For drivers in the Dallas-Fort Worth (DFW) Metroplex, the best auto insurance depends on balancing high liability limits against the region’s unique risks, such as frequent hail storms and heavy commuter traffic. While State Farm and Progressive offer the most competitive rates for commuters, Texas Farm Bureau and USAA consistently lead in customer satisfaction and localized claims handling for North Texas residents.
The DFW Metroplex is one of the most challenging environments for car insurance in the United States. With a population exceeding 8 million people and a sprawling infrastructure that necessitates long daily commutes, drivers in Dallas, Tarrant, Collin, and Denton counties face higher-than-average premiums. Navigating this market requires an understanding of Texas insurance laws, local weather patterns, and the specific offerings of top-tier carriers.
Texas Minimum Insurance Requirements vs. DFW Realities
In 2026, the state of Texas continues to follow the "30/60/25" rule for minimum liability coverage. This means every driver must carry at least:
- $30,000 for bodily injury per person.
- $60,000 for total bodily injury per accident.
- $25,000 for property damage.
However, for a DFW driver, these minimums are often dangerously insufficient. The high cost of medical care in North Texas and the prevalence of expensive SUVs and luxury vehicles on highways like the North Dallas Tollway or I-35 means a standard multi-car pileup can easily exceed $25,000 in property damage.
Furthermore, Texas is an at-fault state. This means the person responsible for the accident is liable for all damages. If your insurance limits are too low, the other party can pursue your personal assets—including your savings and future wages—to cover the difference. Industry experts in 2026 recommend that DFW residents carry at least 100/300/100 limits to ensure adequate protection against the litigious environment of the Metroplex.
Top-Rated Auto Insurance Carriers in the DFW Metroplex
Choosing the "best" insurer involves looking at financial stability, claims processing speed, and localized service. Below are the leading carriers for the DFW region in 2026.
1. Texas Farm Bureau: Best for Customer Service
Texas Farm Bureau remains a standout choice for North Texas. Unlike national giants, this carrier operates with a localized focus. Because it is a member-based organization, it often provides more personalized service. For residents in the outlying suburbs of DFW (like Celina, Forney, or Waxahachie), their rates are frequently the most competitive. Their claims adjusters are deeply familiar with DFW-specific issues like catastrophic hail damage.
2. State Farm: Best for Local Agent Access
With a massive corporate presence in Richardson (CityLine), State Farm is a staple of the DFW economy. They offer a vast network of local agents. This is particularly valuable for drivers who prefer a face-to-face relationship. State Farm’s "Steer Clear" and "Drive Safe & Save" programs have become highly sophisticated by 2026, allowing safe DFW commuters to offset the generally high North Texas premiums with significant telematics-based discounts.
3. Progressive: Best for High-Traffic Commuters
Progressive is often the most price-competitive for drivers who spend significant time on I-635 or the George Bush Turnpike. Their "Name Your Price" tool and robust online interface appeal to the tech-savvy workforce in the Silicon Prairie (Legacy West/Frisco area). Progressive also tends to be more forgiving of minor "fender benders," which are statistically more common in the heavy DFW stop-and-go traffic.
4. USAA: Best for Military Families
If you or a close family member have served in the military, USAA is almost always the gold standard. With the Naval Air Station Joint Reserve Base in Fort Worth, a large portion of the DFW population is eligible. USAA consistently ranks at the top for claims satisfaction and offers specialized coverage options that address the specific needs of service members.
5. GEICO: Best for Budget-Conscious Drivers
GEICO remains a leader for those prioritizing low premiums above all else. In 2026, their mobile app integration allows for rapid claims filing, which is essential for busy professionals. While they lack the local agent density of State Farm, their overhead efficiency translates to lower base rates for many DFW zip codes.
DFW-Specific Risk Factors Affecting Your Premium
The geography and climate of North Texas play a massive role in how insurance companies calculate your risk.
The Hail Factor
Dallas-Fort Worth is located in the heart of "Hail Alley." Each spring, massive convective storms move through the Metroplex, often producing golf-ball to baseball-sized hail. This makes Comprehensive Coverage a non-negotiable for most DFW drivers. Comprehensive covers "acts of God," including hail, flooding, and theft. In 2026, many carriers have adjusted their comprehensive deductibles specifically for Texas, sometimes offering a separate, higher deductible for wind and hail damage.
Uninsured and Underinsured Motorist (UM/UIM)
Despite strict laws, Texas continues to struggle with a high percentage of uninsured drivers. In the DFW area, the risk of being hit by someone without insurance is statistically significant. UM/UIM coverage is technically optional in Texas, but you must reject it in writing. For DFW drivers, accepting this coverage is critical. It pays for your medical bills and car repairs if the at-fault driver has no insurance or flees the scene (hit-and-run).
Personal Injury Protection (PIP) vs. Medical Payments
Texas law requires insurers to offer at least $2,500 in PIP coverage. PIP is "no-fault" coverage, meaning it pays out regardless of who caused the accident. It covers medical expenses, 80% of lost wages, and even caregiver costs. Given the high speeds on DFW highways and the potential for severe injuries, increasing your PIP limit to $5,000 or $10,000 is a highly recommended safety net for North Texas residents.
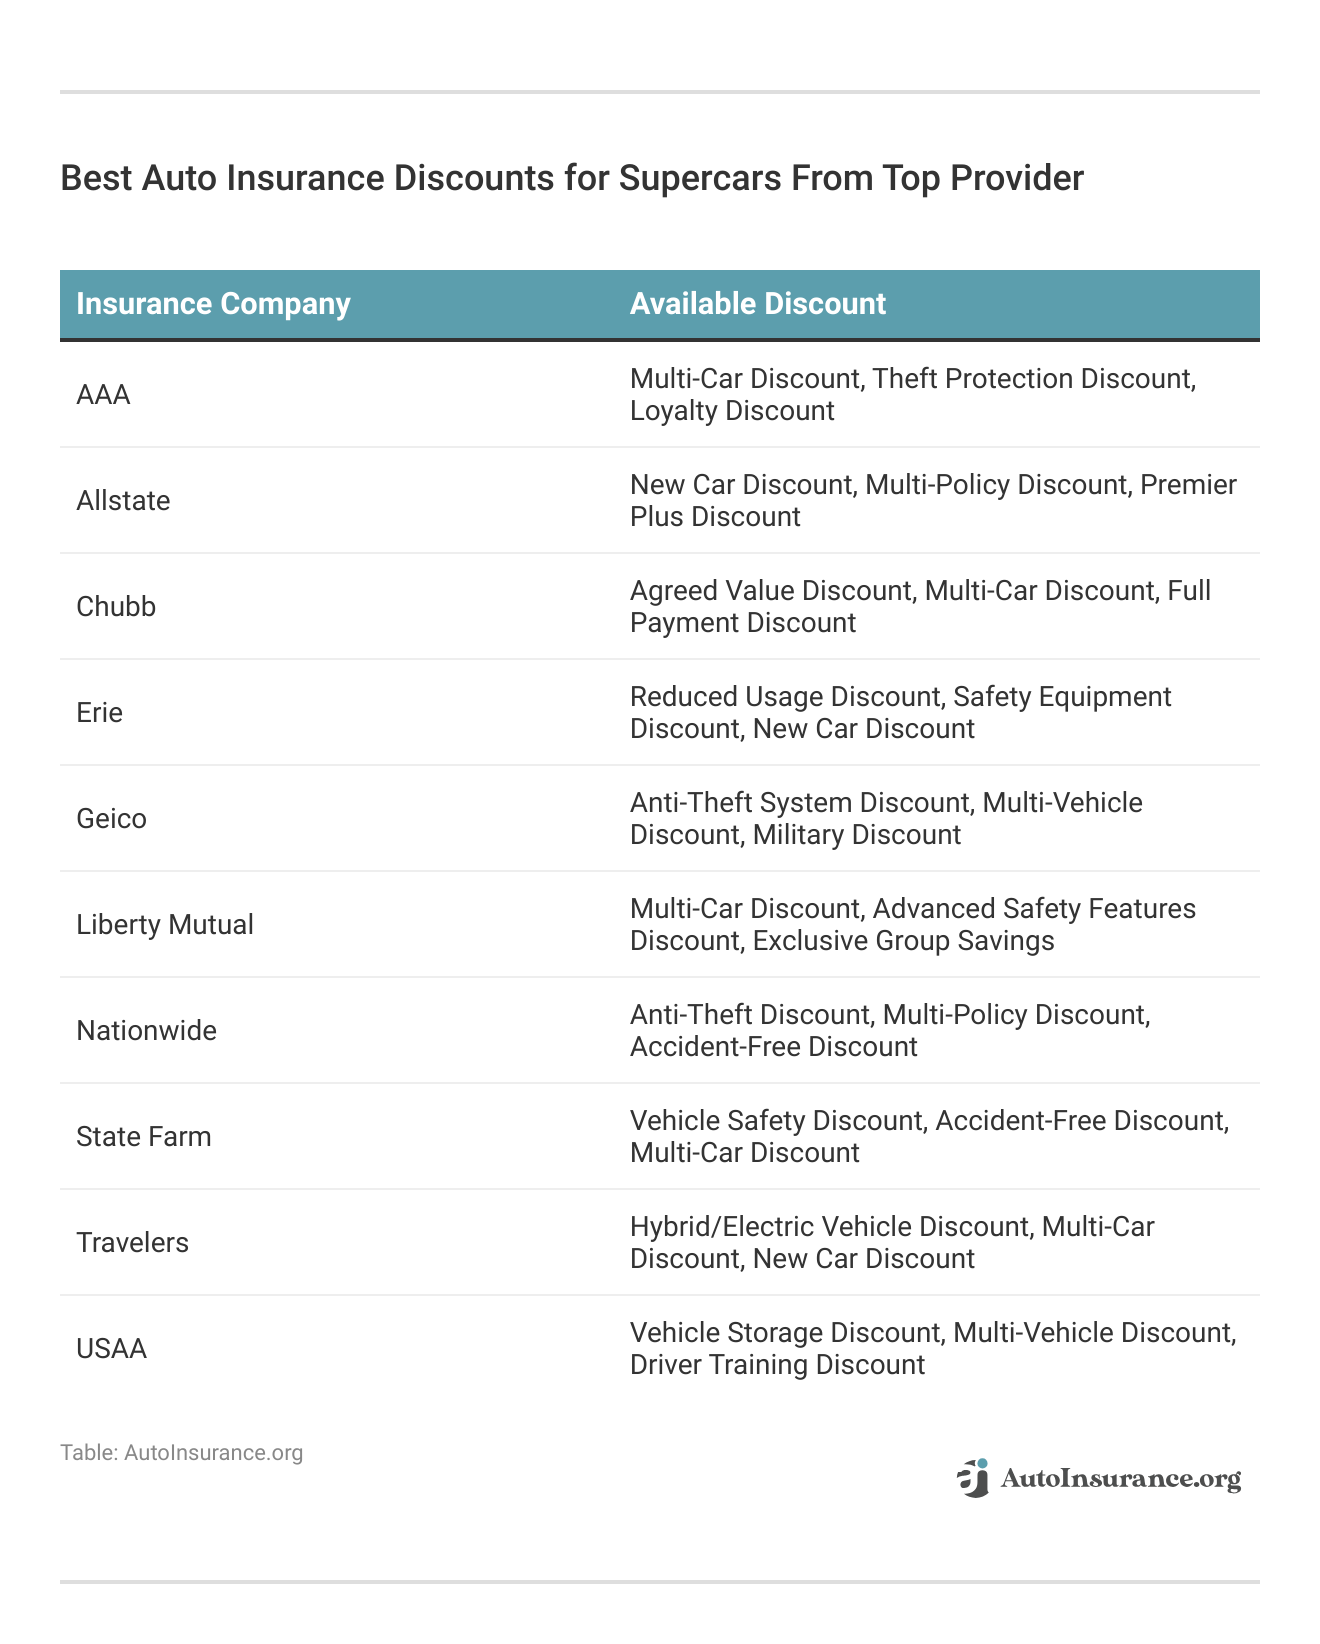
Comparison of Top DFW Insurance Providers (2026 Data)
The following table compares the primary strengths and estimated positioning of top carriers in the DFW market.
| Carrier | Primary Strength | Best For | Technology Rating |
|---|---|---|---|
| State Farm | Local Agent Network | Personalized Service | High (Telematics focus) |
| Progressive | Competitive Pricing | Daily Commuters | Very High (App-centric) |
| Texas Farm Bureau | Regional Expertise | Long-term Residents | Moderate |
| USAA | Claims Satisfaction | Military/Veterans | High |
| GEICO | Low Base Premiums | Budget-focused | High |
| Allstate | Coverage Customization | New Car Owners | High (Milewise options) |
The Impact of DFW Zip Codes on Your Rates
In the DFW Metroplex, your specific zip code can influence your premium by as much as 20-30%. Insurance companies analyze crime rates, traffic density, and the frequency of claims in your immediate area.
- Higher Rates: Zip codes in central Dallas (e.g., 75204, 75201) and areas near the Dallas-Fort Worth International Airport often see higher premiums due to increased theft risks and high-density traffic.
- Lower Rates: Suburban areas with lower population density, such as Flower Mound, Highland Village, or parts of Mansfield, generally enjoy lower insurance costs because the statistical likelihood of an accident or theft is lower.
How to Lower Your Auto Insurance Costs in North Texas
As of 2026, the average cost of insurance in Texas has risen due to increased vehicle repair costs and more frequent severe weather events. However, DFW drivers can take proactive steps to reduce their premiums.
1. Leverage Telematics
Programs like Progressive’s Snapshot or State Farm’s Drive Safe & Save use a plug-in device or smartphone app to track your driving habits. In the DFW area, where traffic can be aggressive, proving you are a cautious, smooth-braking driver can result in discounts of up to 30%.
2. Bundle Home and Auto
Most major carriers in Texas offer significant discounts for bundling. Given the high cost of homeowners insurance in DFW (also due to hail risk), bundling can save hundreds of dollars across both policies.
3. Improve Your Credit Score
Texas allows insurance companies to use credit-based insurance scores to determine premiums. Residents in DFW with "Excellent" credit often pay nearly half the rate of those with "Poor" credit, as insurers correlate financial responsibility with lower driving risk.
4. Opt for a Higher Deductible
If you have an emergency fund, increasing your collision and comprehensive deductibles from $500 to $1,000 can significantly lower your monthly premium. However, given the hail risk in DFW, ensure you can afford the $1,000 out-of-pocket cost at a moment's notice.
Common Pitfalls to Avoid in the DFW Market
When searching for the best auto insurance, many drivers fall into traps that leave them underinsured or overcharged.
- Ignoring the "Texas 2-Step" Compliance: Texas recently moved away from the dual inspection/registration sticker system, but insurance verification is still tied directly to your vehicle registration. Ensure your insurance provider reports your coverage to the TexasSure database immediately to avoid issues with local law enforcement.
- Assuming Minimum Liability is Enough: As mentioned, the 30/60/25 limits are often insufficient for the high-value vehicles found in areas like Plano, Southlake, and the Park Cities.
- Forgetting Flood Coverage: DFW is prone to flash flooding, particularly in low-lying areas near the Trinity River. Ensure your Comprehensive coverage is active, as Liability-only policies will not cover a car totaled by rising water.
Frequently Asked Questions (FAQ)
Is auto insurance more expensive in Dallas than in Fort Worth?
Generally, yes. Dallas often sees slightly higher premiums than Fort Worth due to higher population density, more frequent reported thefts, and higher litigation rates in Dallas County courts. However, the difference is often marginal compared to the impact of individual driving records.
Does my insurance cover hail damage automatically?
Only if you have Comprehensive Coverage. Liability-only policies do not cover weather-related damage. In DFW, because of the high frequency of hail, most lenders require comprehensive coverage if your vehicle is financed or leased.
What happens if I am hit by an uninsured driver in DFW?
If you have Uninsured Motorist (UM) coverage, your insurance company will pay for your repairs and medical bills (up to your policy limits). If you do not have UM coverage and the other driver has no assets, you may be forced to pay for your own repairs out of pocket or through your collision coverage, which carries a deductible.
Are there discounts for DFW commuters?
Yes. Many companies offer "low mileage" discounts if your commute is short. Conversely, if you have a long commute from a suburb like McKinney to Downtown Dallas, telematics programs are your best bet for finding discounts based on your actual driving behavior rather than just the miles driven.
How does the Texas Department of Insurance (TDI) help consumers?
The Texas Department of Insurance regulates the market and provides a "Help Line" for consumers. If you feel a claim has been unfairly denied or a company is acting in bad faith regarding a DFW weather event, the TDI is the official body for filing complaints and seeking mediation.
Recommendation for DFW Drivers
For the average North Texas driver in 2026, the best strategy is to seek quotes from at least three carriers: one national giant (like State Farm), one tech-focused insurer (like Progressive), and the Texas Farm Bureau. Prioritize a policy that includes at least 100/300/100 liability limits, Full Comprehensive coverage with a manageable hail deductible, and Uninsured Motorist protection. In the volatile DFW driving environment, the "cheapest" policy is rarely the best value when a major incident occurs on the Metroplex highways.
Image Gallery
Select an image to open it in a new tab.


Simon Caldwell
Enterprise Technology and Systems Editor
