Navigating Auto Insurance Brokers in Waterloo Ontario: Your Comprehensive Guide to Finding Coverage
Finding the right auto insurance coverage in Waterloo, Ontario, requires understanding the local regulatory environment, comparing policy options across multiple providers, and leveraging independent brokers who can shop the market on your behalf. Unlike direct-to-consumer insurance companies that represent only one brand, independent auto insurance brokers in Waterloo work with numerous licensed insurers to help drivers secure tailored protection, evaluate mandatory accident benefits, and optimize premiums based on driving history, vehicle type, and coverage limits.
Understanding the Role of Auto Insurance Brokers in Waterloo, Ontario
The Ontario auto insurance landscape is heavily regulated by the Financial Services Regulatory Authority of Ontario (FSRA). Within this framework, navigating the marketplace can become complex for drivers trying to balance mandatory legal requirements with adequate personal protection. Auto insurance brokers act as licensed intermediaries between consumers and insurance companies. Their primary function is to analyze a client’s specific needs, assess risk profiles, and source competitive quotes from a network of insurance carriers.
Unlike captive agents who sell policies for a single insurance corporation, independent brokers represent multiple insurance providers. This structural independence allows them to provide objective advice. If one insurer increases its rates disproportionately for a specific demographic or vehicle category in Waterloo, a broker can seamlessly transition the policyholder to a more competitive alternative during the annual renewal cycle. Furthermore, brokers provide professional advocacy if a claim arises, guiding policyholders through the documentation, communication, and settlement processes with the underwriting company.
Mandatory Minimum Requirements and Optional Coverages in Ontario
Every vehicle operated on public roadways in Ontario must carry a legally mandated minimum level of automobile insurance. Understanding these statutory requirements is essential before consulting with a Waterloo insurance broker.
The standard Ontario Automobile Policy (OAP 1) comprises four mandatory coverage pillars:
- Third-Party Liability: Protects you if you are sued or held responsible for injuring someone or damaging someone else's property. The statutory minimum in Ontario is $200,000, though brokers routinely recommend increasing this limit to $1,000,000 or $2,000,000 to protect personal assets from catastrophic legal judgments.
- Statutory Accident Benefits: Provides financial support for medical expenses, rehabilitation, attendant care, caregiver expenses, and income replacement if you are injured in an automobile accident, regardless of who is at fault.
- Direct Compensation - Property Damage (DCPD): Covers damage to your vehicle and its contents, as well as loss of use, when you are not at fault in a collision, provided the accident occurred in Ontario and involves another insured vehicle. Under DCPD rules, you collect from your own insurer.
- Uninsured Automobile Coverage: Protects you and your family if you are injured or killed by an uninsured motorist or a hit-and-run driver.
Beyond these statutory minimums, drivers frequently purchase optional endorsements (known as Endorsements or OPCFs) and physical damage coverages. These include collision coverage (for accidents with other vehicles or objects), comprehensive coverage (for theft, vandalism, fire, or weather events like hail), and specific endorsements such as OPCF 20 (Loss of Use) or OPCF 43/43A (Removal of Depreciation).
Factors Influencing Auto Insurance Rates in Waterloo
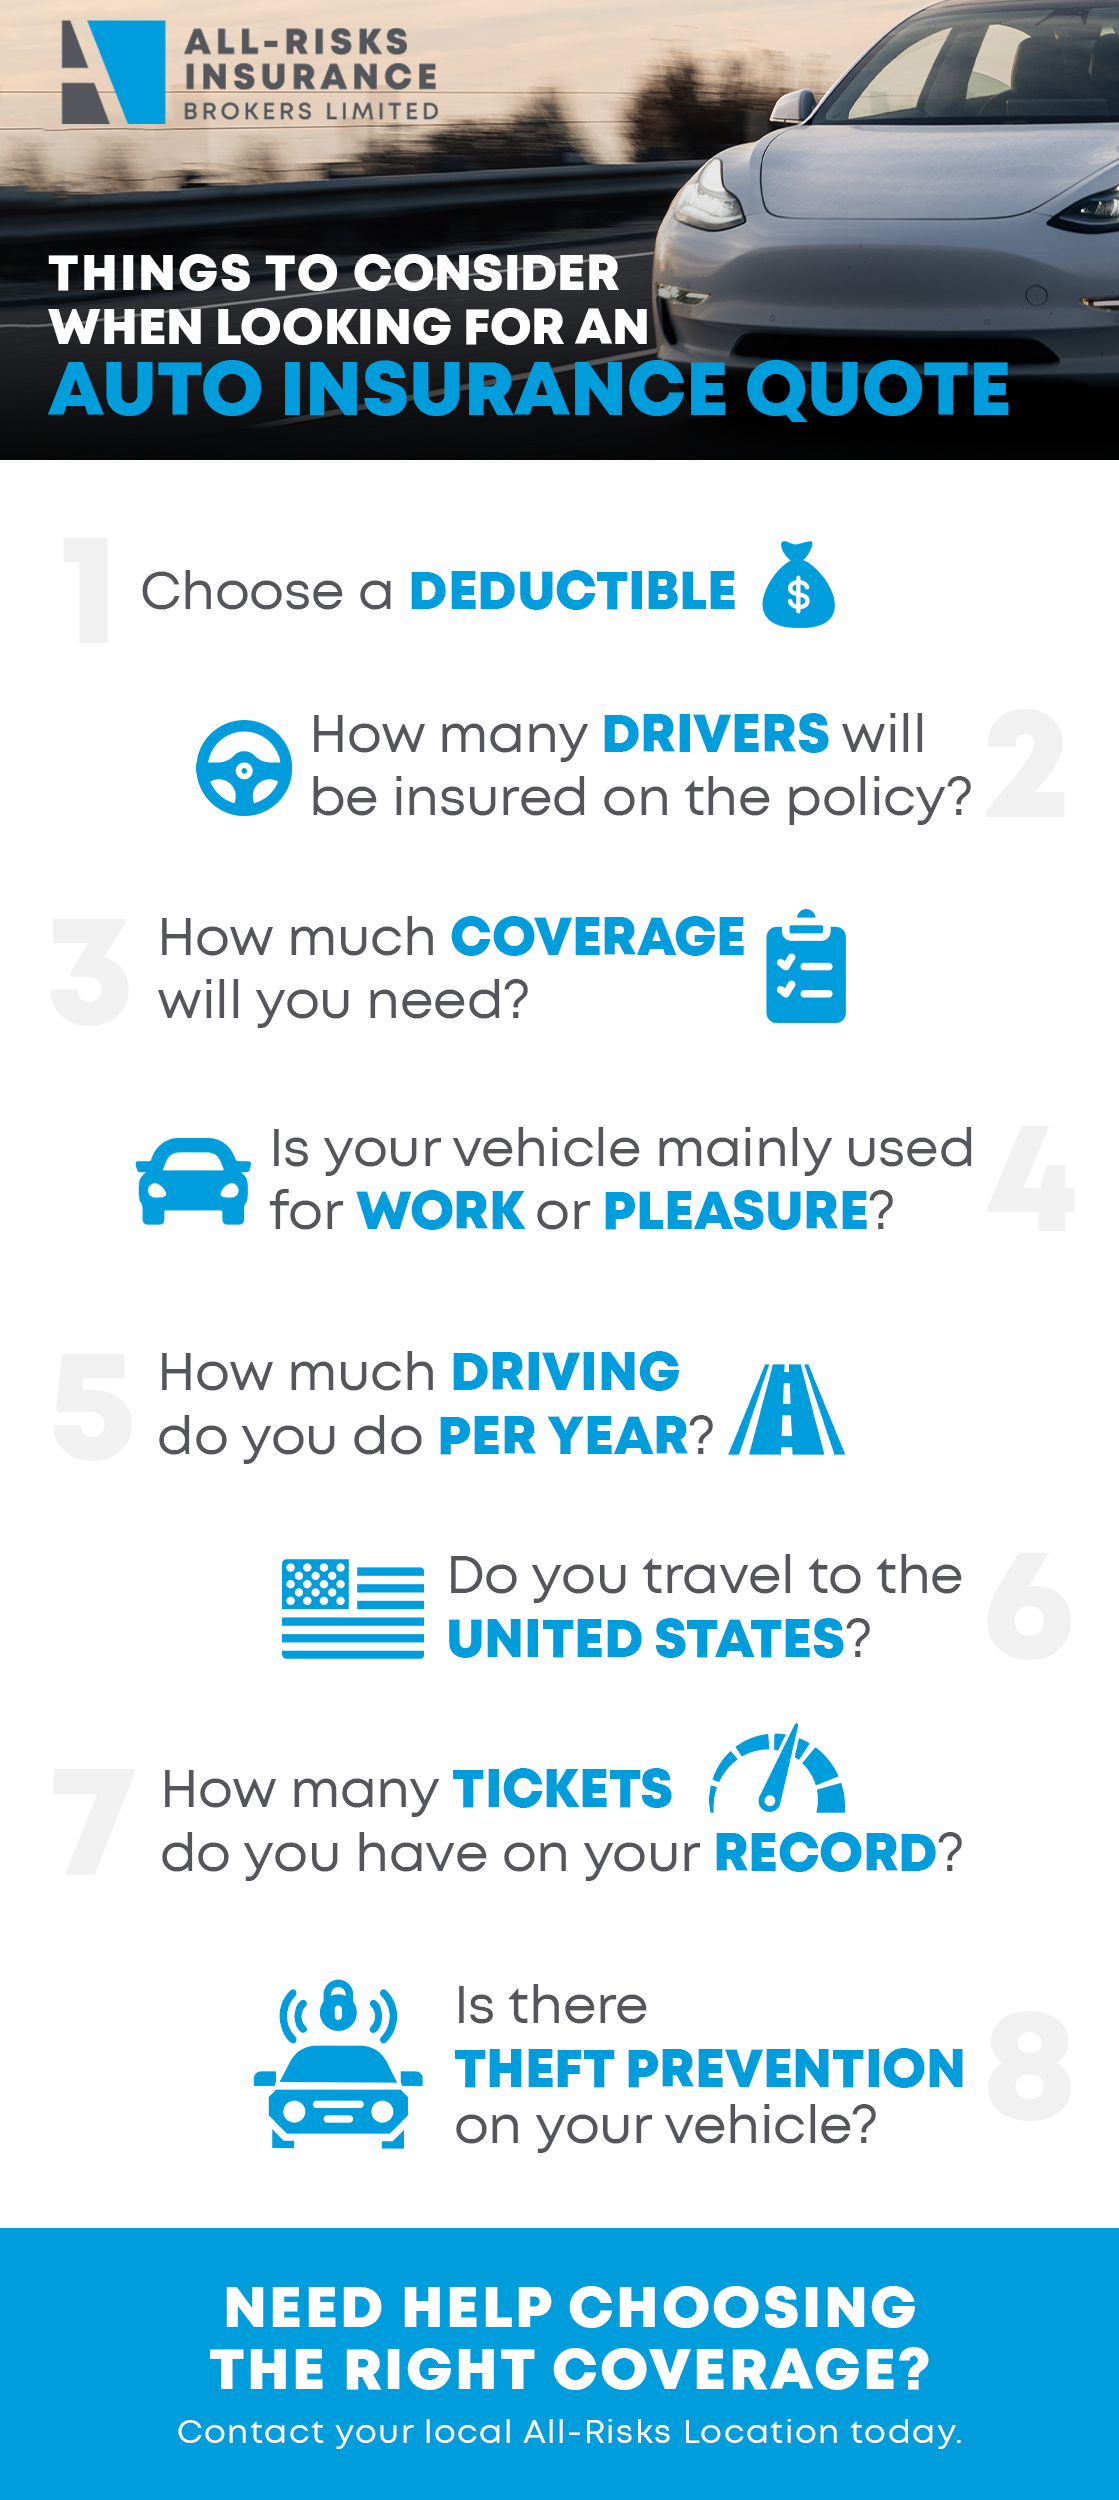
Insurance companies utilize complex underwriting algorithms to determine premium costs. When you work with an auto insurance broker in Waterloo, they will evaluate several key variables that underwriters review:
- Location and Postal Code: Insurance claims statistics vary significantly by municipality and postal code. Urban centers and high-density intersections often experience higher rates of collisions, thefts, and insurance fraud, which directly influences regional pricing.
- Driving Record and Experience: The length of time you have held a valid driver's licence, your moving violation history, and your at-fault collision record dictate your risk classification. Clean driving records over a multi-year period unlock substantial discounts.
- Vehicle Make, Model, and Year: Underwriters analyze historical claims data for specific vehicle models, evaluating repair costs, safety ratings, and theft frequency. High-performance vehicles and frequently targeted SUVs typically command higher premiums.
- Annual Kilometres and Usage: How often and how far you drive matters. Commuting long distances to work or school increases exposure risk compared to occasional pleasure driving.
- Coverage Selections and Deductibles: Choosing higher deductibles (the out-of-pocket amount you pay before insurance applies) or declining optional physical damage coverages on older vehicles will lower your premium, though it increases personal financial exposure.
Comparing Independent Brokers, Direct Writers, and Online Aggregators
When seeking car insurance in Waterloo, consumers generally have three distinct pathways: independent brokers, direct writers (captive agents), and online aggregators. Each approach presents distinct operational dynamics.
| Channel Type | Market Access | Professional Advocacy | Personalization | Primary Focus |
|---|---|---|---|---|
| Independent Brokers | Access to dozens of competing insurance companies. | High level of advocacy during claims and renewals. | Highly customized based on independent risk analysis. | Finding optimal coverage and value across the open market. |
| Direct Writers | Limited strictly to one brand's proprietary products. | Dependent on company employee protocols. | Constrained within single-company underwriting rules. | Selling proprietary products for a single corporate entity. |
| Online Aggregators | Variable; often surfaces preliminary rate estimates. | Minimal to none; self-serve platform. | Automated quoting based on simplified user inputs. | Lead generation for partner insurers and brokerages. |
Working with a local broker bridges the gap between digital convenience and human expertise. While online quote tools provide a quick snapshot, they frequently fail to account for nuanced discounts, complex driving histories, or specific policy endorsements that can significantly impact coverage adequacy.
Step-by-Step Process for Working with a Waterloo Auto Insurance Broker
Engaging an insurance broker is a collaborative process designed to match your specific risk profile with an appropriate underwriter. Understanding what to expect during this journey ensures a smooth transaction.
- Gather Documentation: Before contacting a brokerage, compile your current auto insurance policy declarations page, driver's licences for all household drivers, the vehicle identification number (VIN), current odometer readings, and details of any past claims or moving violations within the past six to nine years.
- Initial Consultation and Needs Assessment: Discuss your driving habits, budget constraints, and risk tolerance with the broker. Be transparent about your driving history; omitting past tickets or claims can lead to denied coverage or policy cancellation later.
- Market Analysis and Quoting: The broker queries multiple insurance partner networks to compare rates and policy wordings. They evaluate which insurers offer the best pricing for your specific demographic in Waterloo.
- Reviewing Policy Options: Your broker presents selected quotes, explaining the differences in deductibles, optional endorsements, and coverage limits. This is the optimal time to ask questions about accident forgiveness or family protection endorsements.
- Application and Binding: Once you select a policy, the broker completes the formal application paperwork, collects initial payment details, and issues temporary liability cards (pink slips) while the formal policy is processed by the underwriter.
Common Mistakes to Avoid When Buying Auto Insurance
Navigating insurance purchases requires vigilance. Avoiding common pitfalls ensures you remain adequately protected without overpaying:
- Sacrificing Coverage for the Lowest Price: Selecting the bare minimum statutory coverage to achieve the lowest monthly premium can leave you severely exposed if a serious accident results in multi-million dollar lawsuits or extensive medical rehabilitation needs.
- Failing to Disclose All Household Drivers: Every licensed driver living in your household must be disclosed to your insurer. Failing to list a spouse, child, or roommate who operates your vehicle can invalidate your coverage in the event of a claim.
- Inaccurate Annual Mileage Estimates: Underreporting your daily commute or annual kilometres driven to secure a lower rate constitutes misrepresentation and can jeopardize claim settlements.
- Overlooking Available Discounts: Many drivers miss out on cost-saving opportunities, such as winter tire discounts, multi-policy bundles (combining auto and home insurance), telematics-based safe driving apps, and alumni or professional association discounts.
Frequently Asked Questions About Auto Insurance in Waterloo
Do I have to pay fees to use an auto insurance broker in Waterloo?
Independent auto insurance brokers in Waterloo typically do not charge consumers direct consultation or brokerage fees for standard personal lines insurance. Instead, they are compensated through standard commissions paid by the insurance carrier underwriting your policy. If a broker deals with specialized high-risk markets or surplus lines that require specialized service fees, they must disclose these charges transparently before binding coverage.
How often should I review my auto insurance policy with my broker?
You should review your auto insurance policy at least annually before your renewal date, as well as whenever you experience a major life event. Significant changes include moving to a new address, purchasing a different vehicle, adding a new driver to your household, changing your employment commute distance, or experiencing a change in your marital status.
What is a telematics discount, and how does it work?
A telematics program (often referred to as usage-based insurance or UBI) tracks your actual driving habits using a mobile smartphone application or a plug-in device installed in your vehicle's diagnostic port. The program monitors metrics such as speed, rapid acceleration, hard braking, cornering, and time of day driven. Safe driving habits documented through these programs can earn policyholders significant initial signup discounts and ongoing renewal savings.
Can a broker help me if I have a poor driving record or multiple tickets?
Yes. Drivers with high-risk classifications, multiple speeding tickets, or at-fault accidents often face prohibitive rates or rejection from standard insurance markets. Specialized brokers maintain access to high-risk (non-standard) auto insurers and can navigate specialized markets to secure legally compliant coverage while you work to improve your driving record over time.
Next Actions and Conclusion
Securing reliable and cost-effective vehicle protection starts with choosing a licensed professional who understands the local insurance climate. Begin by gathering your driving history and vehicle details, then contact an established, independent auto insurance broker in Waterloo, Ontario. Compare multiple quotes, verify that your coverage limits extend beyond statutory minimums to safeguard your personal assets, and review your policy annually to maintain optimal financial protection on the road.
Image Gallery
Select an image to open it in a new tab.

Akira Tanaka
International Academic Trends Correspondent
