What a Local Life Insurance Underwriter Really Themselves Do
A local life insurance underwriter evaluates risk for individuals within a specific geographic or regional market, balancing actuarial data with localized lifestyle factors to price policies accurately. Unlike remote national algorithms, a community-focused or regional insurance professional considers local medical networks, regional environmental variables, and localized economic data to determine policy eligibility and premium costs.
The Core Identity of a Regional Risk Assessor
When individuals apply for life insurance, they often picture an automated computer system spitting out a rate based on age, height, and weight. While digital processing dominates large-scale direct-to-consumer term policies, the reality of life insurance underwriting involves a complex human element, particularly at the local or regional level. A local life insurance underwriter is the gatekeeper of financial security for mutual and stock insurance companies operating within designated communities. Their primary job is to assess the mortality risk of prospective policyholders and determine whether the insurance carrier will offer coverage, under what terms, and at what price.
Understanding what these professionals do requires looking past the broad definitions found in corporate handbooks. Underwriters do not sell policies; they protect the financial reserves of the insurance pool. They sit between the sales agent, who wants to close a deal and secure a commission, and the company’s actuaries, who calculate long-term statistical probabilities. The local underwriter must bridge these worlds by applying national guidelines to individual human lives, factoring in local realities that broad statistical models might miss.
Daily Responsibilities: Beyond the Medical Records
The daily workflow of an underwriter is structured, analytical, and heavily dependent on document review. While medical data forms the core of any file, a comprehensive risk evaluation encompasses a wide array of verification tasks.
Reviewing Medical and Financial Data
The bulk of an underwriter’s day involves examining attending physician statements (APS), lab results, prescription database checks, and motor vehicle reports. For larger whole life or universal life policies, they also pore over personal financial statements, tax returns, and business valuations to ensure the requested death benefit aligns with an insurable interest.
Investigating Regional Risk Variables
A local underwriter evaluates factors unique to their operating area. For instance, if an applicant works in a regional industry—such as commercial fishing in the Pacific Northwest, oil extraction in the Permian Basin, or specialized manufacturing in the Midwest—the underwriter understands the specific safety protocols, occupational hazards, and local labor statistics associated with that trade. They know which regional medical centers provide top-tier care for specific chronic conditions and how local lifestyle habits influence longevity.
Interacting with Producers and Medical Examiners
Underwriters spend a significant amount of time communicating with insurance agents (often called producers) and independent medical examiners. If a lab test returns an anomaly—such as elevated liver enzymes or unexpected blood glucose levels—the underwriter decides whether to request a re-test, ask for a specialist's questionnaire, or decline the application outright.

How Local Underwriters Differ from National Algorithmic Systems
The insurance industry has experienced a massive shift toward automated underwriting, where algorithms instantly approve applicants based on predictive data models. However, local and regional underwriting remains vital for complex cases, high-net-worth estate planning, and non-traditional risk profiles.
| Feature | Automated / National Underwriting | Local / Regional Underwriting |
|---|---|---|
| Primary Driver | Algorithmic scoring and big data | Human judgment supplemented by data |
| Flexibility | Rigid guidelines; little room for context | Ability to make discretionary exceptions for unique cases |
| Geographic Insight | General national averages | Awareness of regional medical facilities and local hazards |
| Processing Speed | Instant to a few days for simple cases | Days to several weeks due to manual file review |
| Communication | Automated emails or portal notifications | Direct phone or email contact with agents and brokers |
When an applicant has a complex medical history or an unusual hobby that trips automated flags—such as localized aviation clubs, regional motorsport racing, or rare medical diagnoses—the file goes to a human underwriter. This professional can look at the nuance of the situation, such as an individual's specific safety gear or a physician's optimistic prognosis, rather than relying solely on a rigid underwriting manual.
The Mechanics of Risk Classification
To understand what an underwriter does, one must examine how they categorize human risk. Every applicant who successfully navigates the underwriting process is assigned a risk classification. These classifications directly dictate the premium cost the policyholder will pay.
Preferred Plus / Preferred Best
Reserved for individuals with optimal health, an exceptional family medical history, clean driving records, no history of tobacco use, and standard biometric markers (blood pressure, cholesterol, and body mass index within strict parameters).
Standard Plus / Standard
Assigned to individuals with minor health deviations or family histories that prevent them from reaching top-tier status, but whose health is still well within acceptable parameters for their age group.
Substandard (Table Ratings)
For applicants with chronic health conditions, higher risks, or hazardous occupations. Underwriters use a rating system—often designated by letters or numbers (Table A through J, or Table 1 through 10)—where each table adds a percentage surcharge (typically 25% per table) to the standard base premium.
Postponed or Declined
If the risk is too high, or if a medical condition is currently unstable or undergoing active diagnosis, the underwriter will postpone the decision until the applicant's health stabilizes. In cases of terminal illness or uninsurable risk profiles, the application is officially declined.
Common Misconceptions About Life Insurance Underwriting
Several myths persist regarding what happens behind closed doors in an underwriting department. Clearing up these misconceptions helps applicants navigate the process more effectively.
- Underwriters are trying to deny claims in advance: In reality, underwriters want to approve as many policies as possible safely because insurance companies make money by writing business. Their goal is accurate pricing, not rejection.
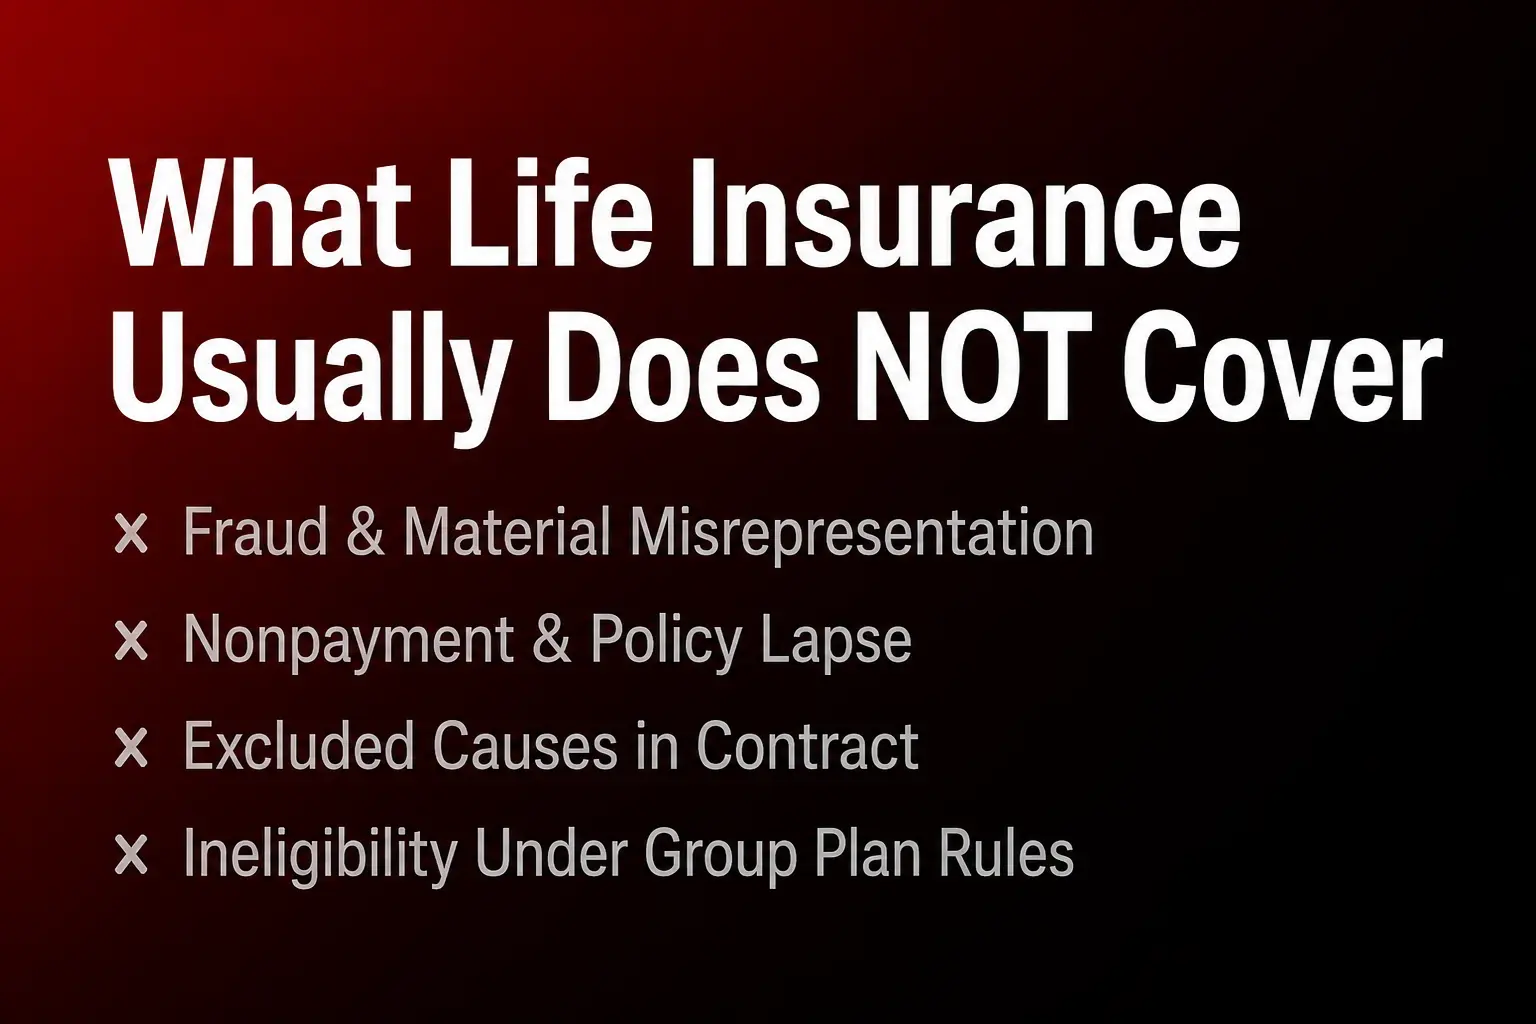
- Minor errors on an application are grounds for instant fraud charges: While misrepresentation is serious, underwriters understand that memory lapses happen. However, intentional concealment of material facts (such as recent hospitalizations or active tobacco use) will lead to a decline or policy rescission during the contestability period.
- All insurance companies use the exact same underwriting manual: While reinsurers provide foundational mortality tables, every insurance carrier maintains its own proprietary underwriting guidelines. An applicant declined by one carrier for a specific condition might find favorable terms with another company whose underwriter has a different risk appetite.
Navigating the Underwriting Process: What Applicants Should Expect
For those applying for coverage that requires manual underwriting, preparation is essential. Understanding the steps can prevent unnecessary delays.
- Disclosure Transparency: Answer every question on the application accurately and completely. Underwriters cross-reference applications with databases like the Medical Information Bureau (MIB) and prescription history databases; discrepancies cause immediate red flags.
- Paramedical Exam Preparation: Fasting when requested, avoiding strenuous exercise or excessive sodium prior to blood draws, and getting adequate sleep can noticeably impact short-term biometric markers like blood pressure and cholesterol.
- Patience with Attendant Physician Statements (APS): The longest delays in local underwriting stem from waiting on medical records from doctor's offices. Proactively contacting personal physicians to authorize the release of records can accelerate this stage.
Frequently Asked Questions
What qualifies someone to become a life insurance underwriter?
Most life insurance underwriters hold a bachelor’s degree in finance, economics, mathematics, or nursing. Many pursue professional designations, such as Fellow, Life Management Institute (FLMI) or Academy of Life Underwriting (ALU) designations, which require years of specialized study in mortality risk, medical science, and legal compliance.
Can a local underwriter change the price of a policy set by the company?
Underwriters do not arbitrarily set prices; they apply the carrier’s filed rate manuals. However, they have discretionary authority within established corporate guidelines to interpret medical evidence, weigh mitigating factors, and assign the most accurate risk class possible.
Why do underwriters require medical exams for term life insurance?
Medical exams provide an objective, current snapshot of an applicant's biological health. While accelerated underwriting programs use data algorithms to bypass exams for healthy young applicants, traditional physical exams remain necessary to uncover hidden conditions like early-stage kidney disease, diabetes, or elevated cholesterol before they manifest symptoms.
How does geographic location affect life insurance underwriting?
Location impacts underwriting in two main ways: state insurance regulations and regional mortality/health data. Underwriters must comply with state-specific laws governing contestability periods and pricing, and they evaluate regional environmental risks and local healthcare access when assessing overall mortality risk.
What happens if an underwriter finds a discrepancy in my medical records?
If an underwriter uncovers a medical condition or history that was omitted from the application, they will pause the file to investigate. Depending on whether the omission appears intentional or accidental, they may request a letter of explanation, order additional medical testing, or adjust the proposed premium rate to reflect the newly discovered risk.
Final Recommendation
When working through the life insurance procurement process, view the local underwriter not as an adversary, but as a technical risk assessor working to establish a fair, sustainable contract. Transparency is your greatest asset; full disclosure of medical and lifestyle details upfront prevents costly delays and ensures your policy remains fully enforceable when your beneficiaries need it most.
Image Gallery
Select an image to open it in a new tab.


Declan O'Connor
Higher Education and Campus Culture Reporter
