Understanding Progressive Commercial Small Business Liability Insurance

Progressive commercial small business liability insurance provides foundational protection against common operational risks, including third-party bodily injury, property damage, and advertising claims. Operating a small business involves navigating numerous unpredictable financial liabilities, making commercial insurance an essential risk-management tool for safeguarding enterprise assets and ensuring long-term continuity.
The Core Foundations of Small Business Liability
Navigating the landscape of commercial insurance requires a solid grasp of how liability policies protect business owners from third-party claims. Unlike personal auto or homeowners insurance, commercial policies are specifically structured to address the complex exposures associated with commercial operations, customer interactions, physical premises, and product distribution.
Liability arises whenever a business owner, employee, or operational activity causes harm to a third party—such as a customer, vendor, or passerby. Without adequate insurance coverage, a single lawsuit resulting from a slip-and-fall accident, a damaged client server, or a copyright infringement claim can exhaust business capital, force asset liquidation, or trigger bankruptcy. Understanding how carriers like Progressive structure these policies helps small business owners select appropriate coverage limits and endorsements tailored to their specific operational risk profile.
Key Components of Progressive Commercial Liability Policies
Progressive Insurance offers business owners flexible packages designed to cover various operational vulnerabilities. The primary cornerstone of this protection is General Liability insurance, often referred to as Commercial General Liability (CGL). This coverage forms the base upon which most small business policies are built.
General Liability Insurance (CGL)
General liability insurance covers claims alleging that the business caused bodily injury or property damage to someone else. It is typically divided into several distinct coverage categories:
- Premises Liability: Protects against accidents that occur on your physical business location, such as a customer slipping on a wet floor in a retail storefront.
- Operations Liability: Covers injuries or damages that happen away from your primary premises while conducting business activities, such as a contractor causing damage while working at a client's home.
- Products-Completed Operations: Protects against financial losses or lawsuits arising from products manufactured, sold, or distributed by your business, or services that have been completed, once the incident occurs away from your premises.
- Completed Operations: Covers injury or damage occurring after a service or project has been finished and handed over to the client.
Personal and Advertising Injury
Beyond physical damages, commercial liability insurance addresses intangible harms. Personal and advertising injury coverage protects against non-physical claims such as slander, libel, copyright infringement in advertisements, malicious prosecution, and wrongful eviction. For modern businesses heavily reliant on digital marketing and social media presence, this coverage is increasingly vital.
Damage to Premises Rented to You
Many small businesses lease office spaces, warehouses, or retail storefronts. If a fire or other covered peril originates in your rented space and damages the landlord's property, this specific coverage helps pay for the repairs. It bridges the gap between standard general liability and commercial property insurance.
Understanding Policy Limits and Deductibles
Evaluating commercial liability options requires a clear understanding of financial limits and out-of-pocket costs. Insurance policies do not cover limitless damages; they are bound by specific structural limits that dictate maximum payouts.
- Occurrence Limit: The maximum amount the insurance company will pay for a single claim or incident, regardless of how many people are injured or how much property is damaged in that specific event.
- Aggregate Limit: The maximum total amount the insurer will pay for all claims combined during the entire policy period, which is typically one year. Once the aggregate limit is exhausted, the business is financially responsible for any subsequent claims until the policy renews.
Choosing appropriate limits depends heavily on industry risk, contract requirements, and the value of business assets. Higher limits provide greater security but result in higher premium costs.
Comparing Progressive Commercial Liability Coverages
To help business owners evaluate policy options, the following comparison highlights standard structures available through commercial providers like Progressive.
| Coverage Type | What It Protects Against | Typical Beneficiaries | Common Exclusions |
|---|---|---|---|
| General Liability | Third-party bodily injury, property damage, advertising injury. | Retailers, contractors, consultants, service providers. | Employee injuries, professional errors, vehicle accidents. |
| Business Owner's Policy (BOP) | Combines general liability, commercial property, and business interruption insurance. | Small-to-medium offices, restaurants, retail shops with physical locations. | Professional negligence, commercial auto liabilities, workers' compensation. |
| Professional Liability | Financial losses resulting from errors, omissions, or negligence in professional services. | Consultants, accountants, IT professionals, real estate agents. | Intentional wrongdoing, bodily injury, standard property damage. |
Expanding Protection Beyond Basic General Liability
While general liability is essential, it does not cover every business risk. Progressive and other commercial insurers offer specialized add-ons and companion policies to ensure comprehensive protection.
Business Owner's Policies (BOP)
For many small businesses, purchasing individual policies for liability, property, and business interruption is inefficient and expensive. A Business Owner’s Policy (BOP) bundles these essential coverages into a single package, usually at a lower combined cost. A BOP protects physical assets like inventory, computers, and furniture while providing the foundational liability shield required for daily operations.
Professional Liability (Errors and Omissions)
General liability policies do not cover financial losses caused by professional mistakes, missed deadlines, or faulty advice. If a consultant provides incorrect strategic guidance that causes a client to lose revenue, general liability will not respond. Professional liability insurance (often called Errors and Omissions or E&O) is specifically designed to cover these financial damages and associated legal defense costs.
Workers' Compensation Insurance
In most jurisdictions, businesses with employees are legally required to carry workers' compensation insurance. This coverage pays for medical expenses and a portion of lost wages if an employee is injured or becomes ill on the job. General liability insurance explicitly excludes injuries sustained by your own employees; workers' compensation fills this critical gap.
Commercial Auto Insurance
Personal auto insurance policies typically deny coverage if a vehicle is used for business purposes, such as making deliveries or traveling to client sites. If employees drive personal, rented, or company-owned vehicles for business operations, a commercial auto policy or hired/non-owned auto liability endorsement is necessary to cover resulting accidents and third-party injuries.
Factors Influencing Progressive Commercial Insurance Costs
Insurance premiums are calculated based on a variety of risk factors specific to each enterprise. Understanding these variables helps business owners manage expenses while maintaining adequate protection.
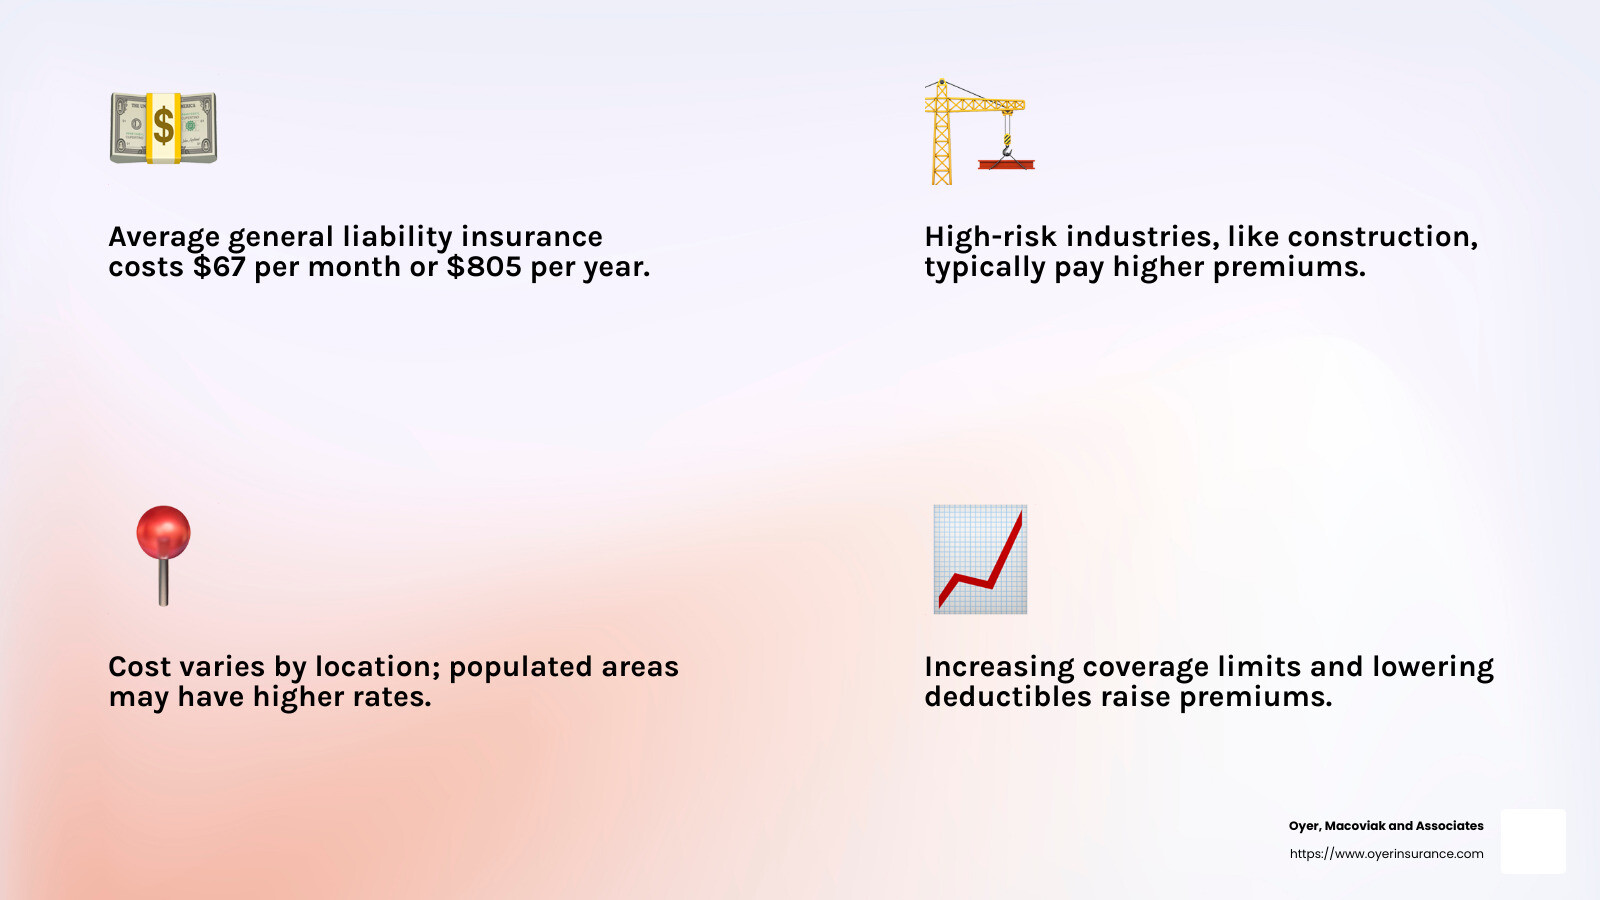
- Industry Classification: High-risk industries, such as commercial construction or roofing, face higher premiums than low-risk operations like digital marketing agencies or consulting firms.
- Business Location: Operating in densely populated urban areas or states with historically higher litigation rates can increase policy costs.
- Payroll and Revenue: Insurers look at the size of your workforce and annual gross revenue as indicators of business volume and operational exposure.
- Claims History: A clean loss history with no prior insurance claims generally results in lower premiums, whereas a pattern of frequent claims signals higher risk to underwriters.
- Coverage Limits and Deductibles: Selecting higher aggregate limits or lower deductibles increases the cost of the policy, while higher deductibles reduce upfront premiums.
Frequently Asked Questions
Does Progressive commercial liability insurance cover independent contractors?
Standard general liability policies generally cover the named insured and employees, but independent contractors or subcontractors working on your behalf are typically not covered unless specifically added via an endorsement or unless they maintain their own independent insurance policies. It is vital to request certificates of insurance from all hired subcontractors.
What is the difference between claims-made and occurrence liability policies?
An occurrence policy covers incidents that happen during the policy period, regardless of when the claim is actually filed—even years after the policy has expired. A claims-made policy only covers incidents that happen and are reported while the policy is active, making tail coverage necessary if the policy is canceled or switched.
Can I bundle my commercial auto and general liability insurance?
Yes, many commercial insurers, including Progressive, offer multi-policy discounts when businesses bundle general liability, commercial auto, property insurance, or a Business Owner's Policy under the same carrier.
Are damages caused by employee negligence covered?
Yes. One of the primary functions of commercial general liability insurance is to protect the business owner from vicarious liability, which includes accidental property damage or bodily injury caused by employees during the normal course of their job duties.
How do I file a commercial liability claim with Progressive?
Claims can typically be reported online through the Progressive commercial portal, by phone, or through an independent insurance agent. You will need to provide detailed incident reports, photographs, witness information, and any correspondence received from the injured party or their legal representation.
Next Actions for Small Business Owners
Securing the appropriate commercial liability coverage requires a systematic evaluation of your operations, contracts, and asset exposure. Begin by reviewing current client contracts to identify mandatory insurance limits and additional insured requirements. Consult with an independent insurance agent or a licensed Progressive representative to conduct a thorough risk assessment, compare bundled BOP options versus standalone policies, and secure coverage limits that align with your enterprise growth and long-term risk management strategy.
Image Gallery
Select an image to open it in a new tab.


Mateo Castillo
Decentralized Finance and E-Payments Strategist
