The Ranking of Michigan in Auto Insurance Rates: A Comprehensive 2026 Analysis
Michigan consistently ranks as one of the most expensive states in the U.S. for auto insurance, frequently occupying the number one or number two spot in national affordability studies. Despite significant legislative reforms enacted in 2019 and 2020, the state’s unique no-fault system, high medical cost requirements, and regional litigation trends continue to keep premiums well above the national average.
Understanding Michigan's Persistent High Ranking
For over a decade, Michigan has been a permanent fixture at the top of insurance cost rankings. To understand why the state remains an outlier, one must look at the structural foundation of its insurance market. Unlike most states that utilize a "tort" system—where the at-fault driver's insurance pays for damages—Michigan operates under a "no-fault" system. In this framework, your own insurance company pays for your medical expenses and lost wages regardless of who caused the accident.
In 2026, Michigan continues to compete with Florida and Louisiana for the title of the most expensive state. While the 2020 reforms introduced PIP (Personal Injury Protection) choice, which allowed drivers to opt out of unlimited medical coverage, the residual costs of the previous "unlimited-only" era and the high cost of healthcare in the state maintain upward pressure on rates. Even for those who choose lower coverage limits, the systemic costs—including the Michigan Catastrophic Claims Association (MCCA) assessment—ensure that Michigan residents pay a significant "location premium" compared to neighbors in Ohio or Indiana.
Comparative Rankings: Michigan vs. The Nation
When evaluating auto insurance rankings, it is essential to distinguish between "minimum coverage" and "full coverage." Michigan's rankings are particularly high for full coverage policies due to the comprehensive nature of the required PIP benefits.
As of 2026, the national average for full coverage auto insurance sits approximately at $2,450 per year. In contrast, Michigan's statewide average often exceeds $3,600, representing a nearly 50% surcharge over the national mean.
State-by-State Comparison (Projected 2026 Data)
| State | Avg. Annual Full Coverage Premium | % Above/Below National Avg. | Primary Cost Driver |
|---|---|---|---|
| Michigan | $3,680 | +50.2% | PIP Benefits / MCCA Fees |
| Florida | $3,590 | +46.5% | High Litigation / Density |
| Louisiana | $3,410 | +39.2% | Lawsuit Climate / Weather Risk |
| New York | $2,950 | +20.4% | Population Density / No-Fault |
| National Average | $2,450 | 0% | N/A |
| Ohio | $1,520 | -37.9% | Competitive Market / Tort System |
This table illustrates the stark reality for Michigan drivers. A resident in Detroit or Grand Rapids can expect to pay more than double what a driver in Columbus, Ohio, pays for similar liability limits, largely due to the regulatory environment rather than driving behavior.

The Role of Personal Injury Protection (PIP) in Rankings
The single largest factor in Michigan’s ranking is Personal Injury Protection (PIP). Until July 2020, Michigan was the only state in the nation that required every driver to purchase unlimited, lifetime medical benefits for auto accident injuries.
In 2026, drivers now have several PIP options:
- Unlimited Coverage: The traditional gold standard, providing lifetime medical care.
- $500,000 Limit: A mid-tier option for those with other health insurance.
- $250,000 Limit: A lower-cost tier.
- $50,000 Limit: Available only to drivers enrolled in Medicaid.
- PIP Opt-Out: Available to drivers with Medicare Parts A and B or qualified health coverage that covers auto-related injuries.
While these choices were intended to lower rates, Michigan remains high in the rankings because a significant portion of the population continues to choose "Unlimited" or high-limit PIP. Furthermore, the medical providers in Michigan are governed by a fee schedule that, while improved by reform, still allows for higher reimbursement rates than Medicare, contributing to the overall premium load.
The Michigan Catastrophic Claims Association (MCCA)
Every Michigan policyholder is familiar with the MCCA fee, though they may not understand its impact on the state's ranking. The MCCA is a nonprofit association that reimburses auto insurers for PIP claims that exceed a specific threshold (currently $630,000).
To fund this, the MCCA charges a per-vehicle annual assessment. In years where the fund has a surplus, this fee is reduced (or refunds are issued, as seen in 2022). However, in 2026, the assessment remains a fixed cost that drivers in other states simply do not have to pay. Because this fee is applied to every insured vehicle, it creates a "floor" for insurance prices, making it impossible for Michigan rates to ever drop to the levels seen in tort-system states like New Hampshire or Wisconsin.
Regional Disparities and the "Detroit Effect"
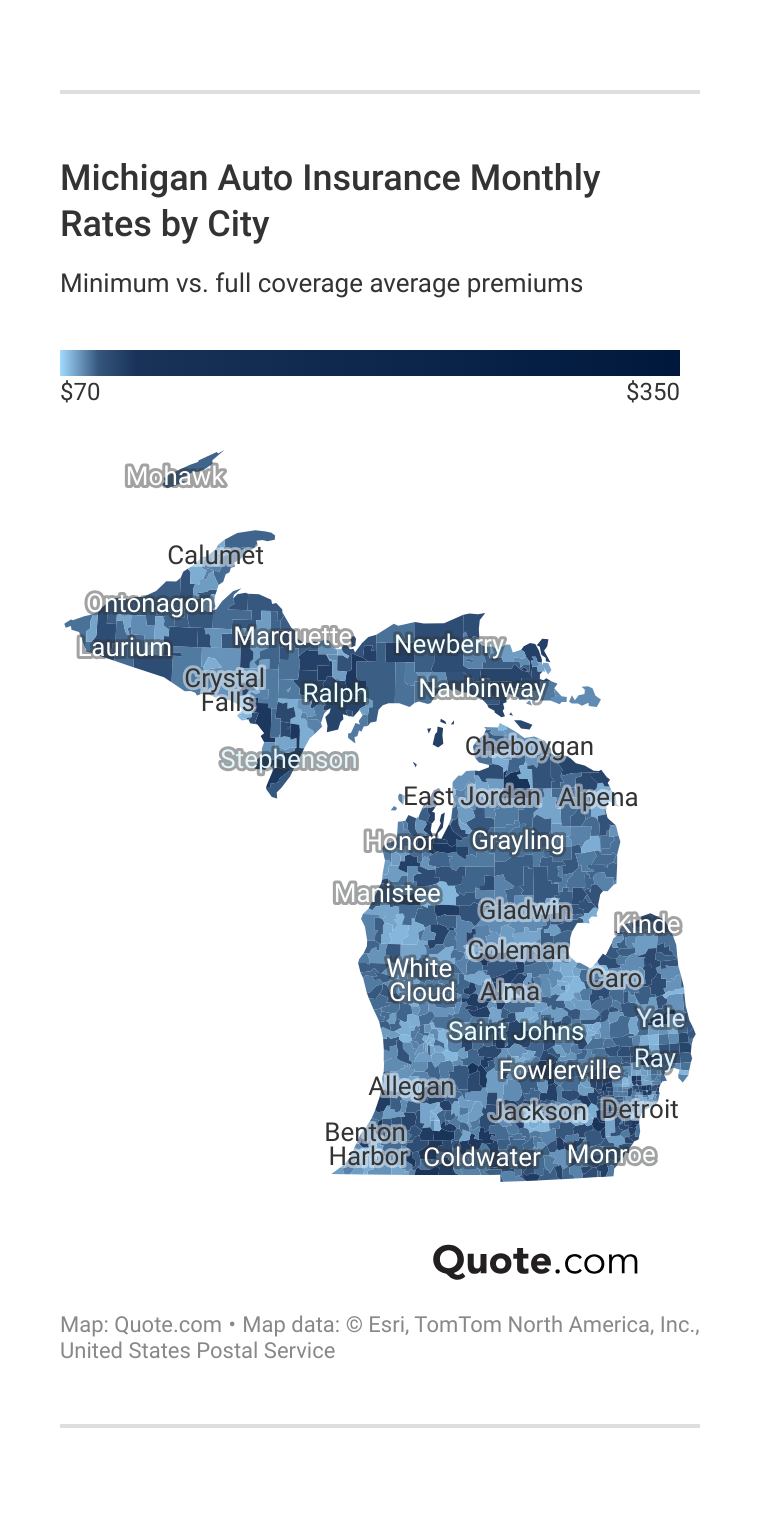
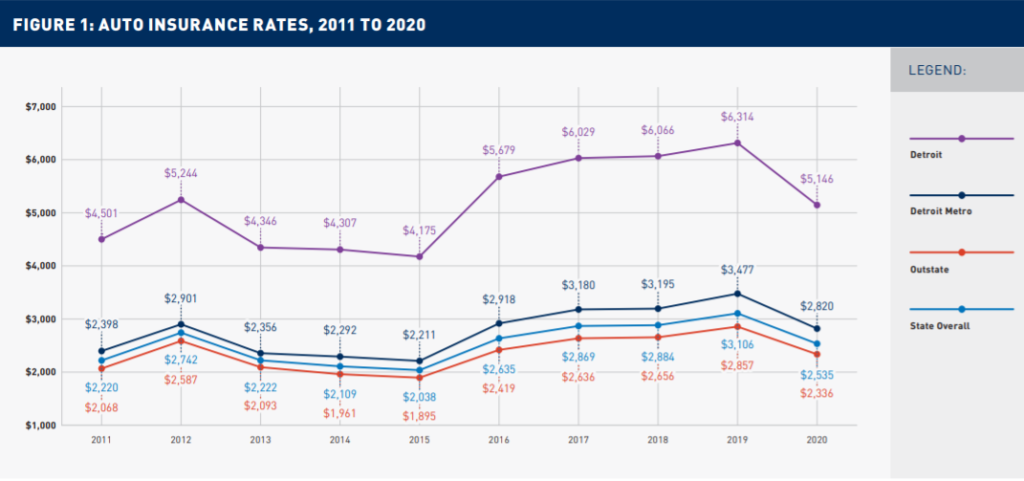
Michigan’s statewide ranking is heavily skewed by specific high-cost regions. Detroit is frequently cited as the most expensive city in America for car insurance. Several factors contribute to this:
- Uninsured Drivers: Estimates suggest that a significant percentage of Detroit drivers operate without insurance. This forces insurance companies to raise rates for those who do pay to cover the risk of accidents involving uninsured motorists.
- Litigation Rates: Higher rates of personal injury lawsuits in the tri-county area (Wayne, Oakland, and Macomb) lead to higher legal defense costs for insurers.
- Theft and Vandalism: Densely populated urban areas face higher actuarial risks for comprehensive claims.
When these urban rates are averaged with more affordable areas like the Upper Peninsula or rural Western Michigan, the state still finishes at the top of national lists. However, a driver in Marquette may find their rates comparable to the national average, while a driver in Detroit may pay five times that amount.
The Impact of Non-Driving Factors on Rankings
Michigan’s 2020 insurance reform also addressed how insurance companies calculate rates. The law prohibited the use of certain non-driving factors, such as:
- ZIP Code (to a limited extent, though "territorial rating" still exists)
- Credit scores (insurers can use "insurance scores," which are different but related)
- Education level
- Occupation
- Gender
Despite these prohibitions, insurance companies have found proxy variables to maintain their risk assessments. The inability to use specific data points has sometimes led to a "leveling up" effect, where rates for low-risk individuals increased slightly to compensate for the inability to precisely segment higher-risk groups. This regulatory friction contributes to Michigan's inability to slide down the national rankings.
Why 2026 Rates Haven't Fallen Further
Expectations following the 2020 reform were that Michigan would drop out of the "top three" most expensive states. By 2026, it is clear that while the rate of increase slowed, the absolute cost did not plummet as some hoped. Several 2026-specific factors explain this:
- Vehicle Complexity: Modern vehicles are equipped with expensive sensors and ADAS (Advanced Driver Assistance Systems). Repairs that cost $500 a decade ago now cost $3,000, impacting the "Collision" and "Comprehensive" portions of the Michigan premium.
- Medical Inflation: The cost of specialized neurological care and long-term rehabilitation—common in auto accidents—has outpaced general inflation.
- Litigation Trends: Michigan has seen a rise in "third-party" lawsuits (suing for pain and suffering), which offsets some of the savings gained from PIP "first-party" reforms.
How Michigan Drivers Can Navigate High Rankings
Given that Michigan will likely remain a high-cost state for the foreseeable future, drivers must take proactive steps to mitigate their individual expenses.
Strategic Coverage Selection
The choice of PIP limit is the most significant lever for price control. Drivers with robust, employer-sponsored health insurance that does not exclude auto accidents can safely opt for lower PIP limits or a total opt-out (if eligible via Medicare). However, this requires careful verification of health insurance terms to avoid a gap in coverage.
Utilization of Telematics
In 2026, Michigan insurers have leaned heavily into "User-Based Insurance" (UBI). By allowing an app or plug-in device to monitor braking, acceleration, and speed, Michigan drivers can often secure discounts of 15% to 30%. In a state with high base rates, a 20% discount translates to hundreds of dollars in annual savings.
Policy Bundling and Loyalty
While shopping around is generally recommended, many Michigan insurers offer significant "multi-policy" discounts for bundling home and auto insurance. Because Michigan’s property insurance market is relatively stable, bundling is often the most effective way to lower the auto portion of the bill.
Frequently Asked Questions
Is Michigan still the most expensive state for auto insurance in 2026?
Michigan typically fluctuates between the 1st and 3rd most expensive state. While recent reforms gave drivers more options to lower their costs, the underlying structure of the no-fault system and the MCCA fees keep Michigan significantly more expensive than the national average.
Did the 2020 insurance reform actually lower rates?
The reform succeeded in providing options for lower rates. Drivers who chose to move away from "Unlimited PIP" saw immediate savings. However, for those who maintained unlimited coverage, rates have remained high or increased due to inflation and the rising costs of vehicle repairs.
Why is Detroit so much more expensive than the rest of Michigan?
Detroit faces a combination of high litigation rates, a higher percentage of uninsured motorists, and greater risks for theft. These factors create a high-risk pool for insurers, which results in premiums that are often double or triple the Michigan state average.
What is the MCCA fee for 2026?
The MCCA fee is adjusted annually based on the fund's projected liabilities for catastrophic injury claims. As of 2026, it remains a mandatory fee for all drivers who choose unlimited PIP, and a lower (often zero or nominal) fee for those who choose limited PIP.
Can I opt out of PIP if I have private health insurance?
Only if your private health insurance is "qualified," meaning it does not exclude auto accident injuries and has a deductible of $6,000 or less per person. You must provide a formal letter from your health insurer to your auto agent to exercise this opt-out.
Practical Recommendation for Michigan Residents
To combat Michigan’s high insurance ranking, the most effective action a driver can take in 2026 is to conduct an annual coverage audit. Do not allow a policy to auto-renew without comparing the "PIP choice" against your current health insurance benefits. If you have moved, changed jobs, or reached a new age bracket (such as turning 25 or 65), your risk profile has changed significantly in the eyes of actuarial tables.
Additionally, consider increasing your collision deductible to $1,000 or $1,500. Because the base cost of Michigan insurance is so high due to the medical components, reducing the "physical damage" portion of the premium through higher deductibles can provide meaningful relief.
Image Gallery
Select an image to open it in a new tab.

Lars Thomsen
Global Labor Markets and Economic Strategy Editor
