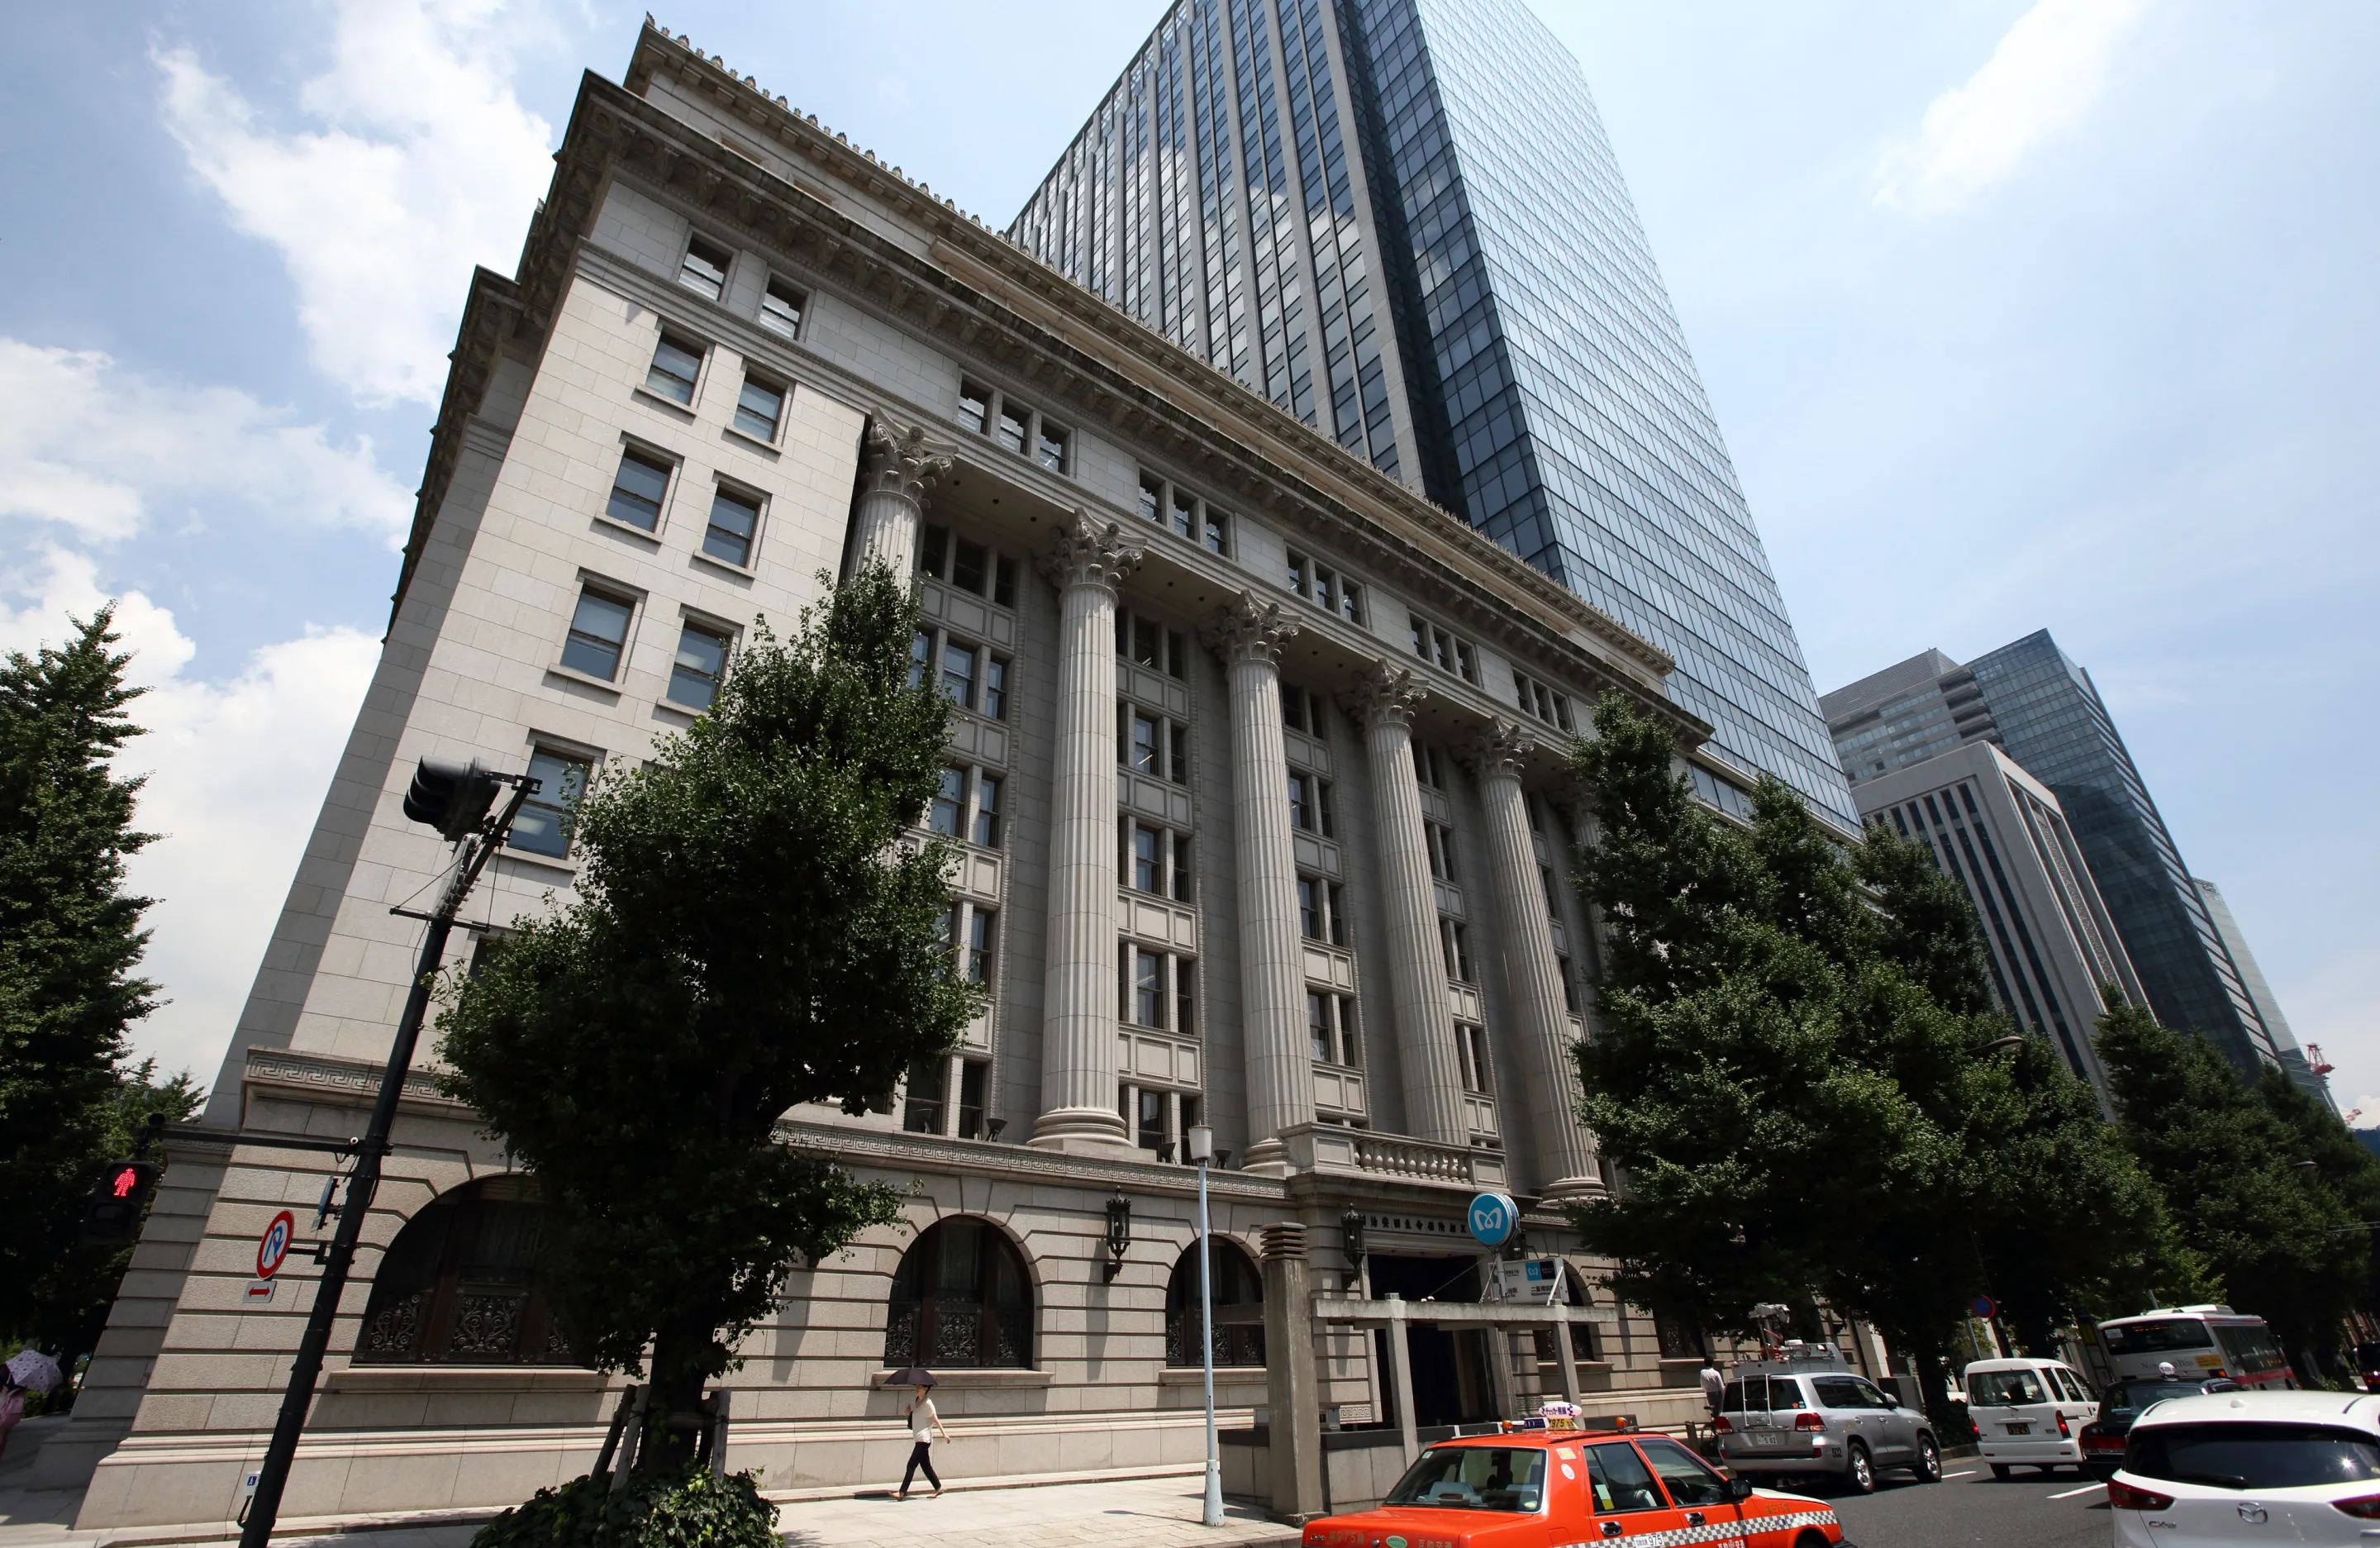
Meiji Yasuda Life Insurance Co is a foundational entity in the Japanese insurance landscape that provides essential financial security through long-term life, medical, and pension products. Understanding its role involves recognizing its status as one of Japan's oldest mutual life insurance companies, its influence on individual asset stability, and its rigorous approach to balancing policyholder protection with sustainable long-term investment strategies.
The Foundations of Meiji Yasuda Life Insurance Co
To understand why Meiji Yasuda Life Insurance Co matters for your future, one must first recognize its scale and historical significance. Formed in 2004 through the merger of Meiji Life Insurance and Yasuda Life Insurance, the organization traces its institutional roots back to 1881. As a mutual company, it is owned by its policyholders rather than external shareholders. This structure is critical because it aligns the company’s fundamental mission with the long-term interests of those it insures rather than the quarterly profit demands of a stock market.
The company operates within a highly regulated environment governed by Japan’s Financial Services Agency (FSA). In an era of economic uncertainty, its longevity and conservative management style serve as a benchmark for stability. For an individual planning for the next several decades, the primary value lies in the company’s ability to remain solvent and responsive through varying interest rate environments and demographic shifts within the Japanese population.
Core Pillars of Future Financial Security
Meiji Yasuda provides a diverse array of financial instruments, but its relevance to your future is best categorized into three specific areas: risk protection, retirement income, and medical contingency planning.
1. Risk Mitigation and Life Protection
The core of life insurance remains the mitigation of financial risk upon the death of the policyholder. For families, this ensures that debt obligations—such as mortgages or educational expenses—do not become insurmountable burdens. Meiji Yasuda’s term and whole life products are designed to provide a predictable payout structure, which is essential for long-term household financial planning. By transferring the risk of early loss to an institution with deep capital reserves, policyholders secure a safety net that protects their dependents.
2. Retirement and Pension Planning
As the average life expectancy continues to rise in 2026, the challenge of outliving one’s savings has become a primary concern for the aging workforce. Meiji Yasuda’s pension products, including individual annuities and endowment policies, function as a hedge against longevity risk. These products allow individuals to contribute systematically during their prime earning years to build a predictable stream of income that supplements the state-provided pension system.
3. Medical and Health Contingency
Medical expenses in Japan are partially covered by the national health insurance system, but significant gaps often exist regarding out-of-pocket costs for specialized treatments, long-term rehabilitation, or advanced medical technologies. Meiji Yasuda’s medical insurance riders provide coverage that bridges these gaps. As healthcare becomes more personalized and expensive, having a policy that covers ancillary costs is a vital component of future medical security.

Comparing Financial Service Strategies
Choosing the right insurance structure requires understanding how your provider manages assets. The following table outlines the key considerations when evaluating life insurance providers in the current financial climate.
| Feature | Mutual Insurance (Meiji Yasuda) | Stock-Based Insurance Company |
|---|---|---|
| Ownership | Policyholders | External Shareholders |
| Primary Goal | Long-term policyholder security | Maximizing shareholder dividends |
| Risk Appetite | Generally conservative/long-term | Often more aggressive for growth |
| Surplus Distribution | Returns to policyholders as dividends | Usually distributed as corporate profit |
| Management Focus | Maintaining solvency for decades | Meeting quarterly performance targets |
Navigating the Policyholder Experience
Understanding your future with Meiji Yasuda requires active engagement with the company’s services. Unlike transactional financial products, a life insurance policy is a contract that will likely span 20, 30, or 40 years.
Periodic Policy Reviews
The most common mistake policyholders make is "set it and forget it" planning. As your life circumstances change—marriage, the birth of children, career advancement, or changes in home ownership—your coverage requirements shift. In 2026, it is recommended to conduct a comprehensive review of your life insurance coverage at least every three to five years. Meiji Yasuda offers consultation services through its agency network and professional advisors who can help adjust policy limits to reflect current financial realities.
Understanding Dividends and Bonuses
Because Meiji Yasuda operates as a mutual company, policyholders may be eligible for dividends depending on the company’s annual performance and the specific terms of their policy. While these dividends are never guaranteed, they represent a potential reduction in the "net cost" of your insurance over the long term. Understanding how these dividends are calculated and whether they are applied as cash payouts or premium reductions is essential for accurate financial forecasting.
The Role of Technology in Modern Insurance
In 2026, the integration of digital tools has streamlined how policyholders interact with their accounts. Meiji Yasuda has expanded its digital portal capabilities to allow for easier access to policy documentation, premium payment tracking, and digital claims filing. The digitization of these processes does not change the underlying risk-pooling nature of insurance, but it does significantly improve the accessibility and transparency of your personal financial data.
When planning your future, ensure that your designated beneficiaries are aware of how to access your digital insurance credentials. Providing a clear roadmap for your heirs is a practical step that ensures the "future" you are planning for actually reaches those you intend to protect.
Potential Limitations and Considerations
While Meiji Yasuda holds a strong market position, no financial institution is immune to macroeconomic pressures. Japan’s prolonged low-interest-rate environment poses a challenge for all life insurance companies, as it limits the yield on the government bonds and other fixed-income assets that typically back traditional life insurance products.
- Inflation Risk: Standard insurance payouts are fixed at the time of policy inception. Over several decades, inflation may erode the purchasing power of that payout. Consider inflation-adjusted riders or supplemental investment vehicles to augment your insurance coverage.
- Regulatory Changes: Changes in tax law or government pension policies in Japan can alter the benefits of holding certain types of insurance products. Always consult with a tax professional regarding how your policy premiums and payouts are treated under current fiscal codes.
- Product Complexity: Life insurance contracts are often dense and laden with legal terminology. Never sign a policy that you do not fully understand. Insist on a detailed explanation of the exclusions, the "free-look" period, and the conditions under which the policy can be surrendered or converted.
Frequently Asked Questions
What happens if I move outside of Japan?
Coverage eligibility often depends on your residency status at the time of policy inception and the terms defined in your contract. Generally, life insurance policies remain active as long as premiums are paid, but you must inform the company of address changes to ensure proper delivery of important legal notices and documentation.
Are my premiums guaranteed to stay the same?
This depends entirely on the type of policy you hold. Term life insurance policies often feature fixed premiums for the duration of the term, while whole life or universal life policies may have different structures. Review your specific policy schedule to determine if your premiums are level or if they are subject to change based on age-banded rate adjustments.
How does a mutual company differ from other insurers?
A mutual company is owned by its policyholders. This structure removes the pressure to generate short-term profits for external shareholders, which often results in a more conservative and stability-focused investment strategy. Profits are kept within the company to strengthen reserves or returned to policyholders through dividends.
Can I change my beneficiaries after the policy starts?
Yes, you generally have the right to change your beneficiaries at any time, provided you are the policy owner. It is critical to update this information whenever major life events occur, such as divorce, death of a beneficiary, or the birth of a child, to ensure the proceeds are distributed according to your current wishes.
What is the difference between a death benefit and cash value?
The death benefit is the amount paid to your beneficiaries upon your passing. The cash value is a component of certain permanent life insurance policies that grows over time as you pay premiums. You may be able to borrow against the cash value or surrender the policy to receive it, though doing so will reduce or terminate the death benefit.
Practical Next Steps for Your Financial Future
To maximize the benefits provided by Meiji Yasuda Life Insurance Co, start by consolidating your documentation. Locate your policy certificates and summary of benefits. Create a secure file that contains these documents alongside your will and power of attorney. If you have multiple policies, create a simple spreadsheet to track the death benefits, annual premiums, and cash values for each.
Schedule an appointment with a certified financial planner or a representative from the company to discuss your current trajectory. Ask specifically about how your current coverage aligns with your goals for the year 2030 and beyond. By treating your insurance policy as a dynamic financial asset rather than a static document, you ensure that it remains a reliable pillar of your long-term security.
Image Gallery
Select an image to open it in a new tab.


Declan O'Connor
Higher Education and Campus Culture Reporter
