Kia Car Loan Rates Explained: What Buyers Need to Know

Securing financing for a new or certified pre-owned vehicle requires understanding how interest rates work, what factors influence monthly payments, and how manufacturer-backed options compare to traditional lenders. Kia car loan rates are determined by a combination of promotional manufacturer incentives, buyer credit profiles, loan terms, and broader macroeconomic conditions.
When shopping for an automobile, navigating financing options can often feel as overwhelming as choosing the vehicle itself. Understanding how Kia car loan rates work helps prospective buyers minimize total interest costs, secure favorable terms, and budget accurately for their monthly expenses. Whether you are looking at a brand-new Telluride, an electric EV6, or a reliable certified pre-owned (CPO) sedan, breaking down the mechanics of automotive lending provides a clear roadmap to a smart purchase.
Understanding Automotive Financing Basics
Automotive financing involves borrowing a principal amount from a lender to purchase a vehicle, which is then repaid over a specified period with added interest. The interest rate, expressed as an Annual Percentage Rate (APR), dictates the true cost of borrowing beyond the vehicle's sticker price.
When evaluating financing offers, buyers generally encounter two primary structures: simple interest loans and pre-computed interest loans. Most modern car loans use simple interest, meaning interest accrues daily based on the remaining principal balance. This structure allows borrowers to save money on total interest by making extra principal payments or paying off the loan early. Conversely, pre-computed interest calculates the total interest owed over the life of the loan upfront, offering fewer savings for early payoffs.
Understanding the components of a monthly car payment requires looking at four variables:
- Principal Amount: The negotiated purchase price of the car, minus any down payment, trade-in value, and added taxes, title, and registration fees.
- Interest Rate (APR): The annual cost of borrowing money, which varies heavily based on creditworthiness and market conditions.
- Loan Term: The duration of the repayment period, commonly ranging from 36 to 84 months.
- Down Payment: The upfront cash contribution paid directly to the dealer, which reduces the total loan amount and lowers monthly obligations.
How Kia Financing Works: Captive Lenders vs. Traditional Banks
Kia buyers generally source financing through two distinct channels: captive lenders like Kia Finance America (formerly known as Hyundai Capital America) or external financial institutions such as banks, credit unions, and online lenders.
Captive finance companies are financial arms closely tied to the automotive manufacturer. Because their primary goal is moving inventory off dealership lots, they frequently offer subsidized promotional rates—such as 0% or low-APR financing—for well-qualified buyers purchasing specific new models. These promotional rates are heavily managed to incentivize sales during specific times of the year or to clear out previous-year inventory.
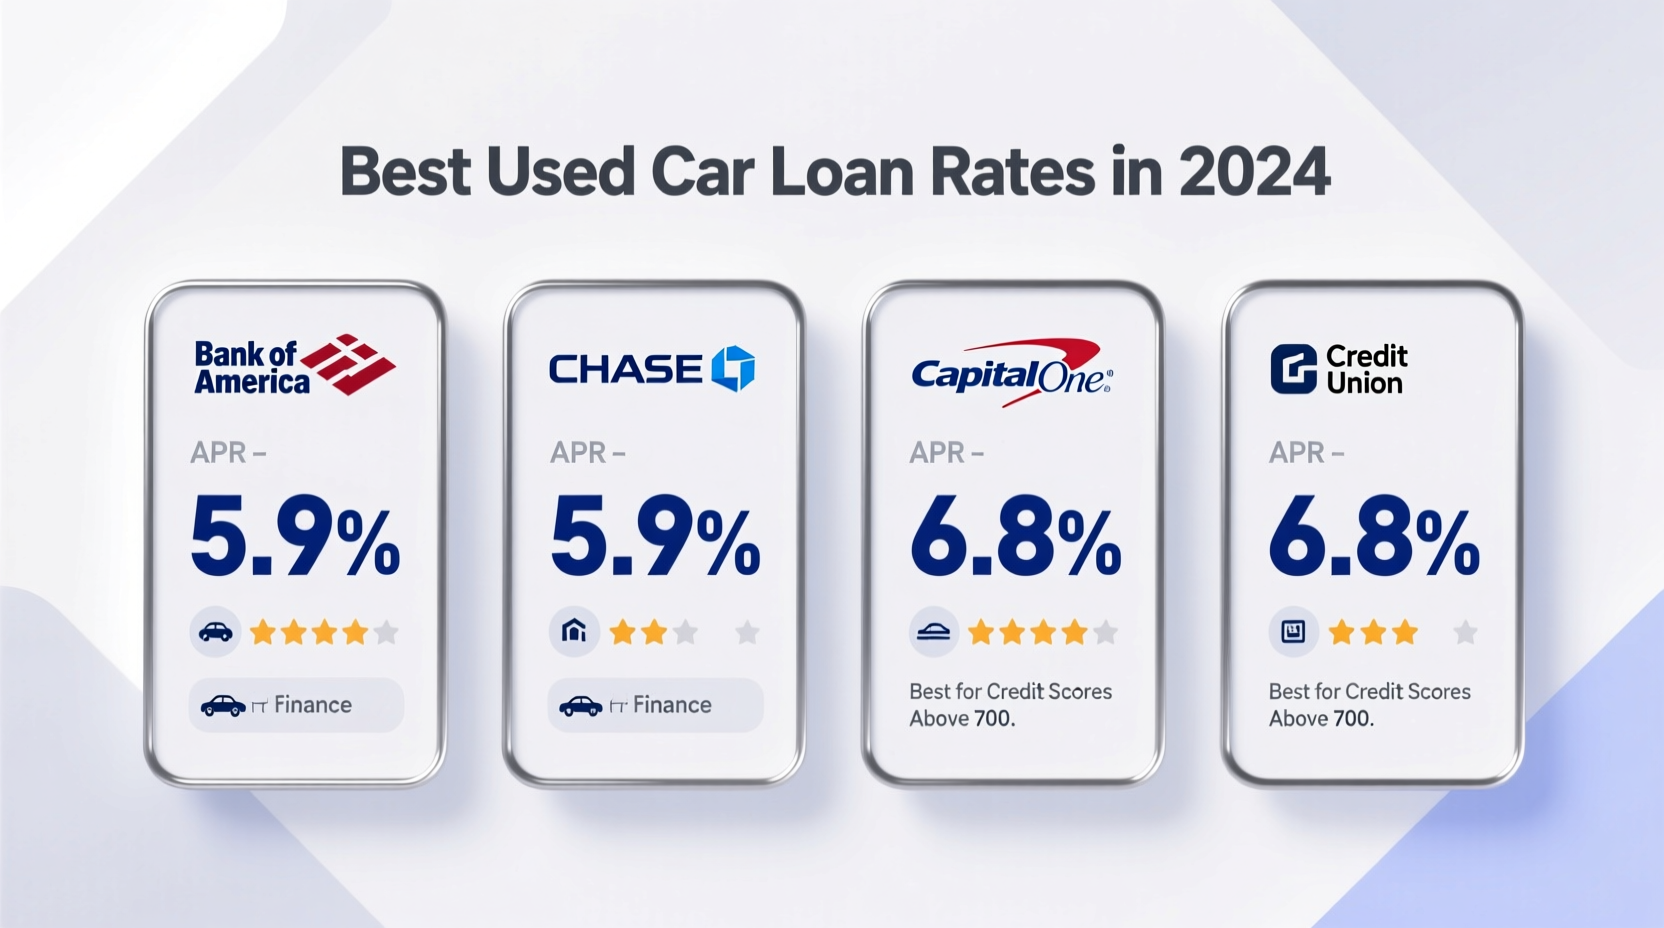
On the other hand, traditional banks and credit unions operate independently of the manufacturer. While they rarely offer 0% promotional rates, credit unions often provide highly competitive baseline rates for buyers with solid credit histories. Securing a pre-approval from an outside financial institution before stepping onto a dealership lot gives buyers a valuable benchmark to negotiate or potentially beat dealer-arranged financing.
Key Factors That Influence Your Kia Car Loan Rate
Lenders evaluate multiple risk factors when determining the specific interest rate offered to an applicant. Knowing these variables allows buyers to prepare their finances before applying for a loan.
Credit Score and History
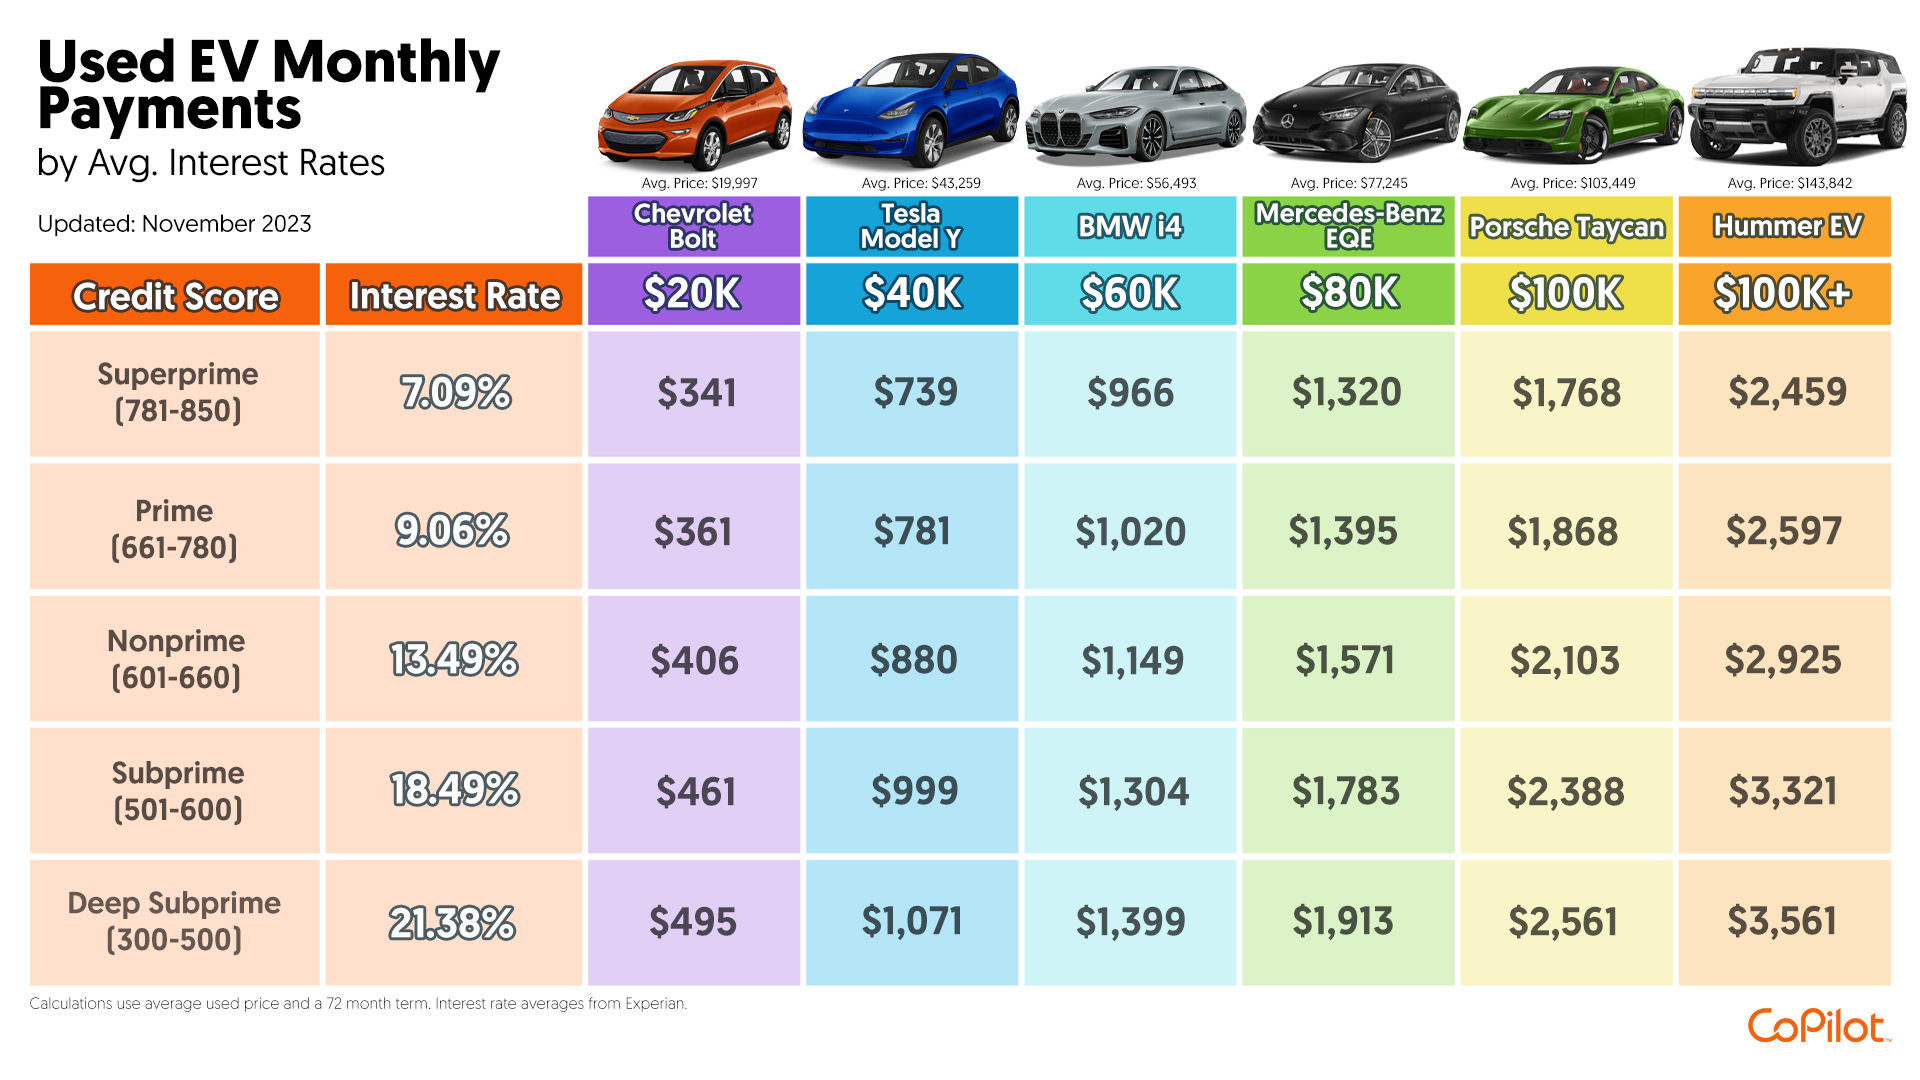
Your credit score is the single most influential factor affecting your car loan rate. Lenders divide applicants into tiers—often ranging from super-prime to deep subprime. Borrowers with credit scores above 740 typically qualify for the lowest available rates, while those with scores below 600 face significantly higher APRs to offset the perceived lending risk. Reviewing your credit report for errors and paying down existing revolving debt a few months prior to applying can noticeably improve your tier placement.
Loan Term Length
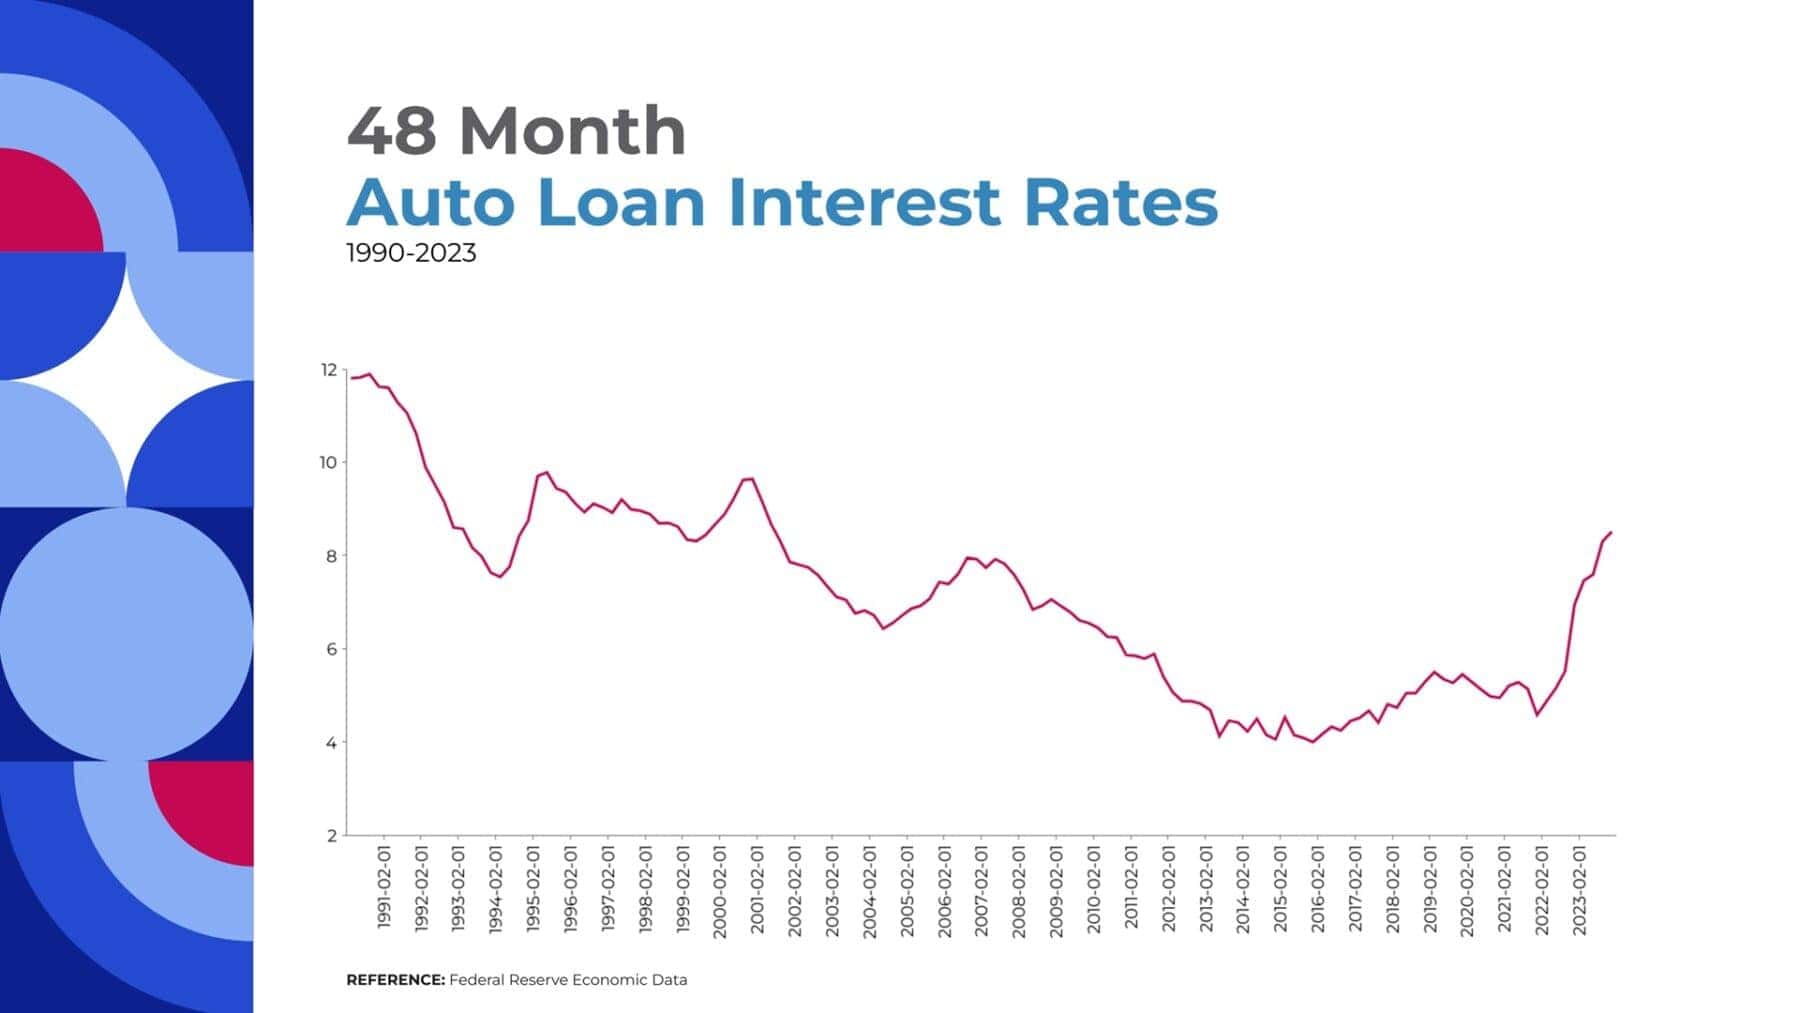
The length of the loan term directly impacts both your monthly payment and your overall borrowing costs. While an 72-month or 84-month loan lowers your monthly payment, it extends the duration over which interest accumulates, substantially increasing the total cost of the vehicle. Furthermore, longer loan terms frequently carry higher interest rates compared to shorter 36-month or 48-month terms because the lender assumes risk over a more extended period.
Down Payment and Trade-In Value
A substantial down payment reduces the loan-to-value (LTV) ratio, signaling lower risk to the lender. Putting down 10% to 20% of the vehicle’s purchase price can often secure a more favorable interest rate tier. Additionally, a strong down payment protects the buyer against immediate negative equity, a scenario where the vehicle depreciates faster than the loan balance decreases.
Vehicle Status: New, Used, or Certified Pre-Owned
Interest rates fluctuate based on whether the Kia vehicle is brand-new, used, or part of the Kia Certified Pre-Owned (CPO) program. New cars generally qualify for the most aggressive promotional rates backed by the manufacturer. CPO vehicles often receive special financing rates through Kia Finance America that mimic new car incentives, whereas standard used cars typically carry higher interest rates due to older model years and higher baseline risk profiles.
| Loan Type / Tier | Typical APR Range | Key Qualifications | Best For |
|---|---|---|---|
| New Car Promotional | 0% – 4.9% APR | Tier 1 Credit (740+), specific models | Buyers wanting maximum savings on new models |
| Certified Pre-Owned (CPO) | 3.9% – 7.9% APR | Tier 1–2 Credit, strict vehicle inspection | Buyers seeking factory-backed used vehicles |
| Traditional Credit Union | 5.5% – 9.5% APR | Good to Excellent Credit, membership required | Buyers wanting flexible terms outside the dealership |
| Standard Used Auto Loan | 7.0% – 18.0%+ APR | Variable Credit Scores, older model years | Buyers purchasing standard used inventory |
Promotional Rates vs. Cash Back Incentives
Car shoppers frequently encounter a common dilemma when evaluating Kia purchase offers: choosing between a promotional low-interest rate or a cash-back rebate. Manufacturers periodically offer a choice between promotional financing (such as 1.9% APR for 60 months) or a substantial cash discount off the purchase price (such as $1,500 cash back).
To determine which option saves more money, buyers must calculate the total cost of ownership under both scenarios. If you finance $30,000 over 60 months, a 1.9% APR yields roughly $1,500 in total interest paid. If the cash-back rebate is also $1,500, but choosing it forces you to take a standard bank loan at 7% APR (which equals roughly $5,500 in interest), the low-interest promotional rate is clearly the superior financial choice. Running these exact amortization calculations before visiting the dealership prevents costly decision-making.
Steps to Secure the Best Kia Car Loan Rate
Preparing strategically for vehicle financing ensures you remain in the driver's seat throughout negotiations. Follow these steps to secure competitive terms:
- Check Your Credit Score: Obtain your credit reports and score well in advance to identify any discrepancies or areas needing improvement.
- Get Pre-Approved Externally: Visit a local credit union or online bank to secure a pre-approved auto loan offer. This establishes a baseline interest rate that dealership finance departments must attempt to beat.
- Research Current Manufacturer Incentives: Visit official manufacturer pages to review active national and regional Kia finance offers, special CPO programs, and seasonal incentives.
- Negotiate the Vehicle Price First: Never discuss monthly payments initially. Focus entirely on negotiating the lowest out-the-door purchase price for the vehicle before introducing financing or trade-ins into the conversation.
- Compare Dealer Financing: Allow the Kia dealership finance manager to run your application through Kia Finance America and their partner lenders to see if they can beat your outside pre-approval.
Common Mistakes to Avoid When Financing a Kia
Avoiding financial pitfalls safeguards your long-term budget and prevents unexpected debt burdens.
- Focusing Exclusively on Monthly Payments: Dealerships can easily manipulate monthly payments to appear affordable simply by stretching the loan term to 84 or 84+ months, dramatically increasing the total interest paid. Always focus on the total purchase price and total cost of financing.
- Skipping the Down Payment: Zero-down loans increase your LTV ratio instantly, leaving you "upside down" (owing more than the car is worth) the moment you drive off the lot.
- Ignoring Additional Fees: Remember to account for state taxes, documentation fees, destination charges, and optional add-ons like extended service contracts or gap insurance, which increase the total amount financed.
Frequently Asked Questions
What credit score is required to get 0% APR on a Kia?
Qualifying for manufacturer-sponsored 0% APR promotional financing typically requires a "Tier 1" or super-prime credit score, generally ranging from 740 and above, alongside a clean credit history with low revolving debt utilization.
Is it better to finance through Kia Finance America or a local credit union?
Neither option is universally superior; it depends on current promotions. If Kia is running subsidized low-APR or 0% incentives on the specific model you want, captive financing is usually cheaper. If buying a used or CPO vehicle, local credit unions frequently offer lower baseline rates than standard dealer partnerships.
Can I refinance my Kia car loan later if interest rates drop?
Yes. Automotive loans are typically simple interest contracts with no prepayment penalties, meaning you can refinance the remaining principal balance with another lender at a later date if market interest rates decline or your credit score improves.
What is gap insurance, and do I need it with a Kia loan?
Guaranteed Asset Protection (GAP) insurance covers the difference between what your insurance company pays if the vehicle is totaled and the remaining balance on your auto loan. It is especially useful if you make a small down payment or finance a vehicle with a high initial depreciation rate.
How do I check for active Kia finance incentives?
Active national and regional promotional offers are published directly on the official Kia corporate website under the shopping and finance tabs, though local dealer participation may vary.
Next Actions and Final Recommendations
Securing a competitive car loan rate for a Kia requires preparation, careful math, and shopping around. Begin by checking your credit score, securing an independent pre-approval from a credit union, and reviewing active manufacturer promotions online. Treat the vehicle purchase price and the financing terms as two separate negotiations, and always calculate the total cost of borrowing over the life of the loan before signing any contracts.
Image Gallery
Select an image to open it in a new tab.



Simon Caldwell
Enterprise Technology and Systems Editor
