Understanding USAA Whole Life Insurance Cash Value Complaints
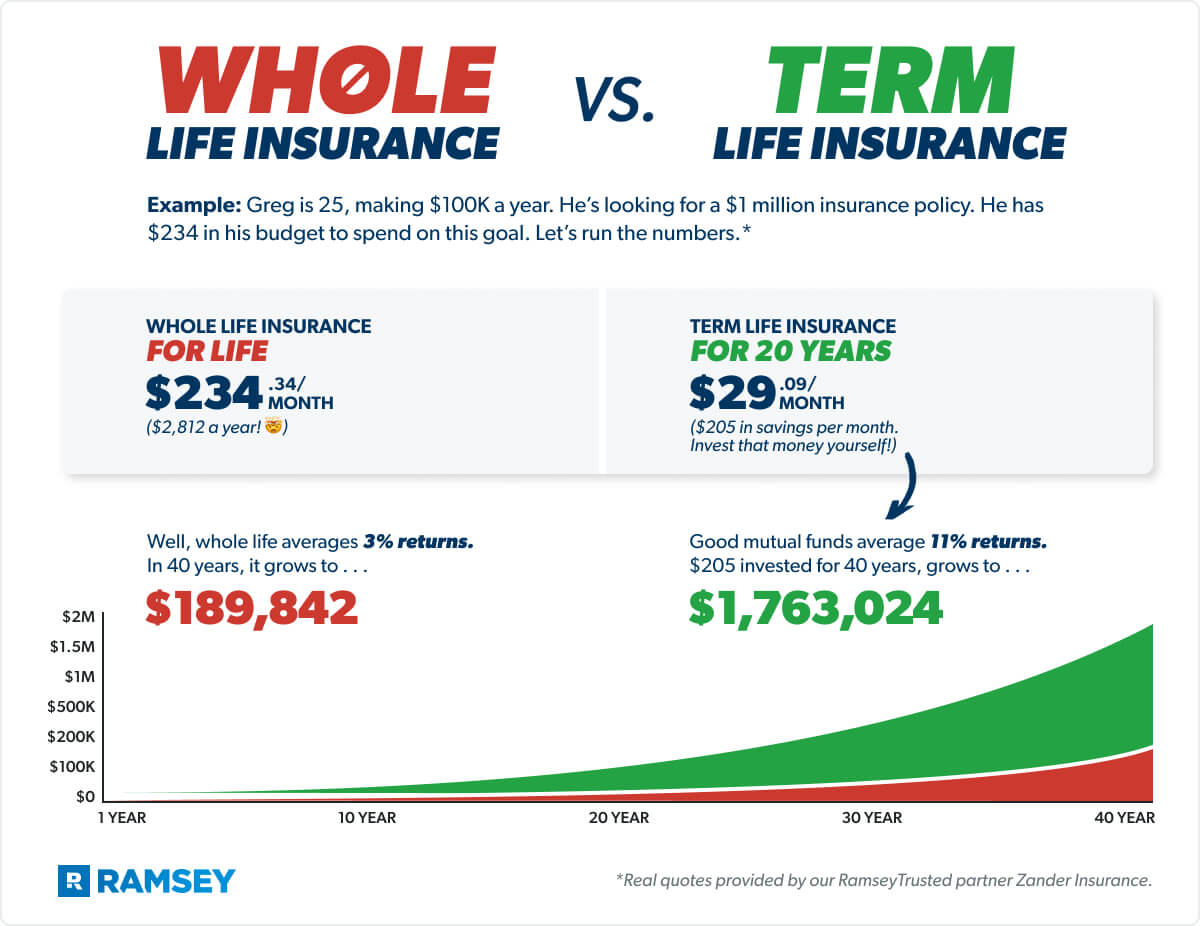
Complaints regarding USAA whole life insurance cash value typically center on the slow rate of initial accumulation, high interest rates on policy loans, and unexpected tax liabilities or surrender charges. Most dissatisfaction arises when policyholders realize that the cash value grows minimally during the first several years due to front-loaded administrative costs and agent commissions.
Whole life insurance is often marketed as a dual-purpose financial tool: it provides a permanent death benefit while simultaneously building a "cash value" component that the policyholder can access during their lifetime. For members of the United Services Automobile Association (USAA), these policies are frequently chosen due to the organization's long-standing reputation for serving the military community. However, as of 2026, many policyholders have voiced concerns regarding the liquidity and growth of these assets.
To navigate these complaints effectively, one must understand the mechanics of permanent life insurance, the specific contractual obligations of USAA Life Insurance Company, and the regulatory environment governing these financial products.
The Structure of USAA Whole Life Cash Value
The cash value in a USAA whole life policy is not a traditional savings account. It is a "living benefit" that represents the equity built up within the policy. In the early years of a policy—specifically years one through five—a significant portion of the premium is directed toward the cost of insurance (mortality charges) and the company’s operating expenses. This leads to the most common complaint: a "zero-balance" or near-zero cash value despite years of premium payments.
By 2026, the financial landscape has seen increased transparency, yet many consumers still find the "illustration" provided at the time of purchase to be confusing. A USAA whole life policy typically guarantees a minimum rate of interest on the cash value. Beyond this guarantee, USAA may pay dividends, which can be used to increase the cash value, pay premiums, or be taken as cash. However, dividends are never guaranteed, and complaints often surface when the "actual" performance of the policy fails to meet the "projected" performance shown in the initial sales illustration.
Guaranteed vs. Non-Guaranteed Values
Every USAA life insurance contract contains a table of guaranteed values. This table outlines the absolute minimum cash value the policy will have at the end of each policy year. The "non-guaranteed" side includes projected dividends. When interest rates in the broader economy are low, or when the insurer's mortality experience is higher than expected, dividends are reduced. Policyholders who relied on optimistic projections often feel misled when their cash value does not reach the expected milestones by 2026.
Primary Sources of Cash Value Dissatisfaction
Understanding why complaints occur requires looking at the specific friction points between the policyholder's expectations and the contractual reality of USAA’s products.
1. The "Early Year" Growth Lag
The most frequent grievance involves the lack of liquidity in the first decade of the policy. In many USAA whole life structures, the cash value may not equal the total premiums paid (the "break-even point") for 12 to 15 years. For military families who may face sudden financial shifts or deployments, realizing that thousands of dollars in premiums have resulted in only a few hundred dollars of accessible cash can be a significant source of stress.
2. High Interest Rates on Policy Loans
Policyholders are often told they can "borrow from themselves" using the cash value as collateral. While true, USAA charges interest on these loans. As of 2026, these rates are often higher than what a member might find with a secured bank loan or a Home Equity Line of Credit (HELOC). Complaints arise when the interest on the loan accrues faster than the growth of the remaining cash value, potentially leading to a "policy lapse" if the loan balance exceeds the total cash value.
3. Surrender Charges and Net Cash Value
If a policyholder decides to cancel (surrender) their policy to access the cash, they do not always receive the full "account value." USAA, like most insurers, may apply surrender charges in the early years of the contract. The "Net Cash Surrender Value" is the amount remaining after these charges and any outstanding loans are deducted. The discrepancy between the "Total Cash Value" and the "Net Surrender Value" is a frequent catalyst for formal complaints to the National Association of Insurance Commissioners (NAIC).
4. Dividend Scale Reductions
USAA Life Insurance Company operates as a subsidiary of the broader USAA entity. While USAA is a reciprocal exchange, the life company is a stock company that acts in a "mutual-like" fashion regarding dividends. When the dividend scale is lowered—meaning the company distributes less profit to policyholders—the cash value growth slows down. Many members feel that the "membership" aspect of USAA should protect them from these market-driven fluctuations, leading to a sense of betrayal when growth targets are missed.
Comparative Analysis of Cash Value Access Methods
When a member needs to access the funds in their USAA whole life policy, they have several options, each with different impacts on the policy's long-term health. The following table compares these methods based on common complaint themes and financial outcomes.
| Access Method | Impact on Death Benefit | Interest/Fees | Tax Implications | Common Complaint |
|---|---|---|---|---|
| Policy Loan | Reduces benefit by loan amount + interest | 5%–8% (Estimated 2026) | Usually Tax-Free | Interest "eats" the remaining equity |
| Partial Surrender | Reduces death benefit proportionally | No interest; possible fees | Taxable above "basis" | Permanently reduces coverage |
| Full Surrender | Eliminates coverage | Surrender charges apply | Taxable on gains | Significant loss of paid-in premiums |
| Dividend Withdrawal | No impact (usually) | None | Generally Tax-Free | Dividends were lower than expected |
How to Investigate a USAA Cash Value Discrepancy
If you believe your USAA whole life cash value is lower than it should be, or if you are facing hurdles in accessing your funds, follow these technical steps to verify the status of your policy.
Step 1: Request an "In-Force Illustration"
Do not rely on the original sales brochure from five or ten years ago. Contact USAA and request a current In-Force Illustration. This document provides a projection based on the current dividend scale and your actual account balance. It will show you exactly when the policy is expected to break even and how much cash will be available at specific ages (e.g., age 65 or 70).
Step 2: Calculate Your "Basis"
The "basis" is the total amount of premiums you have paid into the policy. If you withdraw more than your basis, the excess is treated as ordinary income by the IRS and taxed accordingly. Many complaints about USAA cash values are actually complaints about the tax bill that arrives after a withdrawal. Understanding your basis helps you avoid "phantom income" surprises.
Step 3: Review the Non-Forfeiture Options
If the premiums have become unaffordable but you want to keep the cash value, look at the "Reduced Paid-Up" option. This allows you to stop paying premiums and keep a smaller death benefit, while the current cash value stays intact and continues to grow (though more slowly). This is often a better alternative to a full surrender, which many members regret later.
Addressing Complaints: The Resolution Process
When informal inquiries with USAA customer service do not resolve the issue, policyholders have specific avenues for escalation.
Internal Escalation
USAA has a dedicated "Office of the CEO" or a member advocacy group designed to handle complex disputes. When filing a complaint, use specific terminology: "misrepresentation of dividend projections," "failure to disclose surrender charges," or "usurious loan interest calculations." Using technical language often ensures the complaint is routed to a senior underwriter rather than a general customer service representative.
External Regulatory Filing
If internal resolution fails, the next step is filing a grievance with your State Insurance Department. Insurance is regulated at the state level, not the federal level. The NAIC provides a map to help you find your state's regulator. These bodies investigate whether USAA followed the contractual language approved by the state and whether the sales tactics used were compliant with state law.
The Role of AM Best and Financial Ratings
Complaints about growth should also be contextualized by the insurer's stability. As of 2026, USAA continues to maintain high ratings from AM Best and S&P. While these ratings don't help with slow cash growth, they do ensure that the company is solvent and able to pay out the guaranteed portions of your policy.
Common Mistakes to Avoid
To prevent the need for a formal complaint, policyholders should avoid these frequent pitfalls:
- Treating the policy like a bank account: Frequent loans and repayments can create a complex web of interest that is difficult to untangle.
- Ignoring the annual statement: USAA sends an annual report detailing the current cash value. Reviewing this every year prevents "sticker shock" after a decade of neglect.
- Underestimating the MEC limit: If you "overfund" a policy too quickly, it can become a Modified Endowment Contract (MEC), losing its tax-advantaged status. This often triggers complaints when the policyholder realizes they can no longer withdraw funds tax-free.
FAQ: Understanding USAA Whole Life Issues
Why is my USAA cash value $0 after two years of payments?
Most whole life policies, including those from USAA, use the first two to three years of premiums to cover the "acquisition costs" of the policy. This includes the medical underwriting fees, administrative setup, and the agent's commission. It is standard in the industry for cash value to begin accumulating significantly only in the third or fourth year.
Can USAA change my interest rate on a policy loan?
It depends on the specific contract. Most USAA policies issued in recent years have a "variable" loan interest rate tied to a specific index (like the Moody’s Corporate Bond Yield). If market rates rise, your policy loan rate will likely rise as well. This is a common source of complaints during inflationary periods.
How do I stop the cash value from being used to pay my premiums?
Many USAA policies have an "Automatic Premium Loan" (APL) provision. If you miss a payment, the company automatically takes a loan against your cash value to pay the premium. While this prevents the policy from lapsing, it can quickly deplete your equity. You can contact USAA to disable this feature, but be aware that if you miss a payment, your coverage may end.
Is the cash value separate from the death benefit?
No. In a standard whole life policy, the cash value is part of the death benefit, not in addition to it. If you have a $100,000 policy and $20,000 in cash value, your beneficiaries receive $100,000—not $120,000. Many complaints stem from this misunderstanding. If you want the cash value plus the death benefit, you must purchase a specific type of rider (Option B or Increasing Death Benefit), which increases the premium.
Does USAA offer a "buy-back" for surrendered policies?
Generally, once a policy is surrendered and the cash is paid out, the contract is terminated and cannot be "reinstated." If you are unhappy with the cash value, it is better to explore "Reduced Paid-Up" insurance or a "1035 Exchange" to a different financial product before signing the surrender forms.
Final Recommendations
If you find yourself dissatisfied with your USAA whole life insurance cash value in 2026, your first action should be an objective audit of the policy. Request an In-Force Illustration and compare it to your original goals. If the policy is still in its first five years, the slow growth is likely a normal (albeit frustrating) part of the product's lifecycle.
However, if you find that loan interest is compounding beyond your control or that the projected dividends have been slashed without explanation, consider consulting a fee-only financial advisor who does not sell insurance. They can provide an unbiased "stay or go" analysis. For those looking to exit, a 1035 Exchange may allow you to move your cash value into a more efficient vehicle, such as a low-cost annuity or a different life insurance product, without triggering an immediate tax event.
Image Gallery
Select an image to open it in a new tab.

Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
