Understanding Auto Insurance in 79107: A Comprehensive Guide for Amarillo Residents
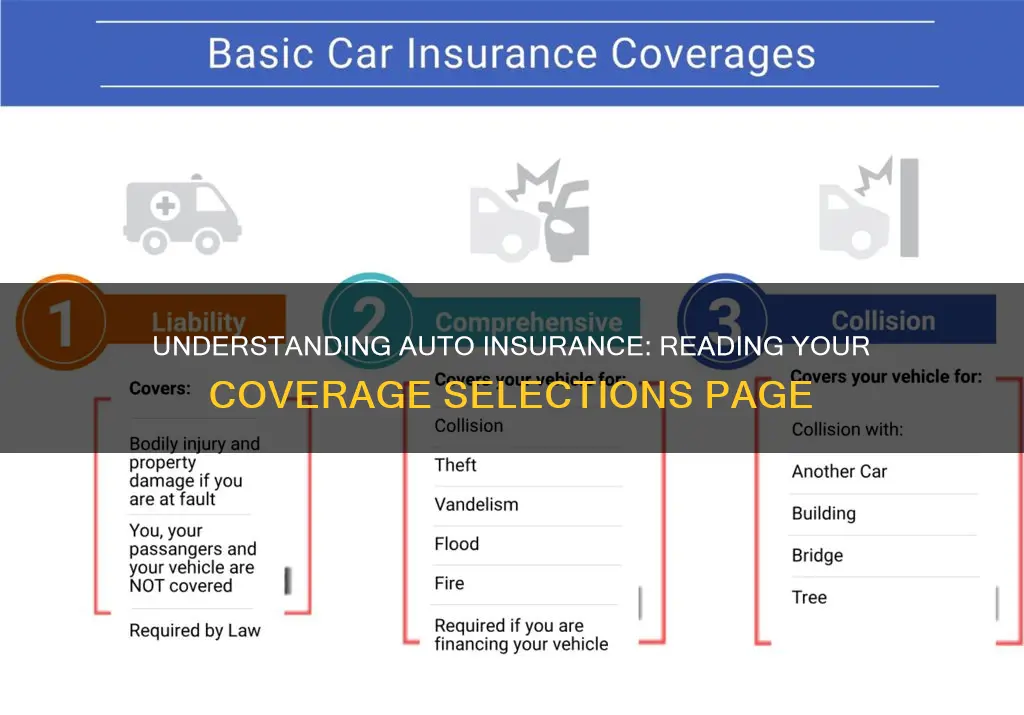
Navigating auto insurance in the 79107 ZIP code of Amarillo, Texas, requires balancing state-mandated liability requirements with the specific environmental and economic risks of the Texas Panhandle. Residents must secure at least 30/60/25 liability coverage while considering comprehensive protection against frequent hail, high wind speeds, and regional traffic patterns.
Automobile insurance is more than a legal checkbox for drivers in the 79107 area; it is a critical financial safeguard in a region defined by volatile weather and unique geographic challenges. Located in the northern portion of Amarillo within Potter County, the 79107 ZIP code encompasses a mix of residential neighborhoods, industrial zones, and major transit corridors like Interstate 40 and U.S. Route 287. These factors directly influence how insurance carriers calculate risk and set premiums for local motorists.
In 2026, the landscape of vehicle protection has evolved to account for rising repair costs and the increased technological complexity of modern cars. Whether you are a long-time resident of North Amarillo or a newcomer to the Panhandle, understanding the nuances of local coverage is essential for both legal compliance and long-term financial stability.
Disclaimer: This article provides general information regarding auto insurance and does not constitute professional legal or financial advice. Jurisdictional rules are subject to change, and residents should consult with a licensed insurance agent or the Texas Department of Insurance for specific policy guidance.
Texas State Requirements and Local Compliance
Texas operates under a "fault" system, meaning the driver responsible for an accident is liable for the resulting damages. To operate a vehicle legally in 79107, you must meet the state’s minimum financial responsibility limits, often referred to as the 30/60/25 rule.
Minimum Liability Limits in 2026
The Texas Department of Insurance (TDI) mandates the following minimums:
- $30,000 Bodily Injury Liability per person: This covers medical expenses for a single person injured in an accident where you are at fault.
- $60,000 Bodily Injury Liability per accident: This is the total cap the insurance company will pay for all injuries sustained by multiple people in a single accident.
- $25,000 Property Damage Liability: This covers repairs to the other party’s vehicle or property (such as fences or structures).
While these are the legal minimums, they are frequently insufficient in 2026. Given that the average cost of a new vehicle in the United States has climbed significantly, a $25,000 property damage limit may not even cover the total loss of a mid-range sedan, let alone a modern pickup truck common in the Amarillo area. If damages exceed your policy limits, the injured party can pursue your personal assets, including savings and property, to cover the difference.
Proof of Financial Responsibility
Texas law requires drivers to carry evidence of insurance at all times. In 79107, law enforcement officers from the Amarillo Police Department or the Potter County Sheriff’s Office will request this during traffic stops or at the scene of an accident. Texas uses an electronic verification system known as TexasSure, which allows officers to verify insurance status in real-time by matching vehicle registration with policy databases maintained by the state.
Why 79107 Residents Need More Than the Minimum
The 79107 ZIP code presents specific environmental and situational risks that make "liability-only" insurance a high-stakes gamble. Understanding these regional factors is key to selecting the right coverage depth.
The Impact of Panhandle Weather
Amarillo is situated in a high-risk zone for extreme weather. For residents in 79107, hail is perhaps the most frequent cause of non-collision insurance claims. High-plains thunderstorms often produce significant hailstones that can shatter windshields and dent body panels in seconds. Without Comprehensive Coverage, the cost of these repairs falls entirely on the vehicle owner.
Furthermore, the region experiences intense wind events and occasional tornadoes. Airborne debris and falling branches are common during the spring and fall seasons. Comprehensive insurance protects against these "acts of God," ensuring that your investment is protected even when your car is parked in your driveway.
Traffic and Transit Corridors
ZIP code 79107 is bisected by several major thoroughfares. The high volume of commercial trucking and interstate travel increases the statistical likelihood of multi-vehicle accidents. Higher speeds on highways like I-40 mean that collisions are often more severe than those occurring on residential side streets. This environment necessitates higher liability limits and Collision Coverage to ensure you can repair or replace your vehicle regardless of who is at fault.
Uninsured and Underinsured Motorist Risks
Despite state mandates, a significant percentage of drivers in Texas remain uninsured or carry only the bare minimum. In a fault-based state like Texas, if you are hit by a driver without insurance, you may be left with no way to recover costs for medical bills or vehicle repairs. Uninsured/Underinsured Motorist (UM/UIM) coverage is highly recommended for 79107 residents. It steps in to pay for your losses when the at-fault driver cannot, providing a vital safety net in a crowded transit hub like Amarillo.
Exploring Coverage Types for the Amarillo Driver
To build a robust policy, it is important to distinguish between the various components available in the 2026 insurance market.
Collision vs. Comprehensive Coverage
These two types of coverage are often bundled together as "Full Coverage," though they serve very different purposes:
- Collision Coverage: This pays for damage to your vehicle resulting from an upset (flipping) or a collision with another vehicle or object (like a light pole or tree). This is essential for newer vehicles or those with an active lien.
- Comprehensive Coverage: This covers damage from almost everything else—theft, fire, vandalism, hail, flood, and hitting an animal. In 79107, where deer and extreme weather are prevalent, this is often considered non-negotiable by local experts.
Personal Injury Protection (PIP) and Medical Payments
Texas law requires insurance companies to offer you at least $2,500 in Personal Injury Protection (PIP). While you can opt-out in writing, PIP is highly beneficial because it covers medical expenses, 80% of lost wages, and the cost of a caregiver, regardless of who caused the accident. Alternatively, Medical Payments (MedPay) coverage is available; it covers medical bills and funeral costs but does not cover lost wages.
Gap Insurance
If you are financing or leasing a vehicle in Amarillo, you may owe more on the loan than the car is actually worth (due to depreciation). If the vehicle is totaled in 79107, a standard policy only pays the Actual Cash Value (ACV). Gap insurance covers the "gap" between the ACV and the remaining balance on your loan, preventing you from paying for a car you can no longer drive.
Comparing Auto Insurance Options in 79107
When selecting a provider, residents should compare not just the monthly premium, but the claims reputation and local presence of the carrier.
| Coverage Type | What it Covers | Required in TX? | Recommended for 79107? |
|---|---|---|---|
| Liability | Others' injuries and property | Yes | Yes (Higher than minimum) |
| Collision | Your car damage (accidents) | No | Yes (For vehicles <10 years old) |
| Comprehensive | Weather, theft, animals | No | Highly Recommended (Hail risk) |
| UM/UIM | Hit-and-run, uninsured drivers | No | Yes (High regional risk) |
| PIP | Your medical bills/lost wages | Optional | Yes (No-fault protection) |
Factors Influencing Insurance Rates in North Amarillo
Several variables determine what a resident of 79107 will pay for their policy in 2026. Insurance companies use actuarial data to assess the likelihood of a claim.
- Geographic Risk: Within Amarillo, 79107 may have different rates than 79109 or 79119 based on local crime statistics (theft and vandalism) and the density of accidents in specific neighborhoods.
- Driving Record: A clean driving history remains the most effective way to keep rates low. Speeding tickets on Loop 335 or at-fault accidents on Amarillo Blvd will lead to surcharges that can last for three to five years.
- Credit-Based Insurance Scores: Texas allows insurers to use credit history as a factor in determining premiums. Maintaining a healthy credit score in 2026 correlates with lower insurance costs, as data suggests a link between financial responsibility and driving safety.
- Vehicle Usage: If you commute from 79107 to major employers like the Pantex Plant, Tyson Foods, or the medical district, your annual mileage will impact your rate. Higher mileage equals higher exposure to risk.
How to Save on Premiums Without Sacrificing Protection
While insurance is a necessary expense, there are several strategies for 79107 residents to reduce their financial burden in 2026.
Bundling Policies
Most major carriers offering services in Potter County provide significant discounts if you "bundle" your auto insurance with a homeowners or renters policy. This can often lead to savings of 10% to 25% across all policies.
Increasing Deductibles
The deductible is the amount you pay out-of-pocket before your insurance kicks in. By raising your deductible from $500 to $1,000, you can lower your monthly premium. However, in a hail-prone area like 79107, ensure you have enough savings set aside to cover that higher deductible if a storm hits.
Defensive Driving Courses
Completing a Texas-approved defensive driving course can not only dismiss a ticket but also provide a mandatory discount on the liability portion of your insurance for up to three years. Many of these courses are available online and are tailored to Texas-specific traffic laws.
Telematics and Usage-Based Insurance
In 2026, many Amarillo drivers are opting for telematics programs. These involve a smartphone app or a plug-in device that monitors braking, acceleration, and speed. Safe drivers in the 79107 area can see substantial discounts based on their actual driving behavior rather than general demographic data.
Navigating the Claims Process in Amarillo
If you are involved in an accident in 79107, the steps you take immediately afterward are crucial for your insurance claim.
- Safety First: Move to a safe location if possible and check for injuries. Call 911 if there is significant damage or medical need.
- Document the Scene: Use your smartphone to take photos of all vehicles involved, the surrounding intersection, and any relevant road signs or weather conditions.
- Exchange Information: Get the name, contact info, and insurance policy details of the other driver. Do not admit fault at the scene, as the legal determination of liability is handled by adjusters and investigators.
- File a Report: In Texas, if an accident results in injury or more than $1,000 in property damage and a police officer does not investigate, you must file a "Crash Report" (form CR-2) with the Texas Department of Transportation.
- Contact Your Agent: Report the claim as soon as possible. Local agents in Amarillo can often provide faster assistance and recommendations for reputable local repair shops that understand how to handle Panhandle-specific damage like hail pitting.
Frequently Asked Questions
Is 30/60/25 liability enough for an Amarillo driver?
While it meets the legal minimum, 30/60/25 is often insufficient in 2026. Rising medical costs and higher vehicle values mean that a moderate accident can quickly exceed these limits, leaving you personally liable for the remaining costs. Most experts recommend at least 100/300/50 coverage for adequate protection.
Does my insurance cover damage from a Panhandle hail storm?
Only if you have Comprehensive Coverage. Liability-only policies do not cover weather-related damage. Because hail is a frequent occurrence in the 79107 ZIP code, adding comprehensive coverage is a vital step in protecting your vehicle's value.
Can I use my own mechanic for repairs in 79107?
Yes. Under Texas law, your insurance company cannot require you to use a specific repair shop. However, they may only pay for the "reasonable and customary" cost of repairs. Using a local Amarillo shop with experience in the regional market is often beneficial for ensuring the work meets local standards.
How does a lapse in insurance affect my rates in Texas?
A lapse in coverage, even for a few days, can lead to significantly higher premiums when you re-apply. In 2026, insurers view a lapse as a high-risk indicator. Furthermore, driving without insurance in Potter County can result in fines, vehicle impoundment, and the requirement of an SR-22 certificate, which is a high-risk insurance filing.
Does auto insurance cover my belongings inside the car?
Generally, no. Auto insurance covers the vehicle and its attached parts. Personal items like laptops, tools, or luggage stolen from your car in 79107 are typically covered by your homeowners or renters insurance policy, not your auto policy.
Final Recommendations for 79107 Motorists
Securing the right auto insurance in 79107 requires a proactive approach. Start by assessing your vehicle's current value and your own financial risk tolerance. For residents of North Amarillo, the goal should be a policy that balances the Texas legal requirements with the very real threat of Panhandle weather and the high-traffic realities of the Potter County corridor.
Review your policy annually to ensure your coverage limits haven't been outpaced by inflation or changes in your driving habits. By combining a robust comprehensive plan with uninsured motorist protection, you can drive through the 79107 area with the confidence that both your vehicle and your financial future are secure. For more information on your rights as a policyholder, visit the Texas Department of Insurance.
Image Gallery
Select an image to open it in a new tab.
Declan O'Connor
Higher Education and Campus Culture Reporter
