Understanding Gap Insurance for Used Auto Loans: Protection, Costs, and Eligibility

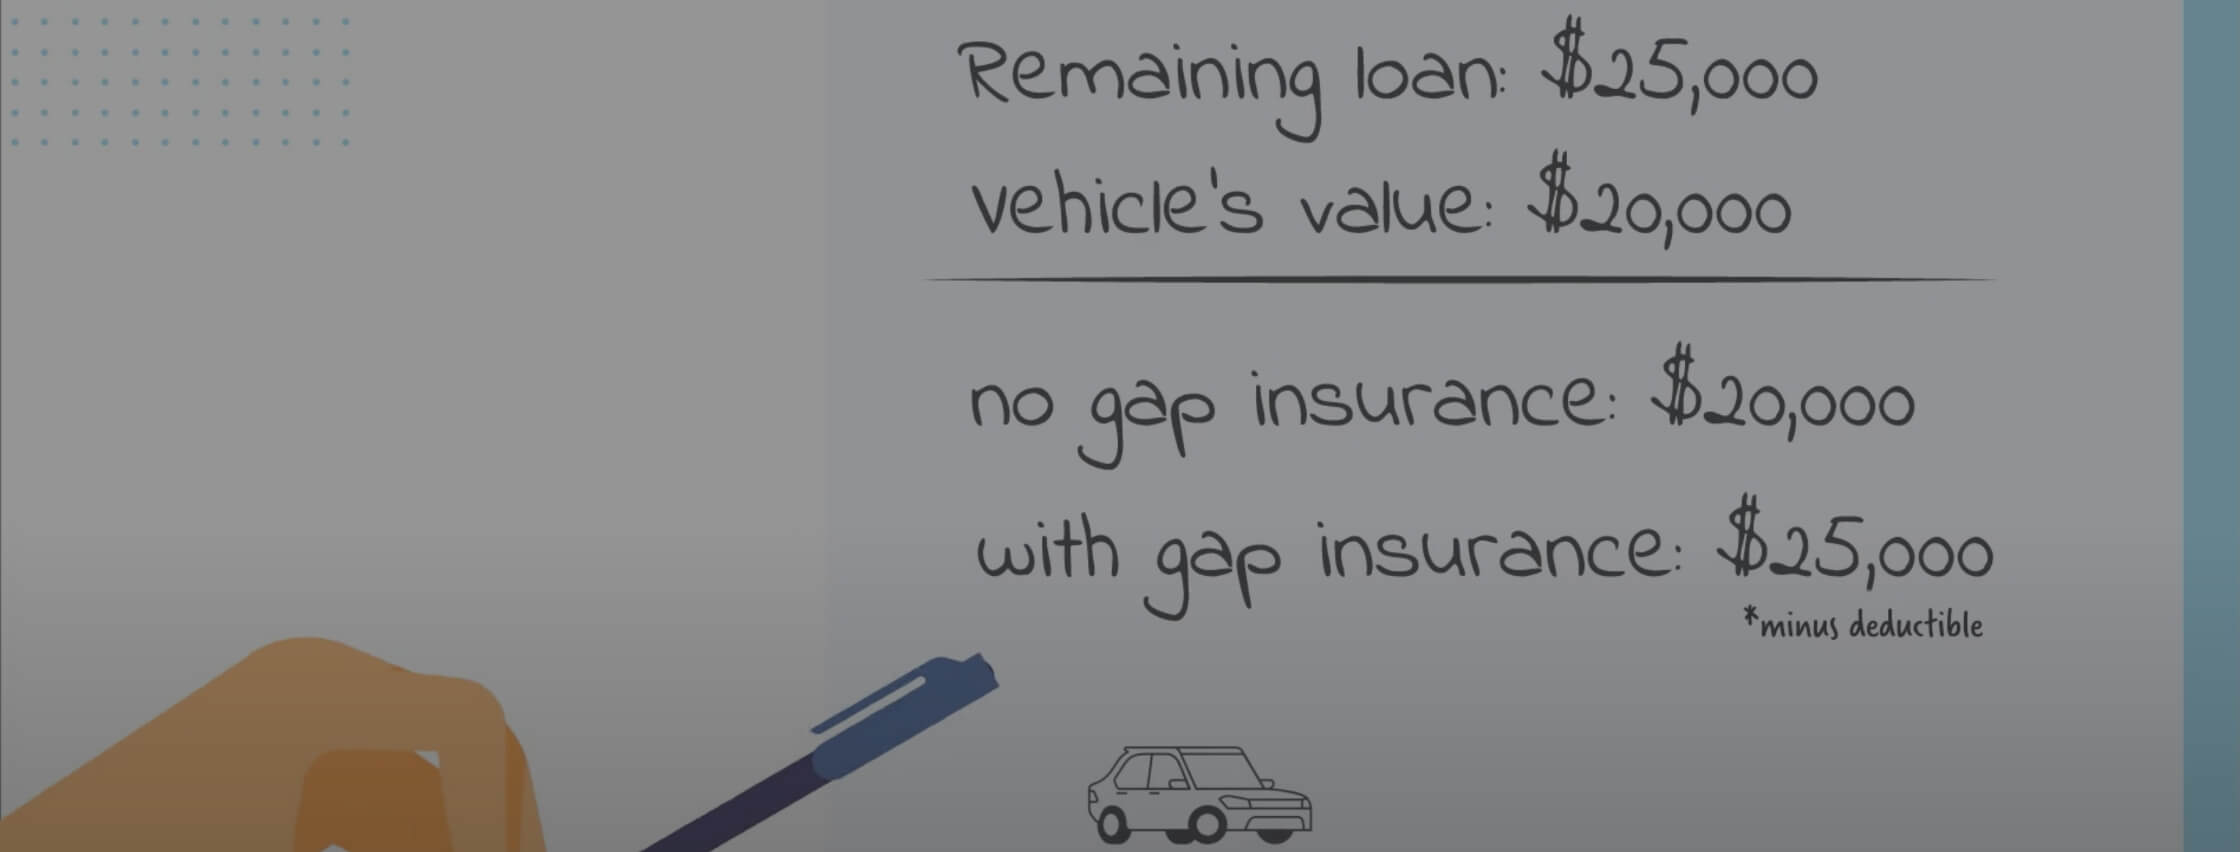
When you finance a pre-owned vehicle, gap insurance covers the difference between your auto loan balance and the actual cash value of the car if it is totaled or stolen. Because used vehicles depreciate rapidly, this optional coverage prevents you from paying out of pocket for a vehicle you no longer possess.
Introduction: Why Gap Insurance Matters for Pre-Owned Vehicles
Purchasing a pre-owned vehicle is often touted as a savvy financial move because much of the initial depreciation has already occurred. However, financing a used car still carries distinct financial risks that many drivers overlook until an emergency occurs. The core financial vulnerability lies in the gap between what your auto insurance company determines your car is worth at the time of a total loss and the remaining balance on your auto loan. This disparity is known as the "insurance gap," and without specific protection, you could find yourself paying hundreds or thousands of dollars for a vehicle that no longer exists in your driveway.
Gap insurance—technically known as Guaranteed Asset Protection—is designed to bridge this exact difference. While often heavily marketed to buyers purchasing brand-new cars, gap insurance for used auto loans is equally critical under specific financial conditions. If you made a modest down payment, rolled negative equity from a previous loan into your current financing agreement, or selected a long loan term exceeding 48 or 60 months, the rate of your loan amortization may lag far behind the vehicle's actual depreciation curve.
Navigating the mechanics of gap insurance requires an understanding of how auto valuation works, how lenders structure used car loans, and where to source this protection cost-effectively. Whether you are currently shopping for a pre-owned sedan or reviewing your existing loan documents, evaluating your exposure to the insurance gap can protect your financial stability against unexpected total losses.
How Depreciation and Used Car Loans Create the "Gap"
To understand why gap insurance is relevant for used vehicles, you must examine the relationship between standard auto insurance payouts and auto loan amortization schedules. Standard comprehensive and collision insurance policies are governed by a principle called "Actual Cash Value" (ACV). ACV represents the market value of your vehicle immediately before an accident or theft, taking into account mileage, overall condition, wear and tear, and localized market demand. Crucially, ACV does not factor in what you paid for the car or how much you currently owe on your financing agreement.
When you finance a used vehicle, your loan balance starts at the total purchase price (plus taxes, registration, and dealer fees if financed). During the first several months or years of the loan, a significant portion of your monthly payment goes toward interest rather than the principal balance. Meanwhile, the vehicle continues to lose market value.
Consider a common scenario in the used auto market:
- You purchase a three-year-old crossover for $20,000 with a $2,000 down payment, financing $18,000 over 60 months.
- Eighteen months later, the vehicle is involved in a severe collision and declared a total loss by your auto insurance provider.
- Due to mileage accumulation and shifts in market pricing, the insurance company determines the vehicle's current Actual Cash Value is $13,500.
- After deducting your comprehensive or collision deductible (e.g., $500), your insurance payout is $13,000.
- At that same point in time, your remaining loan payoff amount is $15,500.
The result is a $2,500 shortfall—the gap. Without gap insurance, your auto loan lender requires you to pay that $2,500 difference out of pocket immediately to close the account, even though your car was totaled through no fault of your own.

Eligibility and Requirements for Gap Insurance on Used Cars
Not every used car loan qualifies for gap insurance, and not every driver needs it. Lenders, credit unions, and insurance carriers enforce specific underwriting criteria before issuing a gap waiver or policy. Understanding these parameters ensures you do not waste money on coverage you cannot use or, conversely, assume you are protected when you are not.
Loan-to-Value (LTV) Ratio Thresholds
The primary metric providers use to evaluate risk is the Loan-to-Value ratio. Most traditional gap insurance providers require your initial financing amount to represent a high percentage of the vehicle's MSRP or blue-book retail value—frequently 80% to 125% or higher. Because used vehicles have fluctuating valuations, providers rely on recognized valuation guides, such as J.D. Power (formerly NADA) or Kelley Blue Book, to establish the baseline ACV at the time of purchase.
Vehicle Age and Mileage Limits
Unlike brand-new cars that roll straight off the showroom floor, used vehicles carry variable histories. Insurance companies and standalone gap providers often enforce strict caps on vehicle age and odometer readings. It is common for policies to stipulate that the vehicle must be less than five to seven years old and have fewer than 60,000 to 100,000 miles. If you are financing an older, high-mileage vehicle, finding an insurance carrier willing to write a gap policy can be challenging.
Financing Structure and Down Payments
Your upfront financial contribution directly dictates your eligibility and need. If you put down 35% in cash on a used car purchase, your initial loan balance is so far below the vehicle's actual cash value that an insurance gap is mathematically impossible. Conversely, if you utilized zero-down financing, traded in a vehicle with negative equity (rolling an old loan balance into the new used car loan), or financed taxes and dealer fees, your LTV ratio spikes, satisfying the risk profile required for gap coverage.
| Financing Factor | Low Risk (Gap Coverage Unlikely Needed) | High Risk (Gap Coverage Highly Recommended) |
|---|---|---|
| Down Payment | 20% or more of purchase price | Less than 10% or zero down |
| Loan Term | 36 months or fewer | 60,000 miles or fewer |
| Vehicle Age / Mileage | Brand new or strictly under 2 years old | Older than 3 years or high mileage |
| Negative Equity | None; clean trade-in value | Previous loan balance rolled into current loan |
Sources of Gap Insurance: Dealerships vs. Insurance Companies vs. Credit Unions
When you decide to secure gap insurance for a used auto loan, you have three primary avenues for purchase. Each option features distinct pricing structures, contract terms, and cancellation rules. Selecting the right source can save you hundreds of dollars over the life of your loan.
1. Auto Insurance Providers (Endorsement or Rider)
Adding gap insurance as an endorsement to your existing auto insurance policy is frequently the most cost-effective method. Major auto insurers offer this coverage (sometimes branded as "loan/lease gap coverage") for a nominal addition to your semi-annual premium, typically ranging from $20 to $60 per year.
- Pros: Highly affordable; can be canceled easily the moment your loan balance drops below the car's value; billed incrementally with your standard insurance.
- Cons: Requires you to maintain comprehensive and collision coverage on the vehicle; some insurers will not add gap insurance to an existing policy if the vehicle has been owned for more than 30 or 60 days.
2. Credit Unions and Banks
If you financed your used car through a credit union or community bank, inquire about their gap waiver programs. Many credit unions offer flat-fee gap protection that is significantly cheaper than dealership rates.
- Pros: Flat-rate pricing (often between $200 and $400); can be rolled into the monthly loan payment without steep dealer markups.
- Cons: Must typically be purchased at the exact time the loan is originated; unavailable if financed through an outside institution.
3. Dealership Financing and F&I Offices
Purchasing gap insurance through the dealership's Finance and Insurance (F&I) manager is the most common method, but it is also the most expensive. Dealerships often sell gap insurance as a flat product costing between $500 and $1,000, and they may roll this cost into your principal loan balance, causing you to pay interest on the insurance coverage itself.
- Pros: Convenient; available instantly during the vehicle purchase process regardless of your primary auto insurer.
- Cons: Significant markup; financing the cost increases total interest paid; cancellation and refunds can involve cumbersome administrative paperwork.
Cost Considerations and Financial Trade-Offs
Evaluating the financial viability of gap insurance requires weighing the upfront cost against the potential catastrophic loss of paying off a deflated loan balance. Because used vehicles depreciate at varying rates depending on make, model, and economic conditions, the financial exposure changes over time.
When calculating costs, pay close attention to how the fee is assessed. If a dealership quotes you $800 for gap insurance and rolls it into a 72-month loan at 7% interest, you are not just paying $800; you are paying cumulative interest on that product over six years, driving the true cost higher. Conversely, paying $30 a year through your auto insurance policy allows you to drop the coverage as soon as your loan amortization surpasses the vehicle depreciation curve.
Furthermore, review the payout caps of the policy. Many gap insurance contracts include a limitation clause, stating they will only cover a specific percentage of the vehicle's Actual Cash Value (for example, paying out up to 125% or 150% of the ACV). If your loan balance exceeds that threshold due to extreme negative equity roll-over, the gap insurance policy may not cover the entirety of the shortfall. Always read the fine print regarding maximum payout caps and exclusions, such as overdue loan payments or late fees, which are never covered by gap waivers.
Step-by-Step Guide: Evaluating Your Need and Purchasing Coverage
Determining whether you need gap insurance for a used auto loan and securing the right policy requires a methodical approach. Follow these practical steps to protect your finances without overpaying.
- Calculate Your Current Loan Payoff: Contact your lender or check your online loan portal to find the exact payoff amount as of today. Remember that this figure differs slightly from your current principal balance due to daily interest accrual.
- Determine Your Vehicle's Actual Cash Value: Visit independent vehicle valuation platforms like Kelley Blue Book or Edmunds. Input your exact trim level, mileage, condition, and ZIP code to find the realistic trade-in or private-party market value.
- Compare Values: Subtract your estimated vehicle ACV from your loan payoff amount. If your loan payoff is higher than the vehicle's value, you have a positive gap and financial exposure.
- Check Existing Coverage: Review your current auto insurance declarations page or call your insurance agent to ask if loan/lease gap coverage is already included in your policy or can be added.
- Shop Around for Quotes: If your auto insurer does not offer gap coverage or charges too much, contact your credit union or bank to compare standalone policy rates. Avoid accepting the first dealer quote without comparing alternative options.
- Verify Policy Terms and Cancellation Rules: Ensure the policy covers 100% of the difference plus your insurance deductible (if applicable). Confirm how cancellation works so you can drop the coverage once your loan balance naturally falls below the car's value.
Common Mistakes to Avoid When Buying Gap Insurance
Navigating financial products during a vehicle purchase can lead to costly oversold extras. Keep the following pitfalls in mind to protect your budget:
- Assuming Comprehensive Insurance Covers the Gap: Many drivers believe that having "full coverage" (comprehensive and collision) means the insurance company pays off the loan in full. In reality, standard insurance only pays market value, leaving any loan balance shortfall entirely your responsibility.
- Failing to Cancel the Policy Early: Gap insurance is only necessary while your loan balance exceeds your car's value. If you keep paying for gap insurance during the final year of a loan when the car is worth less than the loan balance, you are wasting money on a benefit that will never trigger.
- Accepting Dealer Financing Without Review: Dealerships frequently bundle gap insurance into conditional financing quotes without itemizing the cost. Always ask for a breakdown of all added products and fees before signing loan documents.
- Overlooking Deductible Coverage Limits: Check whether your gap policy covers your primary auto insurance deductible. Some policies add up to $1,000 toward your deductible, providing an extra layer of financial relief during a claim.
Frequently Asked Questions
Can I buy gap insurance after I have already purchased my used car?
Yes, but your options are more limited. While you generally cannot purchase gap insurance from a dealership days or months after driving off the lot, many traditional auto insurance providers allow you to add a gap endorsement within 30 to 60 days of purchasing or financing the vehicle.
Does gap insurance cover missed loan payments or late fees?
No. Gap insurance strictly covers the difference between the actual cash value of the vehicle and the remaining principal loan balance after a total loss. It does not cover past-due payments, late fees, extended warranty costs rolled into the loan, or skipped payments.
How do I cancel gap insurance once I no longer need it?
If you purchased gap insurance through your auto insurance carrier, you can call your agent and remove the endorsement at any time. If you purchased a flat-fee gap waiver through a credit union or dealership, you must submit a written cancellation request. Depending on the contract terms, you may be eligible for a prorated refund for the unused portion of the policy.
Is gap insurance required by lenders on used car loans?
Most standard auto lenders do not legally require gap insurance to finance a used car, unlike comprehensive and collision insurance, which protect the lender's collateral. However, a lender may mandate gap insurance if you present an exceptionally high credit risk, such as extreme negative equity or a very high loan-to-value ratio.
What happens to gap insurance if my car is stolen rather than totaled?
Gap insurance applies identically to unrecovered stolen vehicles and vehicles declared total losses due to accidents, fires, or natural disasters. If your insurance company writes off the vehicle as a total loss due to theft, the gap policy covers the remaining loan balance shortfall.
Conclusion and Next Actions
Securing gap insurance for a used auto loan is a practical strategy to protect your personal finances against the rapid depreciation inherent in vehicle ownership. By evaluating your loan-to-value ratio, checking your current auto insurance policy for existing riders, and shopping around for competitive rates through credit unions or insurers, you can avoid costly dealer markups. Review your loan documents and vehicle valuation today to determine whether your financing agreement leaves you vulnerable to an unexpected insurance gap.
Image Gallery
Select an image to open it in a new tab.


Vivian Cho
Executive IT and Emerging Technologies Reporter
