A car down payment is an upfront cash payment or trade-in credit applied toward the total purchase price of a vehicle. It reduces the principal amount of the auto loan, directly lowering monthly payments and the total interest paid over the life of the loan. By providing immediate equity, a down payment also minimizes the lender’s risk and protects the buyer from "negative equity."
The Mechanics of an Auto Down Payment
To understand how down payments on cars work, one must first look at the relationship between the purchase price, the loan-to-value (LTV) ratio, and the financing terms. When you purchase a vehicle in 2026, the total cost includes the "sticker price" or negotiated price, plus taxes, title, registration, and dealer fees. Financing the entire amount—often called "zero-down financing"—means you are borrowing 100% or more of the car’s value.
A down payment acts as the first layer of equity in your asset. For example, if a car costs $40,000 and you provide a $8,000 down payment, you only need to finance $32,000. This $8,000 "sinker" reduces the lender's exposure. If you were to default on the loan immediately, the lender could sell the car and likely recoup the $32,000 more easily than if they had lent the full $40,000. Because of this reduced risk, lenders often reward larger down payments with lower interest rates (Annual Percentage Rates or APR).
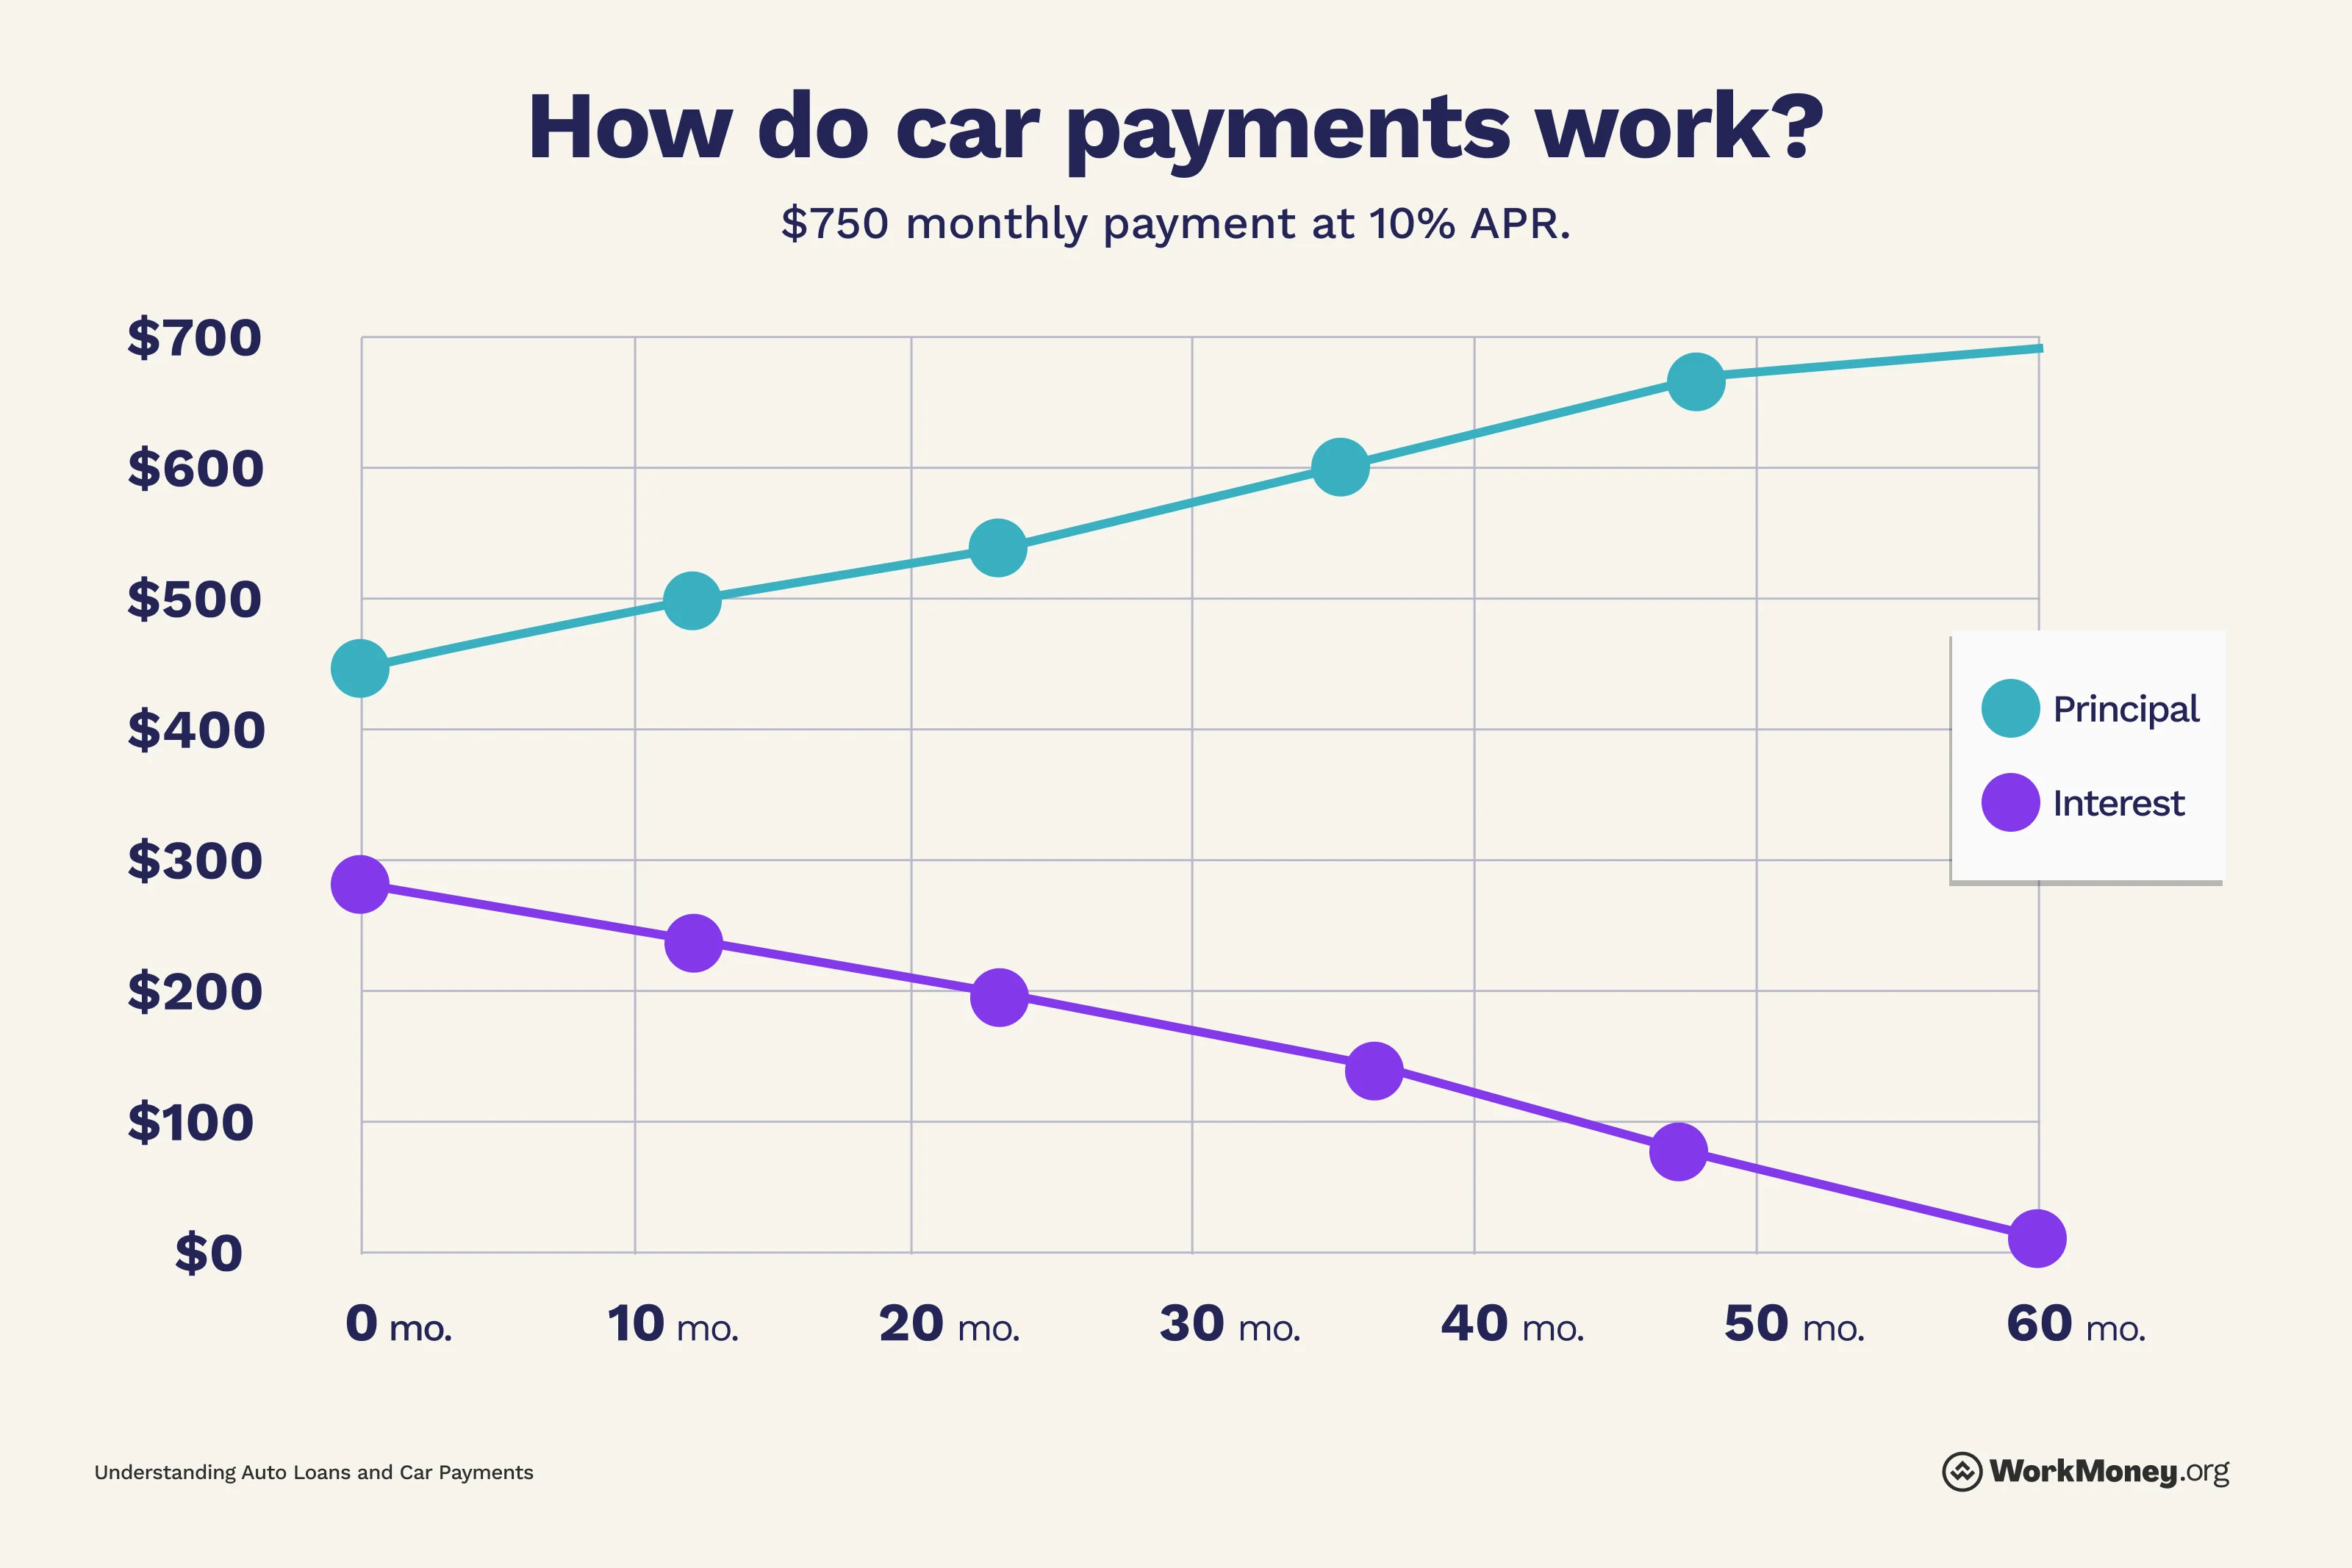
Furthermore, the down payment dictates the starting point of your amortization schedule. Amortization is the process of paying off debt over time through regular installments. Since interest is calculated based on the remaining principal balance each month, a smaller starting principal results in less interest accruing from day one. In a high-interest environment, such as the one seen in recent years leading into 2026, the compounding effect of a reduced principal can save a borrower thousands of dollars over a five- or six-year term.
How Much Should You Put Down in 2026?
While there is no legal requirement for a specific down payment amount, financial experts traditionally recommend the "20/4/10 rule." This suggests putting down at least 20% of the purchase price, financing for no more than four years, and ensuring total transportation costs do not exceed 10% of your monthly income.
New vs. Used Vehicle Considerations
The recommended down payment often fluctuates based on whether the vehicle is new or pre-owned. For a brand-new 2026 model, a 20% down payment is highly advised because of "drive-off depreciation." Most new cars lose 10% to 20% of their value within the first year of ownership—a significant portion of which occurs the moment the car leaves the dealership lot. Without a 20% down payment, you risk becoming "upside-down" or "underwater" on the loan, where you owe the bank more than the car is worth.
For used vehicles, a down payment of 10% to 15% is often considered acceptable. Used cars have already navigated the steepest part of their depreciation curve, meaning their value remains more stable relative to the loan balance. However, used car loan interest rates are typically higher than new car rates, so a larger down payment on a used vehicle can be an effective way to offset those higher borrowing costs.
Minimum Requirements by Lenders
In practice, many lenders will approve loans with as little as $500 to $1,000 down, or even $0 down for buyers with "tier-one" credit scores (usually above 740 or 760). However, subprime lenders—those who work with buyers with lower credit scores—may mandate a specific minimum, such as 10% or a flat $1,500, to mitigate the higher statistical risk of default.

Sources of a Down Payment
A down payment does not necessarily have to be entirely liquid cash from a savings account. In the 2026 automotive market, buyers frequently use a combination of three distinct sources to build their upfront equity.
1. Cash and Liquid Assets
This is the most straightforward method. Buyers can pay via certified check, electronic fund transfer (ACH), or sometimes a credit card (though dealers often cap credit card payments at $2,000–$5,000 due to processing fees). Using cash is the most effective way to lower the LTV ratio without relying on external valuations.
2. Trade-In Equity
If you already own a vehicle, its trade-in value acts as a down payment. If your current car is worth $15,000 and you owe $5,000 on its loan, you have $10,000 in "positive equity" to apply toward your next purchase. In many U.S. states and other jurisdictions, trading in a vehicle also provides a sales tax credit. You are often only taxed on the difference between the new car's price and your trade-in's value, which can save you hundreds additional dollars.
3. Manufacturer Rebates and Incentives
Automakers frequently offer "customer cash" or "loyalty rebates" to move inventory. In 2026, as electric vehicle (EV) competition remains fierce, these rebates can be substantial. A $3,000 manufacturer rebate functions exactly like a cash down payment from your own pocket; it reduces the amount you need to borrow from the bank.
The Impact on Loan Approval and Interest Rates
Lenders use a metric called the Loan-to-Value (LTV) ratio to determine your loan's risk level. The formula is: LTV = (Total Loan Amount / Vehicle’s Wholesale or Invoice Value) x 100
If you buy a car for $30,000 and put $6,000 down, your loan is $24,000. Your LTV is 80%. If you put $0 down and also roll in taxes and fees, your loan might be $33,000, resulting in an LTV of 110%.
When the LTV exceeds 100%, lenders view the loan as high-risk. To compensate, they charge a higher interest rate. Conversely, if your down payment brings the LTV down to 80% or 70%, you move into a lower risk tier, which can unlock the lowest advertised APRs. For buyers with marginal credit, a substantial down payment is often the "tipping point" that moves an application from a "denied" status to an "approved" status.
Comparison of Down Payment Scenarios (2026 Projections)
The following table illustrates how different down payment amounts affect the monthly cost and total interest for a mid-sized SUV priced at $45,000 with a 6.5% interest rate over a 60-month (5-year) term.
| Down Payment Amount | Loan Amount (Excl. Fees) | Monthly Payment | Total Interest Paid | Equity Status After 1 Year |
|---|---|---|---|---|
| $0 (0%) | $45,000 | $880 | $7,825 | Likely Underwater |
| $4,500 (10%) | $40,500 | $792 | $7,043 | Near Breakeven |
| $9,000 (20%) | $36,000 | $704 | $6,260 | Positive Equity |
| $13,500 (30%) | $31,500 | $616 | $5,478 | Significant Equity |
Note: Figures are rounded for clarity. Tax, title, and license fees are assumed to be paid upfront or excluded from the loan principal.
Managing Negative Equity in Trade-ins
A significant complication in how down payments work occurs when a buyer has "negative equity" on their current vehicle—commonly known as being "upside-down." This happens if you owe $20,000 on a car that is only worth $17,000.
If you trade in that vehicle, the dealer must "roll over" that $3,000 deficit into your new loan. In this scenario, even if you provide a $3,000 cash down payment, you are effectively putting zero dollars down on the new car because your cash is simply neutralizing the debt from your old car. To make a true 20% down payment in this situation, you would need to pay the $3,000 to clear the old debt plus 20% of the new car's price. Failing to account for negative equity is a primary reason why many buyers find themselves in a cycle of increasing debt with each vehicle purchase.
Benefits of a Substantial Down Payment
Beyond simply lowering the monthly bill, a large down payment provides several long-term financial protections:
- Avoidance of Gap Insurance: If a car is totaled or stolen, standard insurance only pays the current market value. If you owe more than that value (because you put little money down), you are responsible for the "gap." A 20% down payment usually ensures your loan balance is always lower than the car’s value, making expensive Gap Insurance unnecessary.
- Faster Path to Ownership: Because you start with a lower balance, you reach the point where the car is "paid off" or has significant trade-in value much sooner. This provides more flexibility if your financial situation changes and you need to sell the vehicle quickly.
- Lower Opportunity Cost of Debt: While some argue that cash should be invested in the stock market rather than a car, this only holds true if the investment return is significantly higher than the loan's interest rate. In 2026, where auto loan rates remain competitive but substantial, "guaranteeing" a 6-7% return by avoiding interest charges is a prudent move for many.
When a Low Down Payment Might Make Sense
Despite the benefits of putting more money down, there are specific circumstances in 2026 where a buyer might opt for a minimal down payment:
- Promotional 0% or 0.9% APR Financing: If a manufacturer is offering near-zero interest rates, there is little financial incentive to put cash down. In this case, you are better off keeping your cash in a high-yield savings account earning 4-5% while borrowing money at 0%.
- Urgent Transportation Need: If your current vehicle is non-functional and you lack significant savings, a small down payment allows you to secure a reliable vehicle to maintain your employment.
- Leasing: When leasing a car, a large down payment (often called "capitalized cost reduction") is generally discouraged. If the leased car is totaled in an accident, that down payment is often non-refundable, and the lease is simply terminated by the insurance company and the lessor.
Common Mistakes to Avoid
- Focusing Only on the Monthly Payment: Dealers may ask, "What monthly payment are you looking for?" They can often hit that number by extending the loan term (e.g., 84 months) rather than requiring a proper down payment. This results in much higher interest costs over time.
- Using Your Emergency Fund: You should never deplete your entire "rainy day" fund for a car down payment. If the car breaks down or you lose your income, you need that liquidity.
- Waiting Too Long to Save: With car prices in 2026 averaging higher than previous decades, saving for a 20% down payment requires planning. It is often better to buy a slightly less expensive car with a solid down payment than to stretch for a luxury model with $0 down.
Practical Steps: From Saving to Signing
- Check Your Credit: Six months before buying, review your credit report. Higher scores reduce the down payment "pressure" from lenders.
- Value Your Trade-In: Use independent tools like Kelley Blue Book or Edmunds to get a realistic wholesale value for your current car.
- Calculate the 20% Goal: Once you identify the model you want, calculate 20% of the MSRP plus an additional 10% for taxes and fees.
- Inquire About Rebates: Ask the dealer specifically about "stackable" incentives that can count toward your down payment.
- Verify the Final Disclosure: Before signing the purchase agreement, ensure the down payment is clearly listed as a "Credit" against the purchase price, and verify that the "Amount Financed" reflects the subtraction of that down payment.
Frequently Asked Questions
Can I use a credit card for a car down payment? Most dealerships allow credit cards for down payments, but they typically limit the amount to between $2,000 and $5,000. This is because dealers must pay processing fees (1.5% to 3%) on the transaction. While using a card can help you earn rewards points, you should only do so if you can pay off the credit card balance immediately to avoid high-interest credit card debt.
What happens to my down payment if I return the car? In most cases, car sales are final. If your state has a "lemon law" and the vehicle is found to be defective, or if the dealer offers a specific return policy (e.g., 3-day money-back guarantee), you are entitled to a refund of your down payment. However, outside of these specific legal protections, you cannot simply return a car and get your down payment back because you changed your mind.
Does a down payment go to the dealer or the bank? The down payment goes to the dealer. It is subtracted from the total "out-the-door" price of the vehicle. The remaining balance is what the bank or finance company pays the dealer on your behalf. Therefore, the bank only "sees" and manages the loan for the remaining balance.
Is $2,000 a good down payment for a car in 2026? In the 2026 market, where the average new car price often exceeds $48,000, $2,000 is considered a small down payment (less than 5%). While it may be enough to secure a loan, it likely won't protect you from depreciation or significantly lower your interest rate. For a used car priced at $15,000, however, $2,000 is a much more substantial 13% down payment.
Can I get a car loan with no money down? Yes, "zero-down" loans are common for borrowers with good-to-excellent credit. However, these loans often come with higher interest rates and a higher risk of being "upside-down." Lenders may also require you to purchase Gap Insurance as a condition of a zero-down loan to ensure the debt is covered if the car is totaled.
Next Action: Calculate your current liquid savings and the estimated trade-in value of your existing vehicle. Compare this total to 20% of the MSRP of your target 2026 vehicle to determine your "down payment gap" and set a monthly savings goal to close it before visiting the dealership.
Image Gallery
Select an image to open it in a new tab.



Akira Tanaka
International Academic Trends Correspondent
