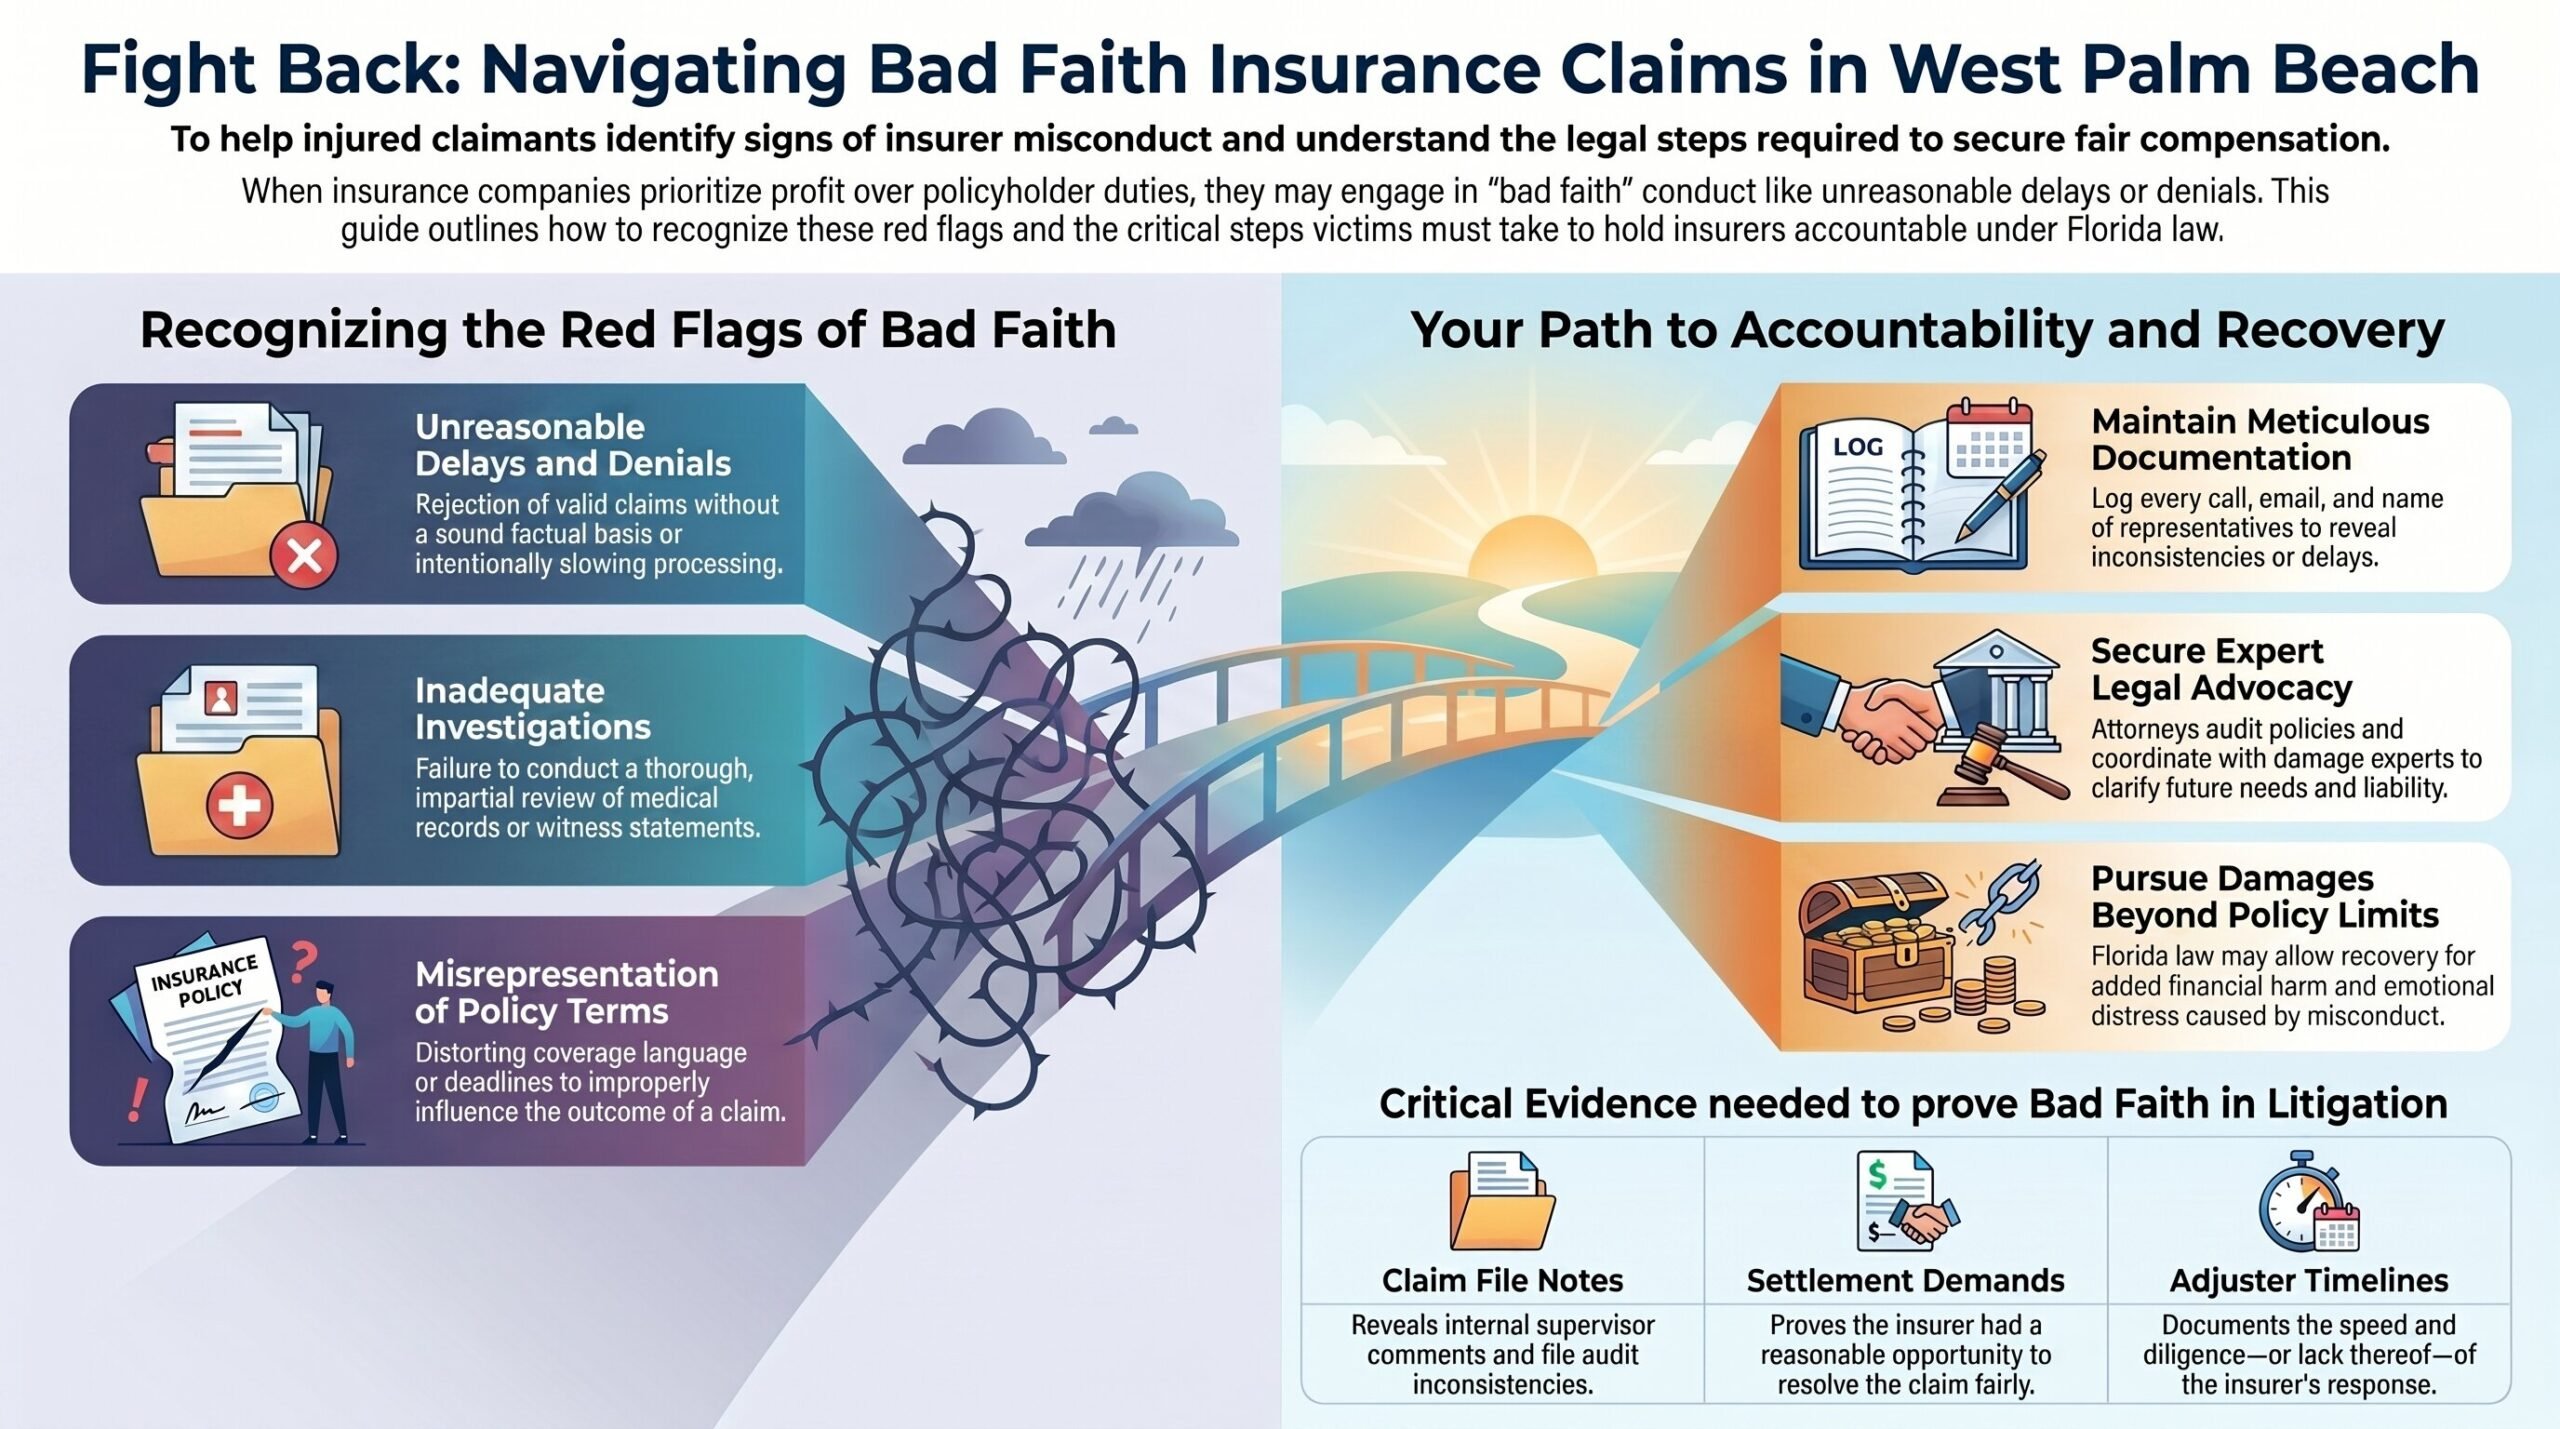
A bad faith claim in workers' compensation occurs when an insurance carrier unreasonably denies, delays, or terminates benefits without a valid basis. In 2026, pursuing a bad faith action allows injured workers to seek damages beyond standard medical and wage benefits—such as compensation for emotional distress or punitive damages—if the insurer’s conduct violated the legal duty of good faith and fair dealing.
The relationship between an injured worker and a workers' compensation insurance carrier is fundamentally governed by a "no-fault" contract. However, this contract carries an implied covenant of good faith. When an insurer prioritizes its bottom line over its legal obligations to a claimant, the "exclusive remedy" of the workers' compensation system may be bypassed in certain jurisdictions, opening the door to civil litigation. Understanding the distinction between a simple dispute and actionable bad faith is critical for any claimant seeking full redress for insurance misconduct.
Defining Bad Faith in the Workers' Compensation Context
Bad faith is more than a simple disagreement over the value of a claim or a clerical error. It is a specific legal tort that arises when an insurer acts with a lack of reasonable basis for its actions and possesses knowledge (or reckless disregard) of that lack of reasonable basis.
In the realm of workers' compensation, the insurer has a dual responsibility: to investigate the claim fairly and to provide benefits promptly once the claim's validity is established. As of 2026, courts increasingly look at the "totality of the circumstances" to determine if an insurer's behavior crossed the line from aggressive claims management to bad faith.
The Duty of Good Faith and Fair Dealing
Every insurance policy contains an implied covenant of good faith and fair dealing. This means the insurer cannot do anything that will injure the right of the insured (or the intended beneficiary, the injured worker) to receive the benefits of the agreement. In workers' compensation, while the employer pays the premium, the injured employee is the third-party beneficiary of that coverage. When an insurer fails to meet this duty, they are not just breaching a contract; they are committing a civil wrong.
Common Indicators of Bad Faith Conduct
Identifying bad faith requires a deep dive into the insurer’s claims-handling process. While every case is unique, several behaviors are frequently cited in successful 2026 bad faith litigations:
- Unreasonable Delays in Payment: If the insurer has all necessary medical documentation and employer verification but refuses to issue indemnity checks for months, this may constitute bad faith.
- Failure to Conduct a Proper Investigation: An insurer cannot simply deny a claim because it "looks suspicious." They have a duty to investigate facts that might support the claim, not just facts that would allow for a denial.
- Wrongful Denial of Medical Treatment: This occurs when a carrier ignores the recommendations of the primary treating physician or uses "peer review" doctors who have never examined the patient to block life-saving or necessary surgeries.
- Misrepresenting Policy Terms or Legal Rights: Providing false information to an unrepresented worker regarding their eligibility for certain benefits or the statute of limitations is a classic example of bad faith.
- Undue Pressure and Harassment: Using aggressive surveillance, threatening to stop benefits unless a low-ball settlement is accepted, or contacting the worker’s employer to disparage them are tactics often scrutinized in bad faith suits.
- Refusal to Settle: When liability is clear and the damages are undisputed, a refusal to offer a reasonable settlement can be interpreted as an attempt to "starve out" the claimant.
The Legal Threshold: Negligence vs. Bad Faith
It is essential to distinguish between negligence and bad faith. Negligence involves a mistake, such as an adjuster losing a file or miscalculating a weekly rate. While these errors are frustrating and may entitle a worker to statutory interest or penalties through the state workers' compensation board, they do not usually support a separate civil lawsuit for bad faith.
To prevail in a bad faith claim, the claimant generally must prove:
- The insurer lacked a reasonable basis for denying or delaying the benefits.
- The insurer knew there was no reasonable basis or acted with reckless disregard for whether a basis existed.
This often involves the "Fairly Debatable" standard. If an insurer can show that the claim's validity was "fairly debatable" based on conflicting medical evidence or legal interpretations, they are often shielded from bad faith liability, even if they are ultimately ordered to pay the underlying benefits.
The "Exclusive Remedy" Rule and Jurisdictional Variations
One of the most significant hurdles in bad faith workers' compensation cases is the Exclusive Remedy Rule. Historically, workers' compensation was designed as a "grand bargain": employees gave up the right to sue their employers for negligence in exchange for guaranteed, no-fault medical and wage benefits.
In many states, this exclusivity extends to the insurance carrier. However, the legal landscape in 2026 shows a clear divide in how states handle this:
- Strict Exclusivity States: In these jurisdictions, all disputes—including those involving insurer misconduct—must stay within the workers' compensation administrative system. The worker may receive a 10% to 50% penalty on late payments but cannot sue for emotional distress or punitive damages in civil court.
- Intentional Tort Exceptions: Many states allow a worker to bypass the administrative system if they can prove the insurer committed an "intentional tort" (e.g., intentional infliction of emotional distress or fraud) that is distinct from the original physical injury.
- Independent Tort States: Some states recognize bad faith as an independent cause of action that is not barred by the workers' compensation act, reasoning that the injury caused by the bad faith (financial ruin, mental anguish) is separate from the workplace injury itself.
Comparison of Recovery Options
The following table compares the typical outcomes of administrative penalties versus a successful bad faith civil lawsuit.
| Feature | Administrative Penalties (WorkComp Board) | Bad Faith Civil Lawsuit (Tort) |
|---|---|---|
| Primary Goal | Compliance and timely payment | Compensation for extra-contractual harm |
| Typical Recovery | 10% - 25% of the delayed benefit | Full compensatory + Punitive damages |
| Emotional Distress | Generally not recoverable | Often a primary component of damages |
| Legal Fees | Often capped by state statute | Contingency-based (may be higher) |
| Burden of Proof | Preponderance of evidence (lower) | Clear and convincing evidence (higher) |
| Duration | Months (Administrative track) | Years (Civil litigation track) |
Steps to Take if You Suspect Bad Faith
If you believe your workers' compensation carrier is acting in bad faith, you must transition from a passive claimant to an active evidence collector. In 2026, the digital trail of communication is often the strongest evidence in these cases.
1. Document Every Interaction
Keep a detailed log of every phone call, including the date, time, the name of the adjuster, and exactly what was said. If an adjuster promises that a check is in the mail and it doesn't arrive for two weeks, that discrepancy is a data point.
2. Move All Communication to Writing
Avoid verbal agreements. Use email or certified mail for all important requests. If the insurer denies a medical procedure, send a written request for the specific medical evidence they used to make that determination.
3. Review the "Explanation of Benefits" (EOB)
Analyze every denial letter. Does it cite a specific doctor’s report? Does it refer to a specific section of the state labor code? If the denial is vague or non-specific, it may be evidence of an inadequate investigation.
4. File a Formal Complaint with the State Regulator
Most states have a Department of Insurance or a Workers' Compensation Commission that oversees insurer conduct. While these agencies may not win you a million-dollar judgment, their investigation can provide "discovery" material that is invaluable if you later file a civil suit.
5. Consult a Specialized Bad Faith Attorney
Bad faith litigation is highly technical and distinct from standard workers' compensation law. You need an attorney who understands insurance bad faith statutes, the "discovery" process for obtaining internal claims manuals, and the nuances of overcoming the exclusive remedy defense.
Discovery: Uncovering the "Claim File"
The heart of any bad faith case is the insurer’s claim file. In a standard workers' compensation dispute, you only see what the insurer wants you to see. In a bad faith lawsuit, your attorney can subpoena the internal notes, emails, and reserve history of the adjuster.
Evidence often found in these files includes:
- Adjuster notes expressing bias against the claimant.
- Instructions from supervisors to "close the file at all costs."
- Evidence that the insurer ignored a doctor's report that supported the claimant.
- Incentive programs for adjusters who deny a certain percentage of claims.
Potential Damages in a Bad Faith Lawsuit
In 2026, the damages available in a bad faith claim are "extra-contractual," meaning they go above and beyond what the insurance policy originally promised.
- Compensatory Damages: This includes financial losses caused by the delay (e.g., interest on loans, loss of a home due to foreclosure, or damage to credit scores).
- Emotional Distress: Compensation for the anxiety, depression, and mental anguish caused by the insurer’s refusal to provide benefits during a vulnerable time.
- Attorney's Fees: In many jurisdictions, if you prove bad faith, the insurer is required to pay your legal fees.
- Punitive Damages: These are designed to punish the insurer and deter future misconduct. They are usually only awarded in cases of "malice, fraud, or oppression," where the insurer’s behavior was particularly egregious.
Frequently Asked Questions
Can I sue for bad faith if my claim was eventually paid?
Yes. The fact that the insurer eventually paid the benefits does not "cure" the bad faith if the delay was unreasonable and caused you harm. The damage occurs during the period of unreasonable denial or delay.
How do I know if my state allows bad faith lawsuits for workers' comp?
This is highly jurisdictional. States like Wisconsin and Arizona have recognized the right to sue for bad faith, while others like Florida and Georgia generally restrict claimants to administrative penalties. You should check the current 2026 statutes in your specific state or consult a local attorney.
What is the "Independent Medical Exam" (IME) role in bad faith?
Insurers often use IMEs to justify a denial. If an insurer repeatedly uses a doctor known for writing "pro-carrier" reports and ignores your treating physician's objective findings (like an MRI), this can be used as evidence that the "investigation" was a sham designed to support a pre-ordained denial.
Is a "disagreement" over disability percentage considered bad faith?
Rarely. If your doctor says you have a 20% permanent disability and the insurer's doctor says 10%, that is a standard medical dispute. Bad faith usually requires something more, such as the insurer refusing to pay even the undisputed 10% while the rest is being litigated.
Does an employer's behavior count as bad faith?
Generally, no. Bad faith is a tort committed by the insurance carrier. However, if the employer and insurer conspire to fabricate evidence to deny a claim, both may be liable for various legal claims, including fraud or conspiracy.
Summary and Next Actions
A bad faith claim in workers' compensation is a powerful tool for holding insurance companies accountable for misconduct. However, it is a high-stakes legal path that requires proving the insurer acted unreasonably and with knowledge of that unreasonableness.
If you suspect your carrier is intentionally obstructing your recovery, your immediate next action should be to secure a full copy of your medical records and all written correspondence from the insurer. Contact a legal professional who specializes in both workers' compensation and insurance tort law to evaluate whether your case meets the threshold for a bad faith filing in your specific jurisdiction.
Image Gallery
Select an image to open it in a new tab.


Vivian Cho
Executive IT and Emerging Technologies Reporter
