Comprehensive Guide to Auto Insurance DWI Coverage and High-Risk Policies in 2026

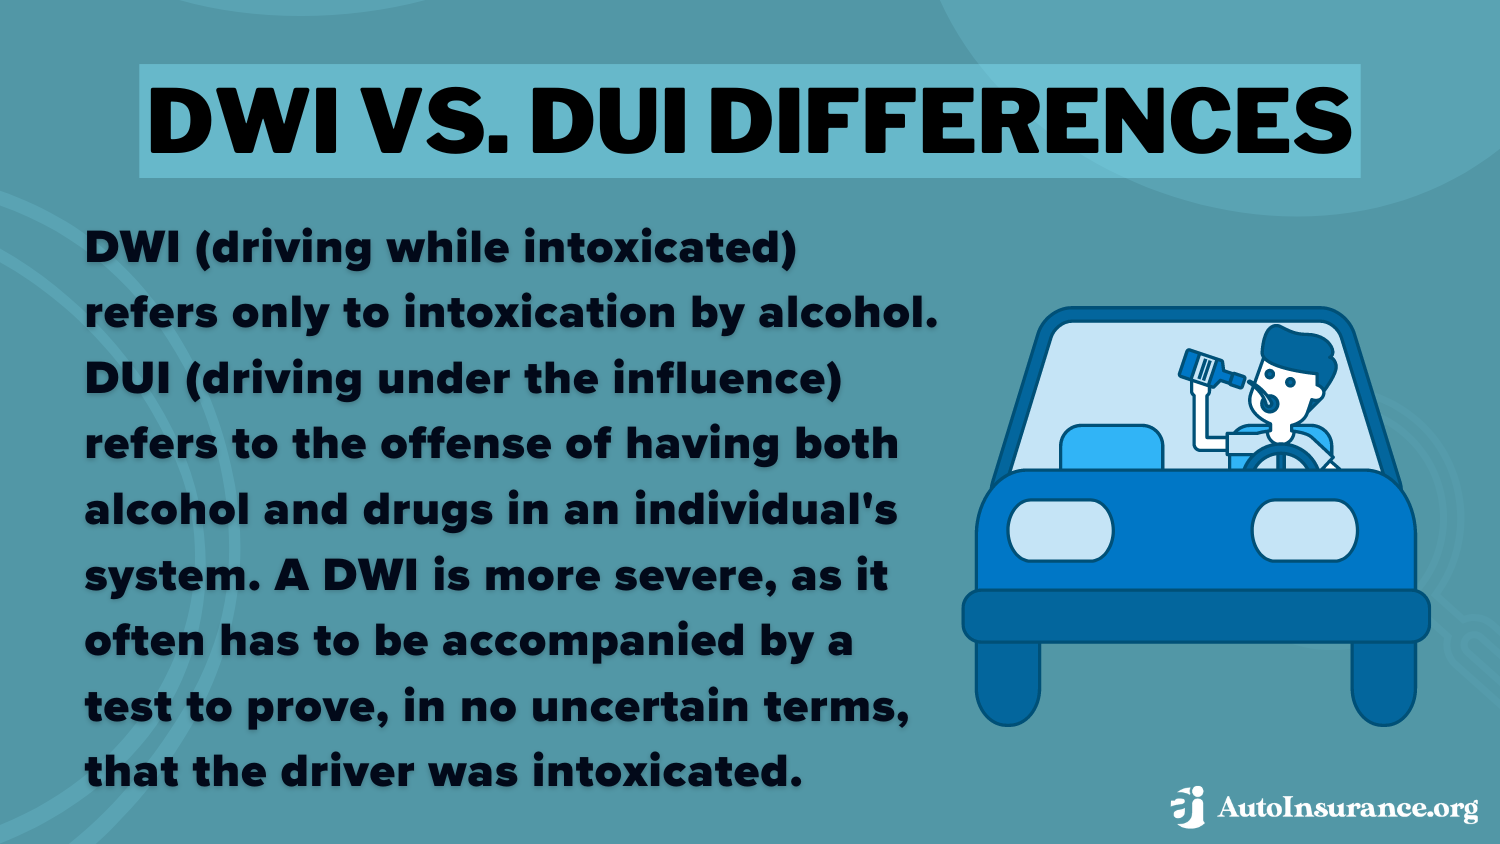
A DWI (Driving While Intoxicated) conviction typically classifies a driver as "high-risk," leading to premium increases of 70% to 100% or more. Most standard insurers may non-renew your policy, requiring you to seek coverage through non-standard carriers and file an SR-22 or FR-44 form with your state’s DMV to prove financial responsibility.
A DWI or DUI conviction is one of the most significant events that can occur in a driver's insurance history. It transforms the relationship between the policyholder and the insurer, moving the driver from the "preferred" or "standard" market into the "non-standard" or "high-risk" market. In 2026, the integration of real-time data sharing between state Departments of Motor Vehicles (DMVs) and insurance carrier databases means that convictions are identified almost instantly, triggering immediate underwriting reviews. Understanding how auto insurance DWI coverage works is essential for maintaining legal driving status and managing the substantial financial burden that follows a conviction.
The Immediate Impact of a DWI on Insurance Eligibility
When an insurance company becomes aware of a DWI conviction, their actuarial risk assessment of the driver changes fundamentally. Actuaries use historical data to determine the likelihood of a driver filing a future claim. Statistics consistently show that drivers with a DWI conviction are significantly more likely to be involved in high-severity accidents. Consequently, the "loss ratio" for this demographic is much higher than for the general population.
Policy Cancellation vs. Non-Renewal
In many jurisdictions, an insurance company cannot cancel a policy mid-term solely because of a DWI conviction unless the driver’s license is suspended or revoked. However, the insurer is under no obligation to renew the policy at the end of the term. In 2026, the trend among major "preferred" carriers is to issue a notice of non-renewal as soon as a DWI is finalized in court. This forces the driver to shop for coverage in the non-standard market, often with very little lead time.
The High-Risk Designation
Being labeled "high-risk" does not mean you cannot get insurance; it means the pool of available insurers shrinks and the cost increases. High-risk drivers are often directed toward specialized subsidiaries of major companies or niche insurers that focus specifically on the non-standard market. These companies are equipped to handle the unique filing requirements and higher claims frequency associated with DWI histories.
SR-22 and FR-44 Financial Responsibility Filings
One of the most misunderstood aspects of auto insurance DWI coverage is the SR-22 (or FR-44 in states like Florida and Virginia). Contrary to popular belief, an SR-22 is not an insurance policy itself; it is a certificate of financial responsibility.
How the SR-22 Works
When a court or the DMV requires an SR-22, your insurance company must electronically file a form with the state confirming that you carry at least the minimum required liability coverage. In 2026, these filings are almost entirely digital and integrated into the state's licensing system. If your policy lapses for any reason—such as a missed payment—the insurance company is legally mandated to notify the DMV immediately via an SR-26 filing. This notification usually results in the immediate suspension of the driver's license.
The FR-44 Distinction
In states that use the FR-44, the requirements are even more stringent. While an SR-22 only requires the state-minimum liability limits, an FR-44 often requires significantly higher limits (e.g., $100,000/$300,000/$50,000). The state's logic is that high-risk drivers should have more protection available to potential victims because of their proven history of dangerous behavior. This higher limit requirement further inflates the cost of the premium.

Analyzing the Cost of DWI Insurance in 2026
The financial repercussions of a DWI conviction extend far beyond court fines and legal fees. The insurance premium hike is often the most expensive long-term consequence. In the 2026 insurance market, several factors influence the final quote for a driver with a DWI.
Average Premium Increases
While rates vary by state and carrier, a single DWI conviction typically results in a premium increase ranging from 70% to 150%. For example, if a standard driver was paying $1,500 per year, a post-DWI premium could easily reach $3,000 to $4,500. These rates generally remain elevated for three to five years, though some states allow insurers to consider a DWI for up to ten years when calculating premiums.
Compounding Factors
The cost is not determined by the DWI alone. Insurers look at the "totality of the risk." If the DWI was accompanied by other infractions—such as reckless driving, speeding, or an accident—the rate increase will be even more severe. Furthermore, younger drivers (under age 25) with a DWI see the highest percentage increases because they are already in a high-risk demographic even before the conviction.
Coverage Limitations and Exclusions
It is a common question whether auto insurance "covers" a DWI accident. The answer depends on the type of coverage and the specific language of the policy.
Liability Coverage
Under standard personal auto policies, liability coverage (Bodily Injury and Property Damage) will generally pay out to victims even if the policyholder was intoxicated at the time of the accident. This is a matter of public policy; the insurance exists to protect the innocent third parties harmed by the driver's actions. However, after the claim is paid, the insurer will almost certainly move to non-renew the policy.
First-Party Exclusions
Where coverage becomes complicated is with "first-party" claims, such as Collision or Medical Payments (MedPay). Some policies in 2026 contain specific exclusions for "criminal acts." If a DWI is classified as a felony or a specific type of criminal offense in your jurisdiction, the insurer might attempt to deny coverage for the damage to your own vehicle or your own medical bills. You must review the "Exclusions" section of your policy to understand if intoxication limits your right to first-party recovery.
The Non-Standard Insurance Market
If you are dropped by a major carrier like State Farm or Geico, you will need to look toward the non-standard market. Companies in this space, such as Progressive (which has a large non-standard division), The General, or Bristol West, specialize in higher-risk profiles.
Assigned Risk Plans
If you are unable to find any private company willing to cover you, most states offer an "Assigned Risk Plan" or a "Residual Market Plan." These are state-mandated programs where all insurance companies operating in the state must share the risk of high-risk drivers. This is the insurance of last resort. While it ensures you can legally drive, it is almost always the most expensive option available.
Comparing Standard vs. High-Risk Policies
| Feature | Standard Policy | High-Risk (DWI) Policy |
|---|---|---|
| Average Premium | Competitive/Market Rate | 70% - 150% Surcharge |
| Carrier Availability | Most major national brands | Specialized or niche carriers |
| State Filings | Not required | SR-22 or FR-44 usually required |
| Payment Options | Flexible (Monthly, Semi-Annual) | Often requires larger down payments |
| Renewal Guarantee | High (unless multiple claims) | Low; subject to strict underwriting |
| Limits | High limits easily available | Limits may be capped by the carrier |
State-Specific Variations in DWI Coverage
Insurance is regulated at the state level, which means the consequences of a DWI vary significantly depending on where you live. In 2026, state laws continue to evolve regarding how long a DWI can impact your rates.
- California: Under Proposition 103, insurers can only consider accidents and violations from the last three years for most surcharges, but a DUI conviction can impact the "Good Driver" discount for ten years.
- Florida & Virginia: These states utilize the FR-44, which mandates higher liability limits for DWI offenders, significantly increasing the total cost of ownership for a vehicle.
- North Carolina: The state uses a "Safe Driver Incentive Plan" (SDIP) which assigns points for convictions. A DWI is a 12-point offense, the highest possible, leading to a massive, state-mandated percentage increase in premiums.
- New York: Insurers have significant leeway in non-renewing policies following a DWI, and the state's "no-fault" personal injury protection (PIP) can be excluded if the injury occurred while committing a felony or while intoxicated.
Steps to Secure Coverage After a DWI Conviction
Securing auto insurance with a DWI on your record requires a methodical approach. Following these steps can help mitigate the costs and ensure you remain compliant with state law.
- Obtain Your Driving Record: Before shopping, get an official copy of your Motor Vehicle Record (MVR). You need to know exactly what the insurance companies will see, including the date of conviction and the specific statute violated.
- Confirm SR-22 Requirements: Contact your state DMV to find out if you need an SR-22 and for how long. Most states require this for three years from the date of license reinstatement.
- Shop the Non-Standard Market: Do not waste time with companies that explicitly state they do not cover high-risk drivers. Focus on carriers that advertise SR-22 filings.
- Consider Higher Deductibles: To offset the massive premium increase, you may need to raise your deductibles on Comprehensive and Collision coverage. This lowers your monthly cost but increases your out-of-pocket expense if an accident occurs.
- Inquire About Ignition Interlock Discounts: In 2026, many states and some insurance companies offer small discounts if you voluntarily or mandatorily install an Ignition Interlock Device (IID). While the discount won't cancel out the DWI surcharge, every bit helps.
Long-Term Recovery and Rate Reduction
A DWI is not a permanent financial death sentence. Over time, the impact of the conviction on your insurance rates will diminish.
The Declining Surcharge
Most insurers use a tiered surcharge system. The first year after the conviction is the most expensive. If you maintain a clean driving record—no speeding tickets, no accidents—the surcharge often decreases annually. By the end of the three-to-five-year high-risk period, you may be eligible to move back into the standard market.
Re-evaluating Your Carrier Regularly
It is a mistake to stay with a high-risk carrier longer than necessary. Once your SR-22 requirement ends and the "look-back" period for your state passes, you should immediately shop for coverage among preferred carriers. Many drivers overpay for years because they fail to realize they are no longer classified as high-risk.
Frequently Asked Questions
Does a DWI in another state affect my insurance? Yes. In 2026, the Driver License Compact (DLC) and the National Driver Register (NDR) ensure that nearly all states share conviction data. If you get a DWI in a different state, it will be reported to your home state's DMV and will subsequently appear on the MVR that your insurance company checks during renewal.
Can I get insurance if my license is currently suspended? You can often obtain "non-owner insurance" with an SR-22 even if you do not own a vehicle or if your license is suspended but you are seeking a restricted/hardship permit. This is often a prerequisite for the DMV to reinstate your driving privileges.
Will my insurance company find out about my DWI if I don't tell them? Yes. Insurance companies typically run an MVR check at every renewal period (every 6 or 12 months). Even if they do not check mid-term, the conviction will be discovered at the next renewal. Attempting to hide a conviction can be considered material misrepresentation, which is grounds for policy rescission and claim denial.
What is the "look-back" period for a DWI in 2026? The look-back period varies by state and insurer. For criminal sentencing, it is often 10 years. For insurance underwriting, it is most commonly 3 to 5 years for the primary surcharge, though some premium calculations may be affected for up to 10 years.
Does a DWI affect my life insurance rates too? Often, yes. Life insurance underwriters view a recent DWI as a sign of high-risk behavior. Depending on the carrier, you may face higher premiums or a waiting period (often 1-2 years) before they will issue a new policy following a conviction.
Practical Recommendation: If you are facing a DWI conviction, do not wait for your current insurer to send a non-renewal notice. Proactively contact an independent insurance agent who has access to multiple non-standard carriers. They can shop your profile across several companies to find the most competitive high-risk rate and ensure your SR-22 is filed correctly and timely to avoid further license complications.
Image Gallery
Select an image to open it in a new tab.



Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
