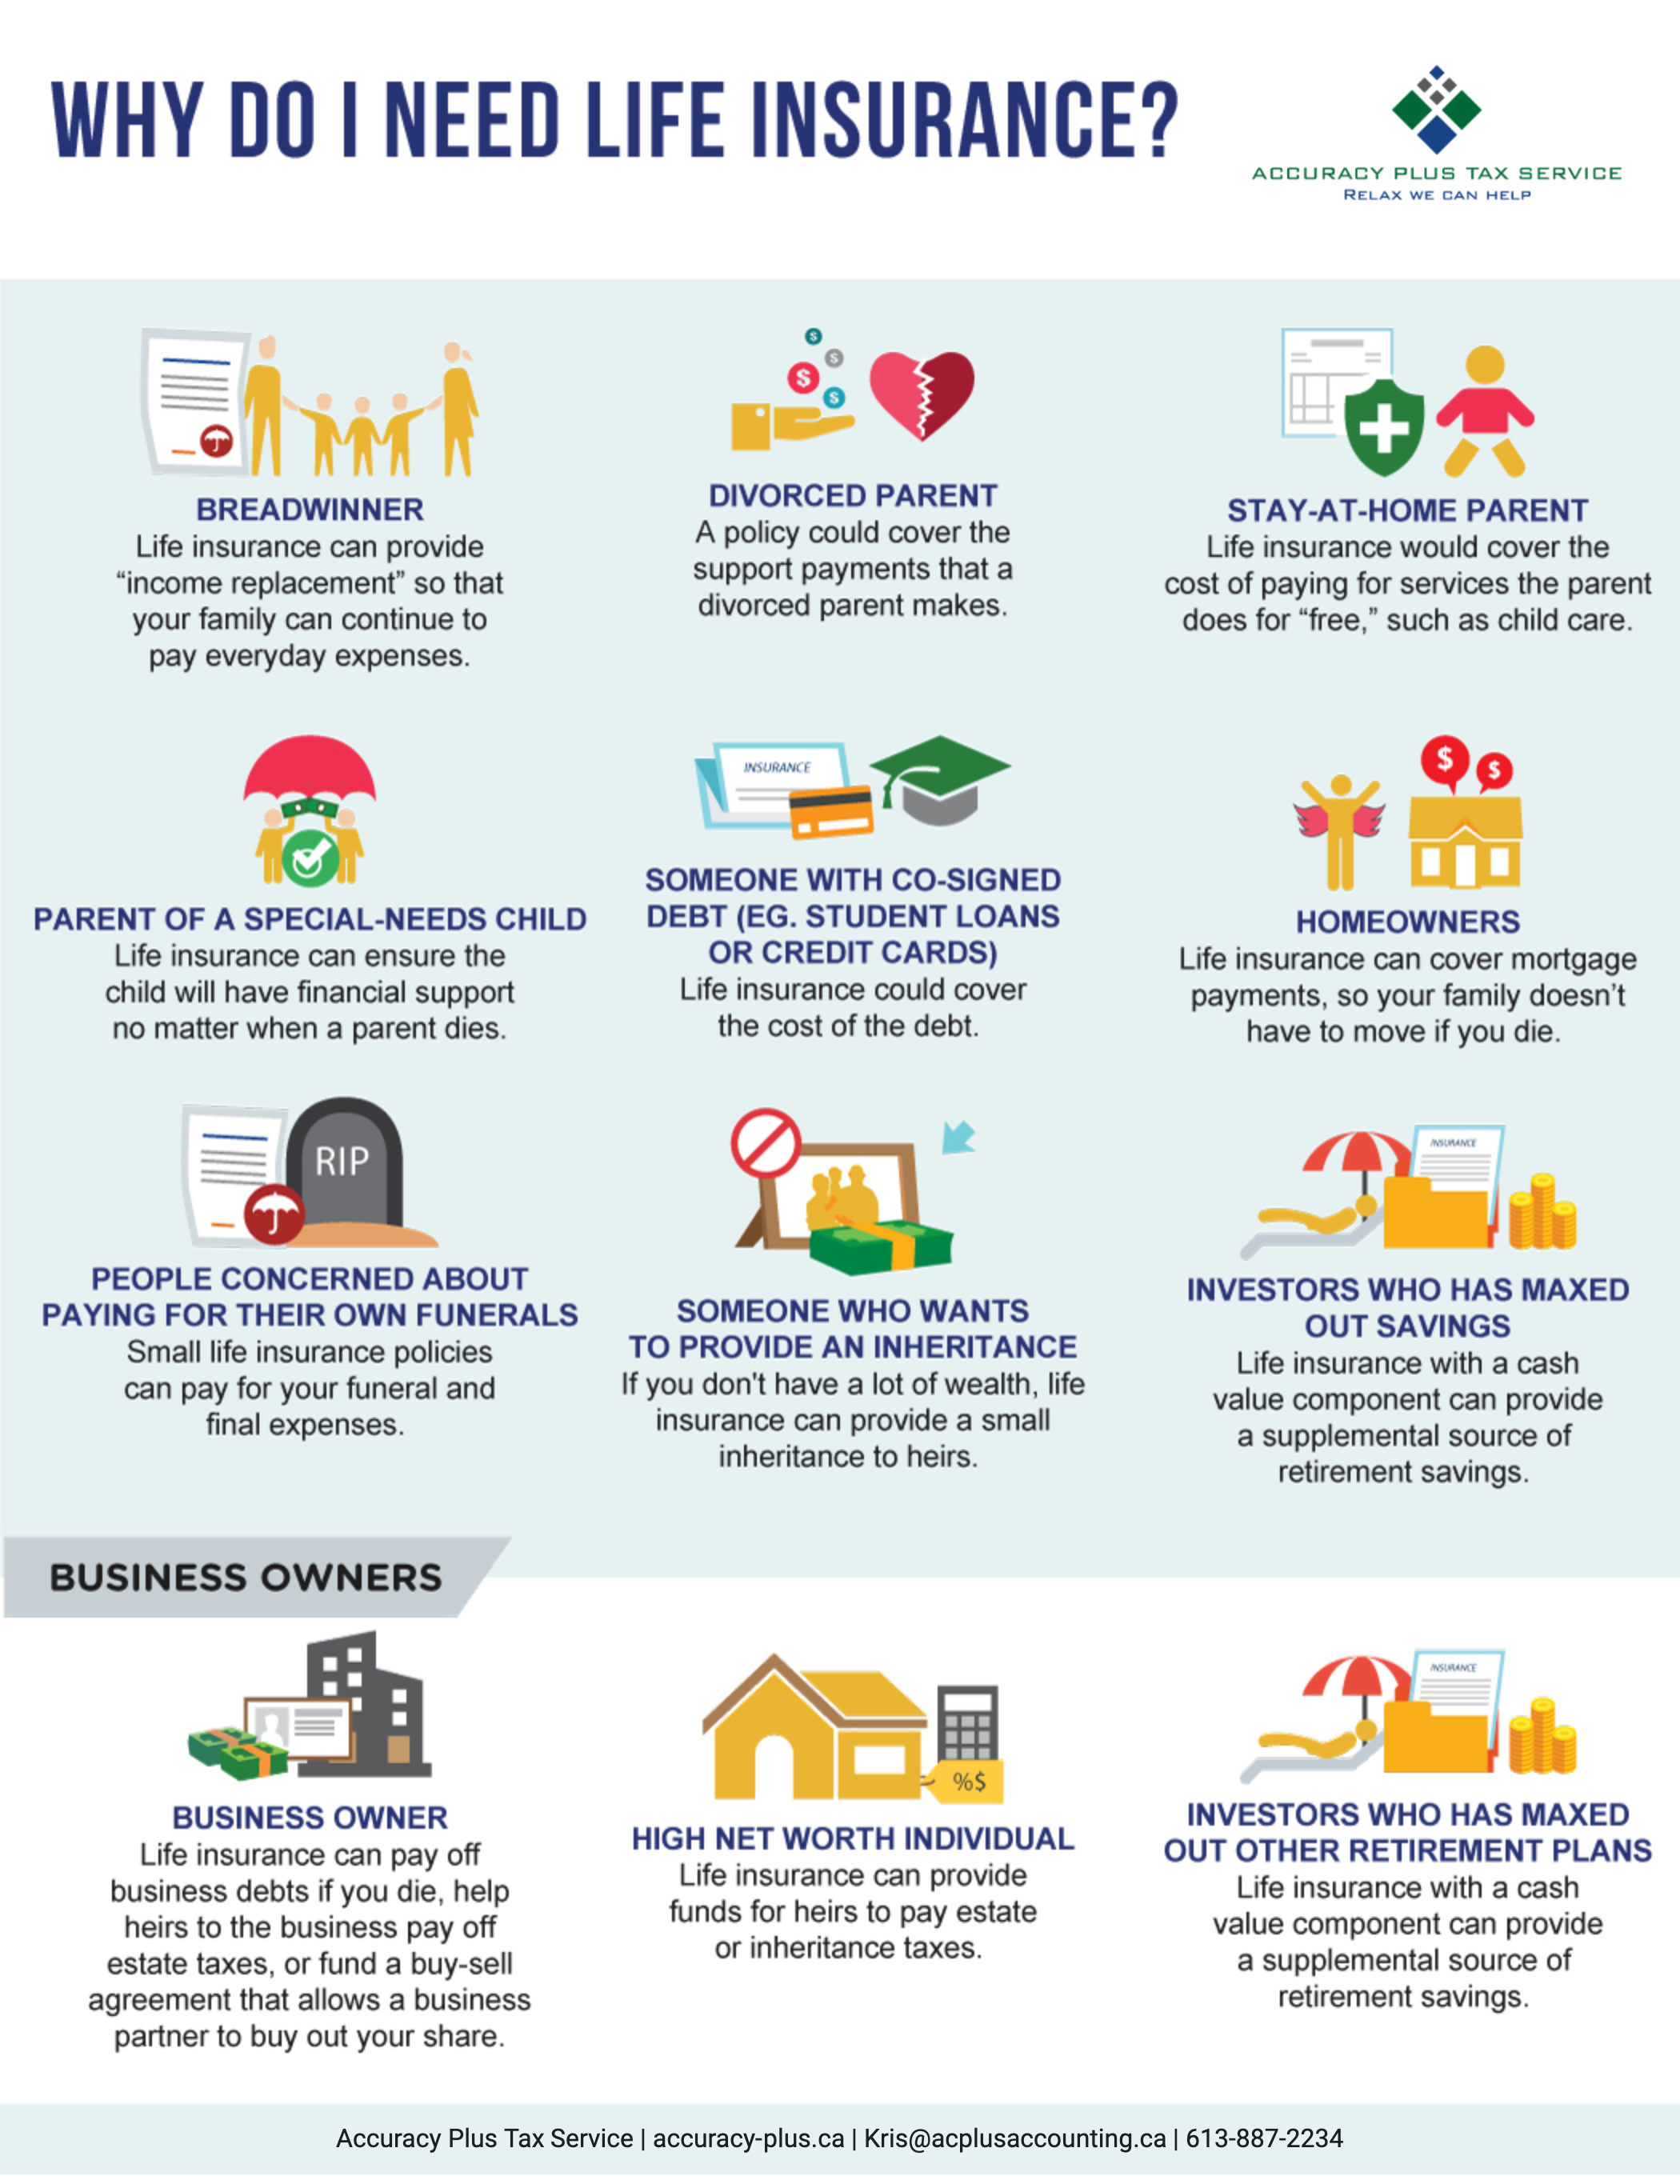
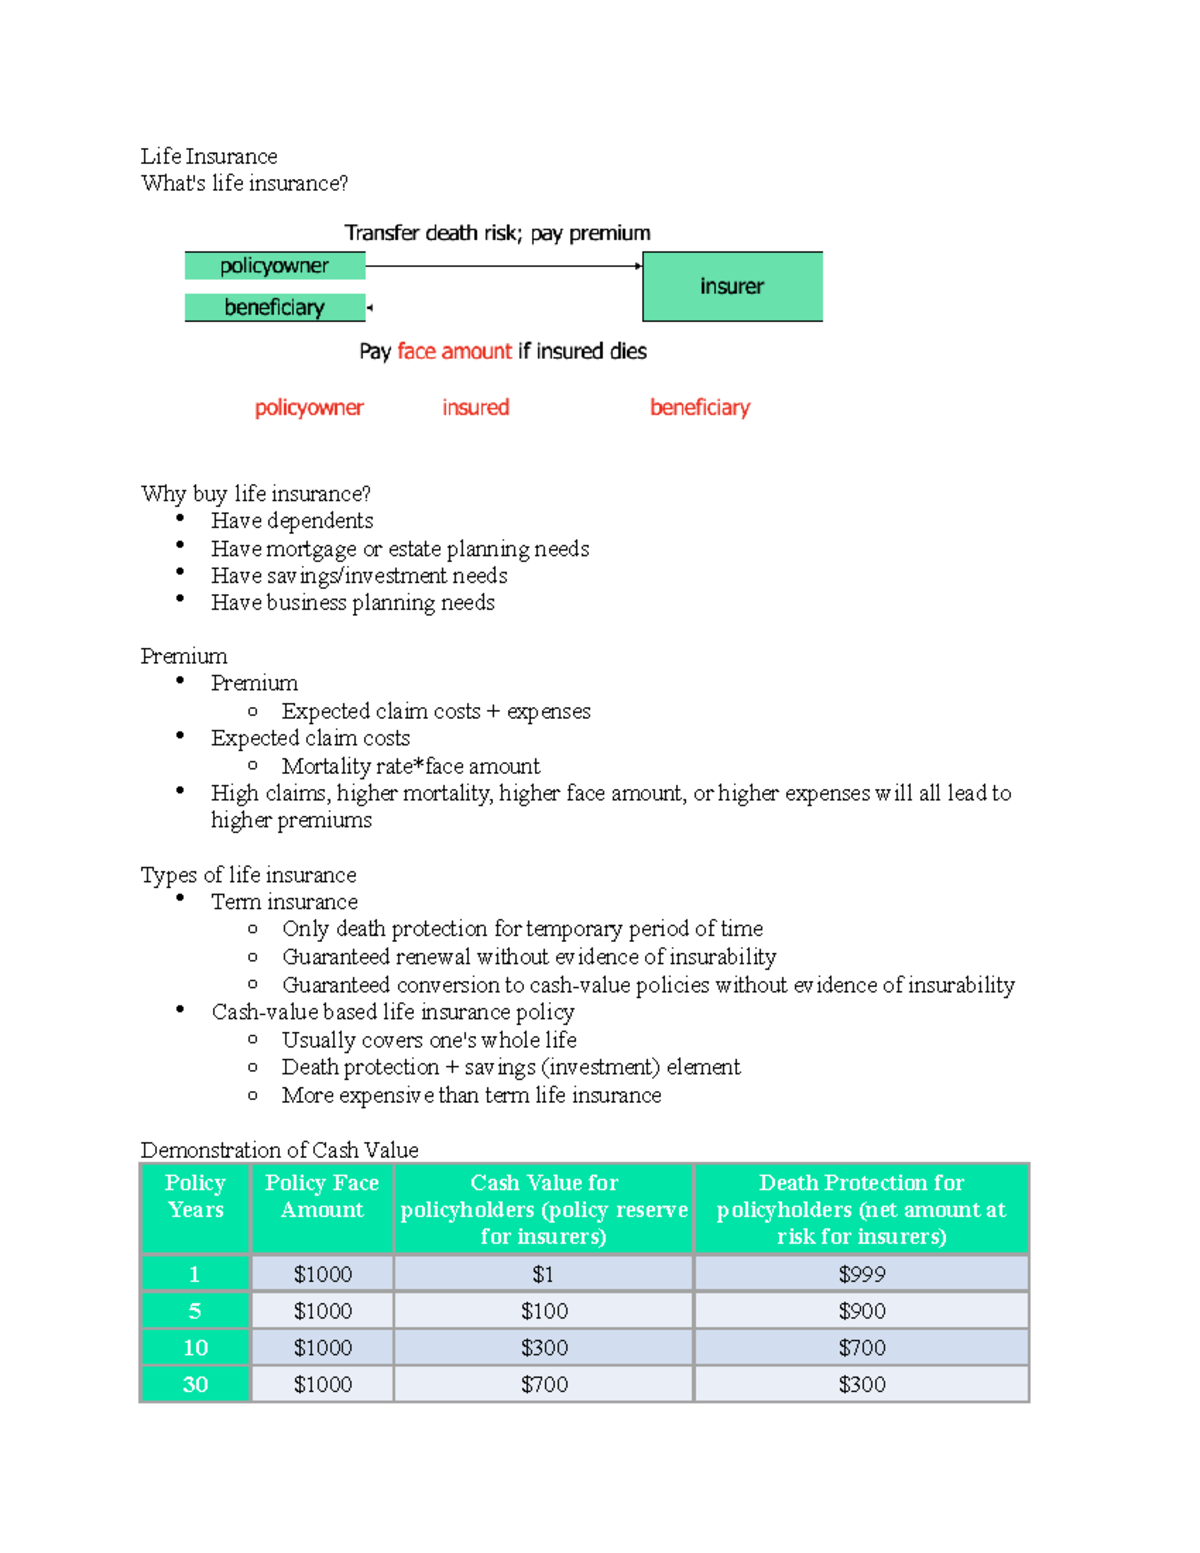
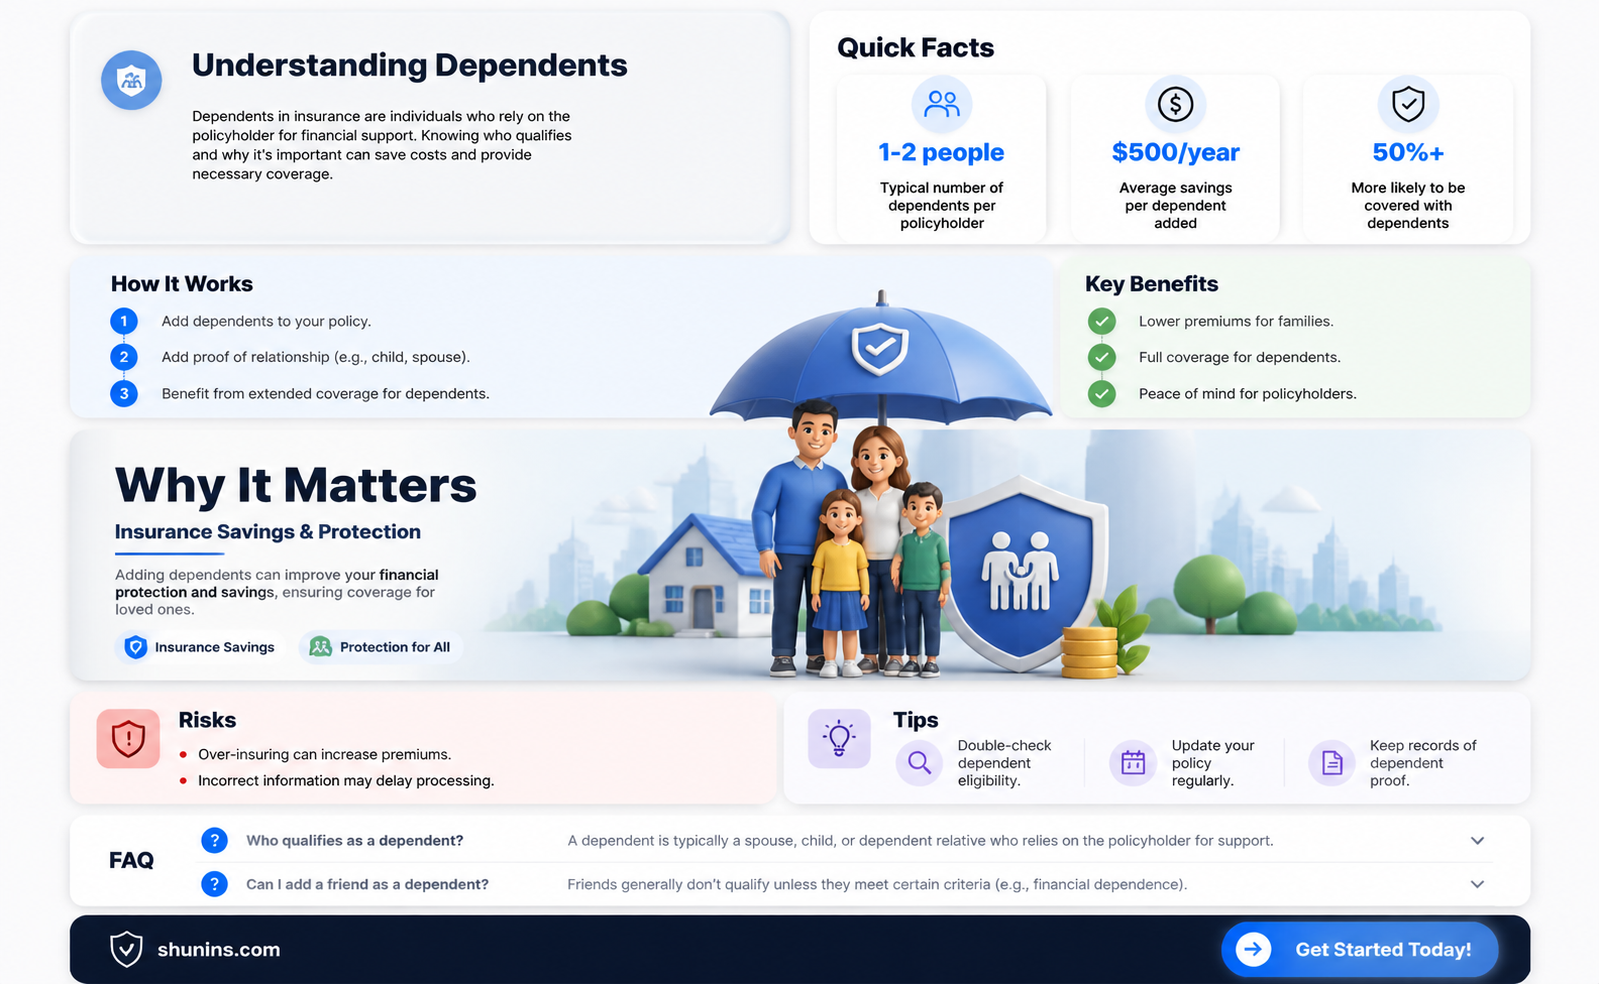
Dependent life insurance through The Standard provides essential financial protection for your family by offering a death benefit if your spouse, domestic partner, or eligible children pass away. It serves as a safety net to cover immediate final expenses, childcare transitions, and lost household contributions, ensuring that a family tragedy does not lead to a financial crisis.
Choosing the right insurance coverage is one of the most critical components of a robust financial plan. While most employees prioritize their own life insurance policies to protect their survivors, the importance of insuring dependents is often overlooked. As of 2026, the rising costs of final arrangements and the increasing economic value of household management make dependent life insurance a practical necessity for the modern workforce.
The Standard (Standard Insurance Company) is a leading provider of group life insurance policies. When your employer offers "Dependent Life" through The Standard, it is typically a group term life policy designed to be affordable, accessible, and easily managed through payroll deductions. This guide explores the specific reasons why this coverage is vital, how it functions within your benefits package, and what you should consider when selecting coverage levels.
Understanding the Financial Impact of a Dependent’s Death
The primary reason to secure dependent life insurance is to mitigate the sudden financial burden that follows a loss. Many people mistakenly believe that because a spouse or child does not provide the primary "paycheck," their death would not result in a financial loss. This is a significant misunderstanding of household economics.
Final Expenses and the Cost of Farewells
In 2026, the average cost of a traditional funeral, burial, and headstone can range from $12,000 to $18,000, depending on the region and specific services chosen. Even a simple cremation with a memorial service can easily exceed $5,000. For many families, coming up with this amount of cash on short notice is difficult. Dependent life insurance provides a lump-sum payment—often ranging from $5,000 to $50,000 for spouses and $2,000 to $10,000 for children—that can be used immediately to settle these accounts without draining your emergency savings or retirement funds.
The Economic Value of a Non-Working Spouse
If your spouse or partner stays at home or works part-time, their contribution to the household is often undervalued in strictly financial terms. Should they pass away, the surviving spouse may suddenly face massive costs for:
- Childcare and After-School Programs: Replacing the care provided by a stay-at-home parent is a significant monthly expense.
- Household Management: Services for cleaning, meal preparation, and transportation.
- Logistical Support: The "invisible labor" that allows the primary earner to focus on their career.
By having a dependent life policy through The Standard, the surviving partner has a financial buffer to pay for these services during the difficult transition period.
The Unique Advantages of The Standard’s Group Coverage
Purchasing life insurance on the individual market can be time-consuming and expensive. When you opt into your employer’s plan with The Standard, you benefit from "group" dynamics that offer advantages you cannot find elsewhere.
1. Guaranteed Issue (GI) Opportunities
One of the most compelling reasons to choose insurance from The Standard is the "Guaranteed Issue" window. During your initial eligibility period (usually when you are first hired) or during certain Open Enrollment cycles, you can often secure a baseline level of coverage for your spouse and children without having to answer medical questions or undergo a physical exam.
This is a lifeline for families where a spouse may have a pre-existing condition—such as diabetes, heart issues, or a history of cancer—that would make them uninsurable or prohibitively expensive on the private market. As long as you enroll during the designated period, the coverage is typically granted automatically.
2. Convenience and Payroll Integration
In 2026, managing multiple bills and subscriptions is a chore. The Standard’s dependent life insurance premiums are deducted directly from your gross pay. This "set it and forget it" approach ensures that coverage never lapses due to a missed payment. Furthermore, because it is a group plan, the rates are often significantly lower than individual term policies because the risk is spread across the entire company’s workforce.
3. Simplified Claims Process
When a dependent passes away, the last thing a grieving person wants to do is navigate a complex legal bureaucracy. The Standard is known for its streamlined claims process for group policies. Since your employer already has much of your basic information on file, the administrative hurdle for the beneficiary is significantly lowered.

Comparing Spouse and Child Coverage
The coverage amounts for dependents are generally structured differently than the employee’s own life insurance. The following table illustrates typical coverage structures offered by The Standard in 2026.
| Feature | Spouse/Partner Coverage | Child Coverage |
|---|---|---|
| Common Coverage Limits | $5,000 to $250,000 (often capped at 50% of employee amount) | $2,000 to $20,000 (flat amount) |
| Medical Underwriting | Required for amounts over the Guaranteed Issue limit | Rarely required |
| Age Limitations | Typically ends at age 70 or 75 | Usually covers birth to age 26 |
| Premium Basis | Often based on the spouse's age | One flat rate covers all eligible children |
| Portability | Often portable if employment ends | Often portable |
Note: Specific limits and rules are governed by your employer's specific contract with The Standard. Always refer to your Summary Plan Description (SPD).
Evaluating the "Why" for Child Life Insurance
Insuring a child is a sensitive topic that many parents prefer not to think about. However, from a practical standpoint, child life insurance serves a specific purpose. It is not about "replacing" a child, which is impossible; it is about allowing the parents the time and space to grieve.
Grief Leave and Time Away from Work
While the death benefit for a child is usually smaller (e.g., $10,000), this money can replace lost income if the parents need to take extended unpaid leave from work. Standard bereavement leave offered by corporations is often limited to three to five days. For most parents, returning to high-level professional responsibilities a week after losing a child is untenable. The insurance benefit provides the financial freedom to take additional weeks or months off to focus on mental health and supporting other surviving family members.
Future Insurability
Some policies offered through The Standard include a "conversion" or "guaranteed purchase" option. This means that when the child reaches the age of 26 and is no longer an eligible dependent under your plan, they may have the right to convert their coverage into a permanent individual policy without a medical exam. This protects their ability to have life insurance later in life, regardless of any health conditions they may have developed in childhood or young adulthood.
Important Considerations and Potential Limitations
While dependent life insurance is generally a wise investment, you must understand the "fine print" of your policy with The Standard to ensure there are no surprises during a claim.
1. Evidence of Insurability (EOI)
If you decline coverage when you are first hired and decide to add your spouse later during an Open Enrollment period, The Standard will likely require "Evidence of Insurability." This is a medical questionnaire that assesses the health of the dependent. If the spouse has significant health issues, they could be denied coverage at that stage. This is why many financial advisors recommend electing the Guaranteed Issue amount as soon as it is offered.
2. The "Employee Must Be Covered" Rule
Under most contracts with The Standard, you cannot purchase dependent life insurance unless you are also enrolled in the basic or supplemental life insurance plan for yourself. The dependent coverage is "attached" to your primary policy.
3. Suicide Clauses and Exclusions
Like most life insurance policies, there is typically a two-year suicide exclusion clause. If a dependent takes their own life within the first two years of the policy being in force, the death benefit may be denied, and only the premiums paid will be returned. Additionally, certain "war exclusions" or "illegal act exclusions" may apply, though these are less common in standard group life policies.
4. Age Reductions
For spouse coverage, the benefit amount may decrease as the spouse reaches certain age milestones (e.g., age 65 or 70). This is a standard feature of group term life insurance, as the risk of mortality increases significantly with age.
Tax Implications of Dependent Life Insurance
In the United States, the Internal Revenue Service (IRS) has specific rules regarding employer-provided life insurance. According to IRS Publication 15-B, if an employer pays for dependent life insurance, the value of that coverage is generally tax-free to the employee as long as the face amount is $2,000 or less.
However, most employees pay for their dependent coverage using after-tax dollars through payroll deduction. In this scenario, the death benefit paid out by The Standard is typically 100% tax-free to the beneficiary. This makes it an incredibly efficient way to transfer funds during a crisis, as none of the benefit is lost to federal or state income taxes.
Common Mistakes to Avoid
- Underestimating the Cost of a Spouse’s Labor: Don't just look at the spouse's income. Look at the cost to replace their role in the family.
- Waiting Until a Health Crisis: You cannot buy insurance once a terminal diagnosis is received. The best time to enroll is during the Guaranteed Issue window.
- Assuming Work Coverage is Enough: For high-net-worth individuals, the $25,000 or $50,000 provided by a group plan may not be enough. Treat The Standard’s policy as a "base layer" and supplement with private insurance if necessary.
- Forgetting to Update Beneficiaries: While the employee is usually the automatic beneficiary for dependent life insurance, ensure your primary life insurance beneficiary designations are updated following a divorce or a change in family status.
Frequently Asked Questions
Does dependent life insurance cover stepchildren or foster children?
Yes, in most policies offered by The Standard, stepchildren and legally adopted children are covered under the same terms as biological children. Foster children may be covered if they meet the legal residency and support requirements defined in the specific plan document. You should verify the definition of "eligible child" in your Summary Plan Description.
What happens to the coverage if I leave my current job?
If you leave your employer, your group dependent life insurance usually ends. However, The Standard often provides a "Portability" or "Conversion" option. Portability allows you to take the term coverage with you at group-like rates, while conversion allows you to turn it into an individual permanent policy. You must typically apply for this within 31 days of leaving your job.
Can I cover my domestic partner under The Standard’s dependent life?
Many modern group plans from The Standard include "Designated Domestic Partners" as eligible dependents. This usually requires a signed affidavit of domestic partnership or proof of joint residency and financial interdependency. Check with your HR department for the specific requirements of your company's plan.
Is there an age limit for child coverage?
Standard coverage usually applies to children until they reach age 26, regardless of their student or marital status. However, some older policies may still require the child to be a full-time student to remain covered after age 19. For children with permanent disabilities that began before the age limit, coverage may often be extended indefinitely.
Can both parents cover the same child if they work for the same company?
In many cases, The Standard (and other group insurers) has a "no duplication of coverage" rule. This means if both parents work for the same employer, only one parent can claim the child as a dependent for life insurance purposes. This prevents a "double payout" for the same risk, which helps keep premiums low for the entire group.
Final Recommendation: Secure Your Family's Foundation
In 2026, the financial complexity of maintaining a household requires proactive planning. Dependent life insurance from The Standard is not about expecting the worst; it is about being prepared for the unexpected so that your family can focus on healing rather than debt.
Next Steps:
- Review your benefits portal: Check your current enrollment status and see if you are within a Guaranteed Issue window.
- Calculate the gap: Estimate the cost of a funeral and at least six months of childcare/household help. If your savings cannot cover this, you need the insurance.
- Confirm beneficiary info: Ensure your employer has your correct contact information and that you understand the process for filing a claim should it ever become necessary.
Image Gallery
Select an image to open it in a new tab.



Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
