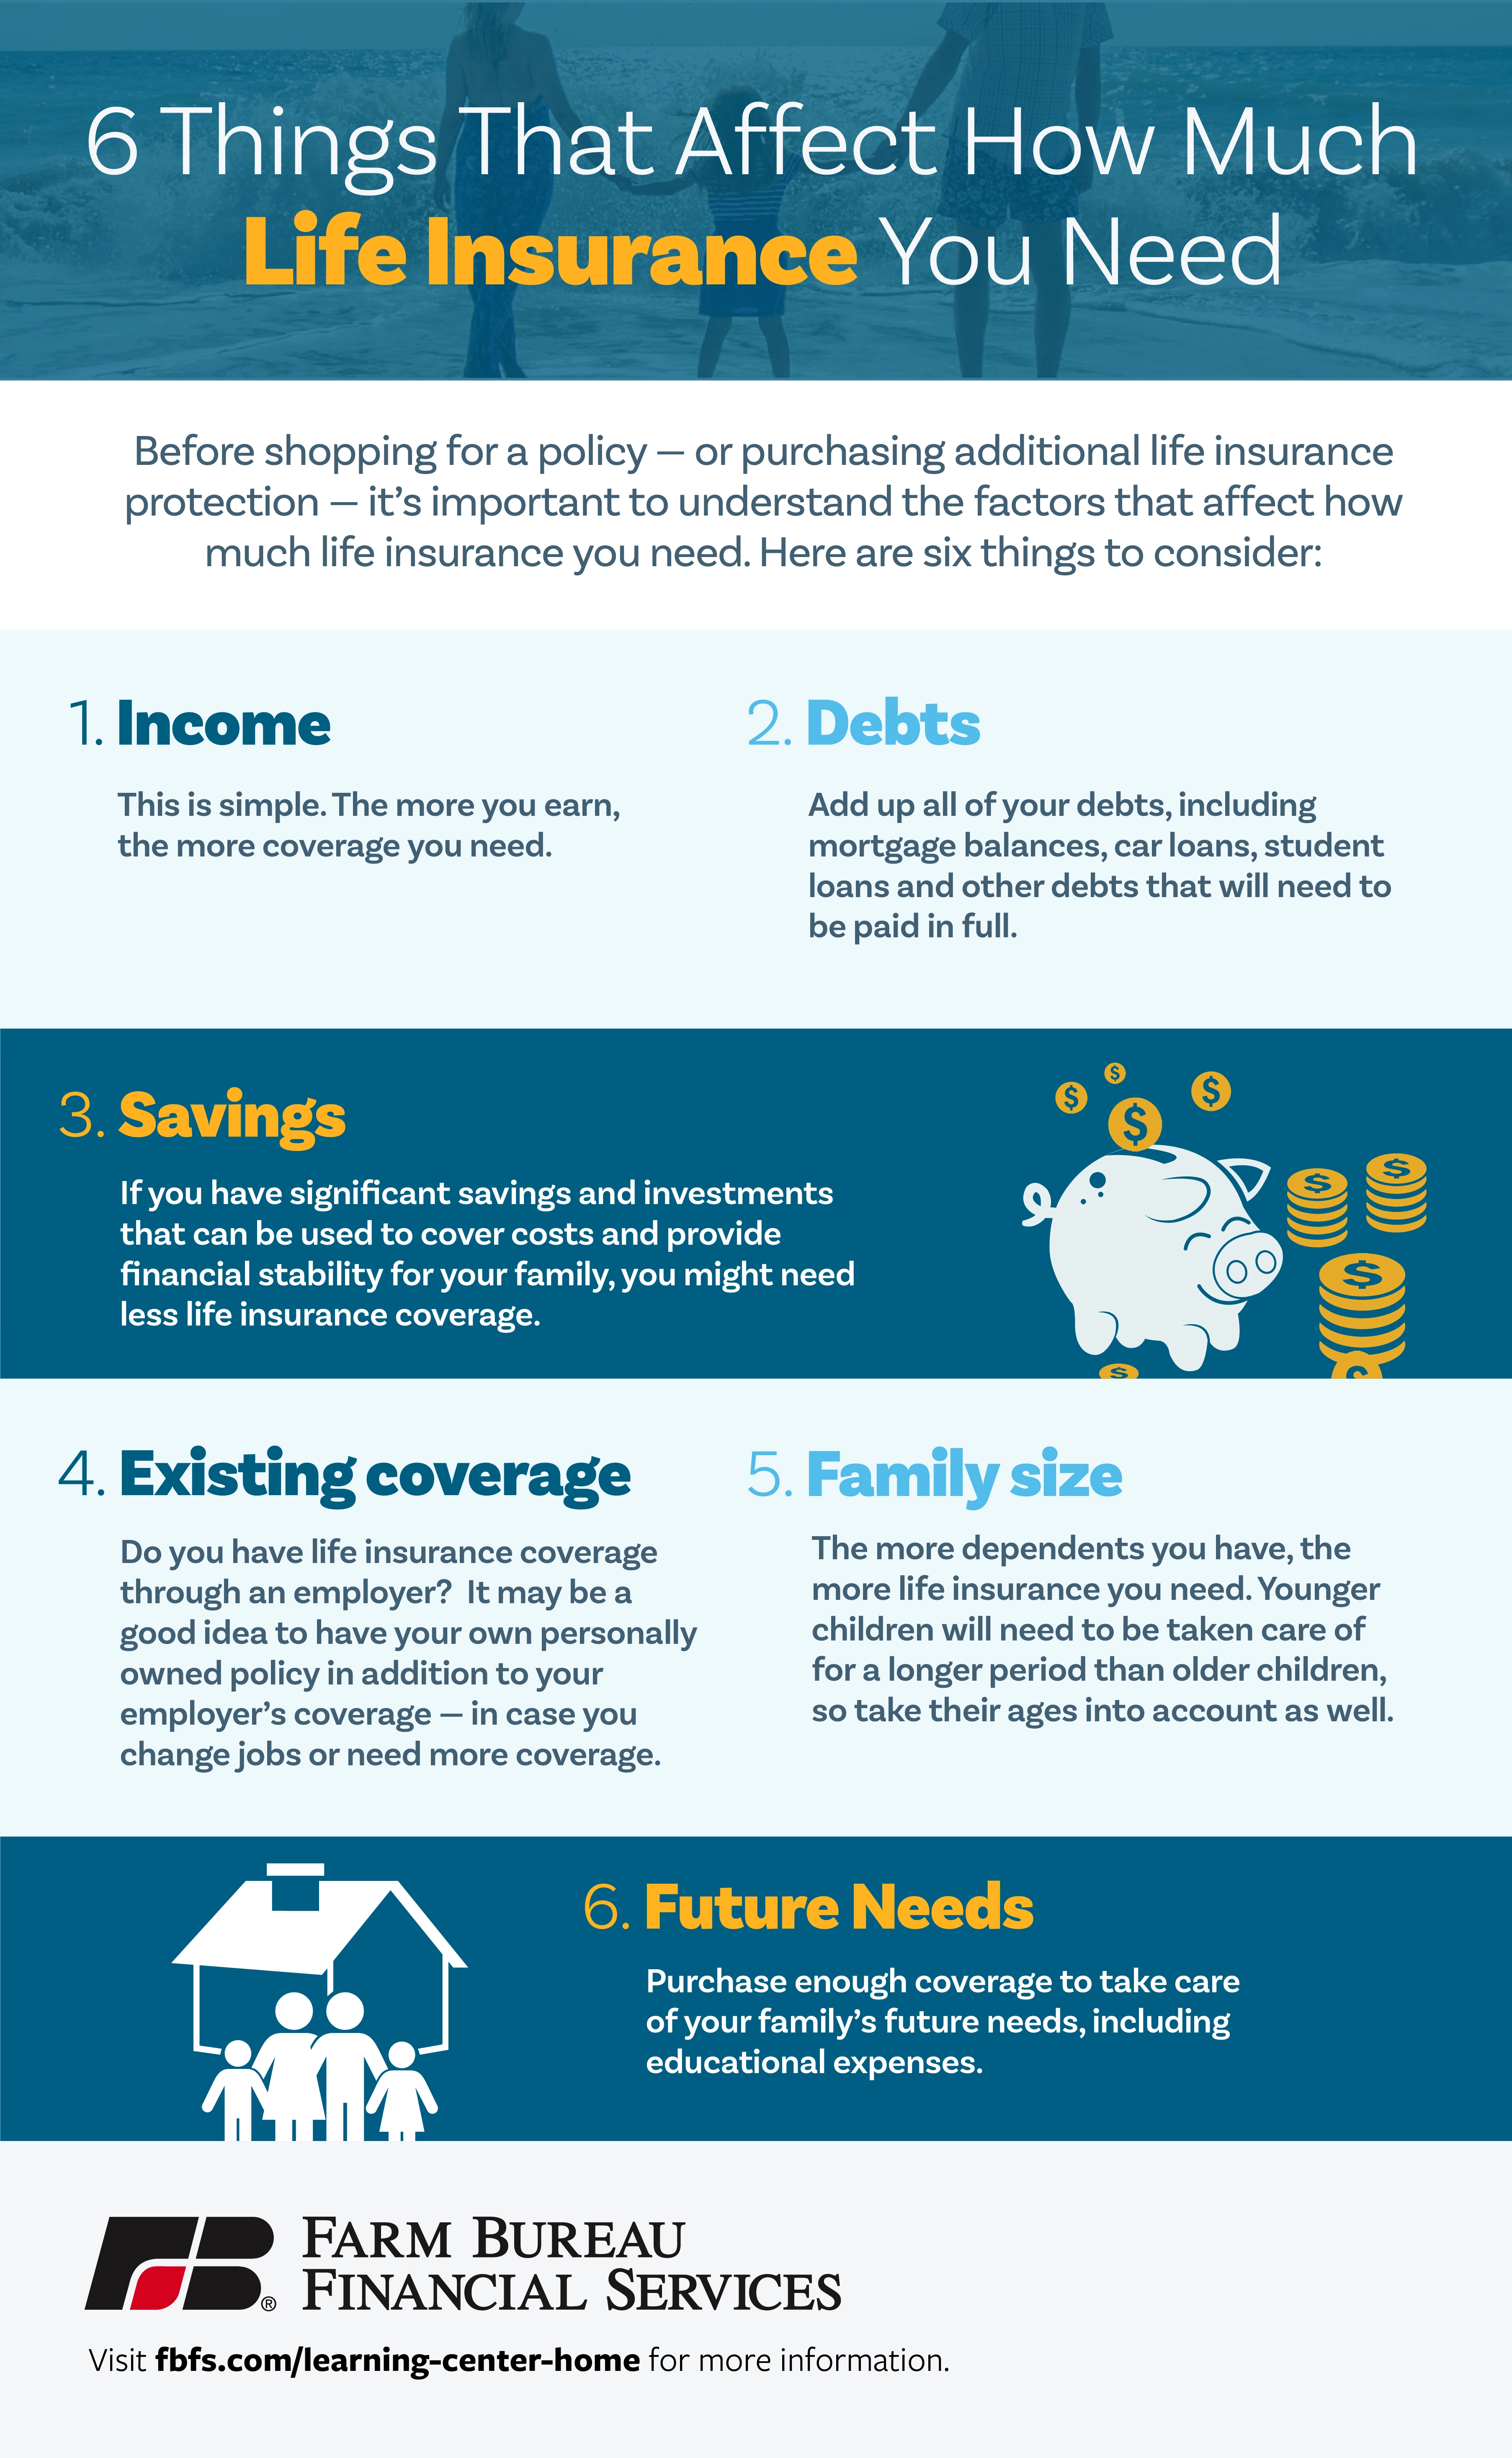
Life events that trigger the need for life insurance typically involve significant changes in financial responsibilities, such as getting married, having children, buying a home, starting a business, or taking on new debt that would burden dependents if you were to pass away.
Navigating the financial landscape of adulthood requires anticipating changes that alter your family's economic stability. While purchasing life insurance can feel like an abstract task, certain milestones dramatically shift your risk profile. During these moments, the absence of a safety net can expose your loved ones to severe financial hardship, making coverage not just a precautionary measure, but an essential component of responsible financial planning. Understanding which milestones demand a policy—or an upgrade to your existing coverage—ensures that your financial protection evolves right alongside your life.
1. Getting Married and Combining Finances
Entering into a legal marriage fundamentally changes your legal and financial obligations. When you tie the knot, your financial life becomes intertwined with your partner's. Many couples pool their incomes to manage shared expenses such as rent, mortgages, utility bills, and consumer debt. If one partner were to pass away unexpectedly, the surviving spouse might struggle to maintain their standard of living, cover the shared debts, or pay off the remaining mortgage on a single income.
Life insurance acts as an income-replacement mechanism during this transition. Even if both partners work, the sudden loss of one salary can derail long-term plans, such as retirement savings or purchasing a home.
Key Financial Considerations for Newlyweds
- Income Disparity: If one spouse earns significantly more or stays home to manage household labor, the surviving partner faces a steep financial deficit.
- Shared Debt: Legally, certain debts may remain with the estate or the co-signer, requiring immediate liquidity that savings alone might not cover.
- Future Goals: A policy ensures that joint objectives, such as building an emergency fund or funding future real estate purchases, remain achievable.
2. Buying a Home or Taking Out a Mortgage
Purchasing residential real estate is typically the largest financial transaction an individual or couple will undertake. Securing a 15-year or 30-year mortgage creates a massive, long-term liability. While the property itself serves as collateral for the lender, the obligation to make monthly payments rests squarely on the shoulders of the borrower.
If you die prematurely, your family could face foreclosure if they cannot sustain the mortgage payments on a reduced household income. A dedicated life insurance policy—often structured as a term life policy matching the duration of the mortgage—ensures that the surviving family members can pay off the loan balance entirely or continue making payments without financial strain.

3. Having or Adopting Children
The arrival of a child is perhaps the most universally recognized trigger for purchasing life insurance. Raising a child to adulthood involves hundreds of thousands of dollars in direct expenses, ranging from basic daily necessities to higher education.
When you have dependents who rely entirely on your financial support, life insurance is no longer optional; it is a fundamental duty. A comprehensive policy provides resources for immediate childcare expenses, everyday living costs, and long-term milestones like college tuition if you are no longer there to provide.
Factors to Calculate When Evaluating Coverage for Parents
- Duration of Dependency: The number of years until your youngest child reaches financial independence (typically age 18 or 22).
- Childcare Costs: Expenses for daycare, babysitting, or nannies if a working parent passes away and the surviving parent must maintain full-time employment.
- Education Funding: Projected costs for trade school, community college, or a four-year university degree.
4. Starting a Business or Entering Business Partnerships
Entrepreneurship introduces complex financial liabilities that extend far beyond personal household finances. If you own a business, you may have commercial loans, equipment leases, lines of credit, or payroll obligations. Furthermore, if you have business partners, the sudden death of one partner can throw the company's operations and ownership structure into complete disarray.
Business owners utilize specialized life insurance products to protect their enterprise and their family. Key person insurance protects the company against the financial fallout of losing a vital employee or owner. Additionally, buy-sell agreements funded by life insurance allow surviving partners to purchase the deceased partner's share from their heirs, ensuring business continuity without external interference.
| Life Event | Primary Financial Risk | Recommended Insurance Strategy |
|---|---|---|
| Marriage | Loss of dual-income support and shared debt exposure | Term life policy covering income replacement and joint obligations |
| Homeownership | Inability to pay the mortgage after a primary earner's death | Term life policy matched to the length of the mortgage amortization schedule |
| Having Children | Long-term costs of childcare, upbringing, and higher education | High-multiplier term policy or blended permanent and term coverage |
| Business Ownership | Commercial debt liability and ownership disputes among heirs | Buy-sell agreements funded by life policies and key person coverage |
5. Taking on Significant Non-Mortgage Debt
While mortgages are secured by property, other forms of debt can create severe financial vulnerabilities. Personal loans, private student loans with co-signers, and substantial credit card balances do not always vanish upon death.
If a co-signer or estate administrator is legally tied to your personal debts, creditors may seek repayment from your remaining assets, potentially depleting the inheritance you intended for your family. Securing a policy with a death benefit large enough to clear these liabilities safeguards your estate from forced liquidation during an already difficult emotional time.
6. Going Through a Divorce or Entering a Stepfamily
Family structures evolve, and legal dissolutions often require adjustments to financial planning. During a divorce settlement, courts frequently mandate that the higher-earning or alimony-paying ex-spouse maintain a life insurance policy. This ensures that alimony and child support obligations continue uninterrupted if the payor passes away before the children reach adulthood.
Similarly, blending families by marrying someone who already has children introduces new dependencies. Even if you do not legally adopt your stepchildren, your income often supports the household they live in. Updating or acquiring coverage ensures that all children in the blended household are protected equitably.
7. Caring for Aging Parents or Adult Dependents with Special Needs
Not all dependents are minor children. Many adults find themselves in the "sandwich generation," simultaneously raising children while financially supporting aging parents or adult family members with disabilities or chronic illnesses.
If you provide financial assistance, housing, or medical oversight for an aging parent or a disabled sibling, your death would leave them without a caregiver or financial support system. Permanent life insurance or specialized trusts funded by life insurance proceeds can provide long-term care funding or lifetime financial management for dependents who cannot care for themselves.
Common Mistakes to Avoid When Buying Life Insurance During Major Life Events
Navigating these milestones requires careful planning. Avoiding common pitfalls ensures your policy performs as expected when your family needs it most.
- Underestimating Coverage Needs: Relying solely on a basic group life insurance policy provided by your employer is rarely sufficient. These policies typically offer coverage equal to one or two times your salary, which falls short for families with mortgages and young children.
- Waiting Too Long: Insurance premiums increase with age and the onset of health conditions. Purchasing a policy immediately after a major life event locks in lower rates while you are younger and healthier.
- Choosing the Wrong Term Length: Selecting a 10-year term when you have a newborn infant leaves you unprotected during their teenage and college years. Match your policy term to the actual duration of your financial liabilities.
Next Steps for Securing Coverage
When a major life event occurs, assess your current assets, debts, and future financial obligations before shopping for a policy. Consult with a licensed financial advisor or insurance professional to calculate an accurate death benefit. Request quotes from multiple reputable insurers to compare premiums, policy riders, and financial strength ratings. Taking proactive steps following a significant life milestone guarantees that your loved ones remain financially protected against unforeseen circumstances.
Image Gallery
Select an image to open it in a new tab.





Lars Thomsen
Global Labor Markets and Economic Strategy Editor
