Comprehensive Guide to the Cost and Acquisition of a $660 Million Life Insurance Policy

The annual cost of a $660 million life insurance policy typically ranges from $1.3 million to over $20 million, depending primarily on the insured’s age, health classification, and the specific structure of the policy (term versus permanent). Because no single insurance carrier can absorb this level of risk independently, these "jumbo" policies require complex syndication through global reinsurance markets and rigorous financial underwriting.
Obtaining a nine-figure life insurance policy is a sophisticated financial maneuver reserved for ultra-high-net-worth individuals (UHNWIs) and large-scale corporate entities. In 2026, the marketplace for such extreme death benefits is governed by tight capacity and strict "insurable interest" rules. This guide explores the pricing mechanisms, the underwriting hurdles, and the strategic implementation of a $660 million coverage plan.
The Economics of Ultra-High-Limit Coverage
When discussing a $660 million policy, the "cost" is not merely the premium. It involves a combination of annual outlays, the opportunity cost of capital, and the legal fees associated with structuring the ownership of the policy. In the current 2026 financial landscape, several core variables dictate the final price point.
Age and Mortality Risk
At this level of coverage, the actuarial risk is magnified. For a 35-year-old in peak health, a $660 million term policy might be relatively affordable because the statistical likelihood of a payout during a 10- or 20-year term is low. However, for a 60-year-old seeking permanent coverage to fund estate taxes, the premium will be exponentially higher. As the insured ages, the "Cost of Insurance" (COI) within the policy rises, reflecting the increased mortality risk.
Health and Lifestyle Underwriting
Carriers underwriting a $660 million risk will demand an exhaustive medical profile. This includes multiple physical exams, EKGs, cognitive screenings (for older applicants), and a review of five to ten years of medical records. Any significant health history—such as cardiovascular issues, past malignancies, or even high-risk hobbies like private aviation—can result in a "table rating," which adds a percentage-based surcharge to the base premium.
Policy Structure: Term vs. Permanent
- Term Life Insurance: This is the most cost-effective way to secure $660 million, but it is rarely used in isolation for such high amounts. It provides coverage for a set period (e.g., 10, 20, or 30 years). It is often used to cover specific, time-bound liabilities like a massive business loan or a short-term buy-sell agreement.
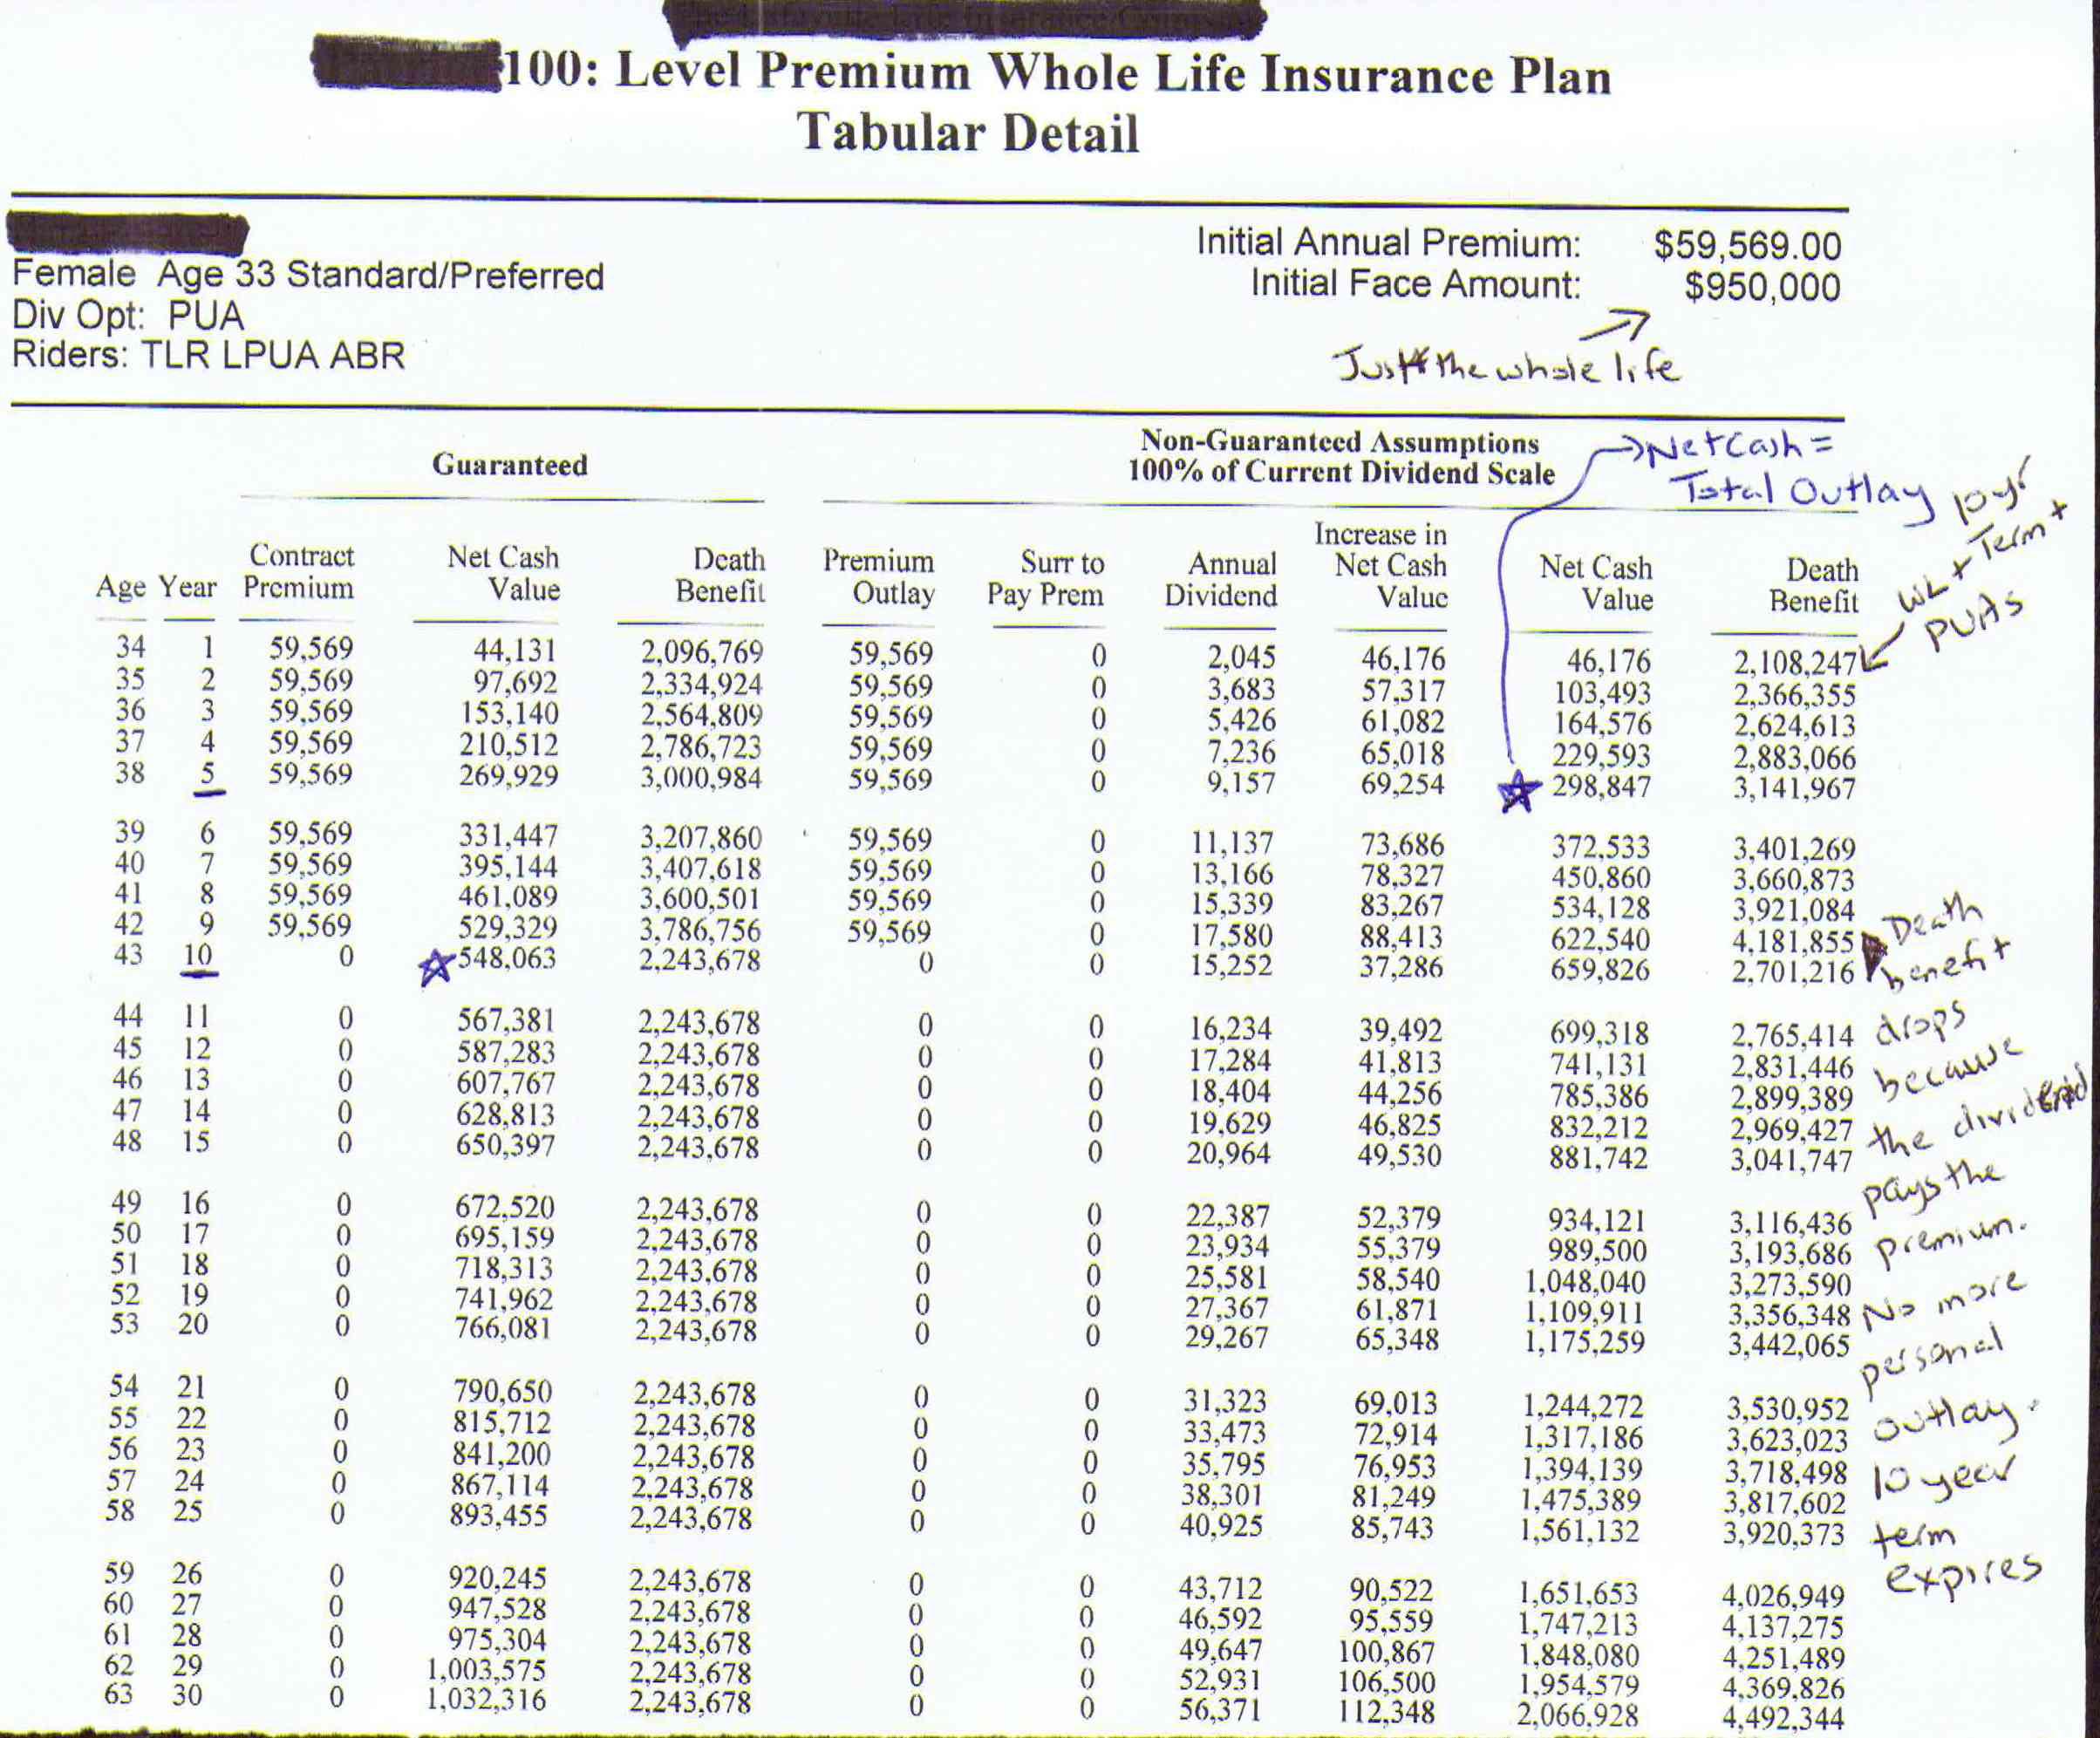
- Permanent Life Insurance (UL, VUL, PPLI): Most $660 million policies are permanent, designed to remain in force until death. Universal Life (UL) and Variable Universal Life (VUL) are common. For the ultra-wealthy, Private Placement Life Insurance (PPLI) is frequently the preferred vehicle, as it allows for customized investment options within the policy's cash value, often lowering the net cost over time through tax-efficient growth.
The Syndication Process: How the Risk is Distributed
No single insurance company—regardless of how large their balance sheet is—will keep a $660 million risk on their own books. This is due to "retention limits," which are the maximum amounts a company is willing to lose on a single life.
In 2026, most major carriers have a retention limit between $5 million and $30 million. To reach $660 million, the lead insurer must "syndicate" the risk. They act as the primary point of contact but cede portions of the risk to:
- Facultative Reinsurers: Companies like Swiss Re, Munich Re, or Berkshire Hathaway Specialty Insurance take on specific layers of the $660 million.
- Automatic Reinsurance Treaties: Existing agreements where the reinsurer automatically accepts a multiple of the lead carrier's retention.
- Other Primary Carriers: A "jumbo" case may be split among five or ten different insurance brands, each issuing a separate policy that adds up to the $660 million total.
This layering affects the cost because each reinsurer may have different pricing models and risk appetites. If the global reinsurance market is "tight," the premiums for a $660 million policy will rise across the board.
Financial Underwriting and Insurable Interest
To secure a $660 million policy, you must prove to the insurers that the "loss" of the insured life is actually worth $660 million. This is known as insurable interest. You cannot simply buy a policy of this size because you can afford it; there must be a financial justification.
Estate Tax Liability
The most common justification for a $660 million policy is the Federal Estate Tax. In 2026, the top federal estate tax rate remains 40%. For a family with a net worth of $1.65 billion, the tax bill upon death would be approximately $660 million. The policy provides the liquidity to pay the IRS without forcing the liquidation of closely held businesses, real estate, or other illiquid assets.
Key Person and Business Succession
If a CEO or founder is the primary driver of a multi-billion dollar corporation's value, the board may justify a $660 million policy to cover the anticipated drop in stock price, the cost of finding a successor, and the stabilization of credit lines during the transition.
Debt Protection
In rare cases, a $660 million policy is required to collateralize massive private loans or corporate debt structures. The lender requires the insurance to ensure the debt is retired if the principal guarantor passes away.
Estimated Annual Premium Costs for $660 Million
The following table provides estimated annual premiums based on 2026 market data. These figures assume a "Preferred Best" or "Super Preferred" health rating.
| Insured Age | Policy Type | Estimated Annual Premium (Low) | Estimated Annual Premium (High) |
|---|---|---|---|
| 35 (Male) | 20-Year Term | $1,320,000 | $2,100,000 |
| 45 (Male) | Guaranteed Universal Life | $5,800,000 | $8,500,000 |
| 55 (Male) | Guaranteed Universal Life | $10,500,000 | $14,200,000 |
| 65 (Male) | Whole Life / Permanent | $16,500,000 | $22,000,000 |
| 45 (Female) | Guaranteed Universal Life | $4,900,000 | $7,200,000 |
| 55 (Female) | Guaranteed Universal Life | $8,900,000 | $12,100,000 |
Note: Premiums for females are generally lower due to longer statistical life expectancy. Prices vary significantly based on the internal charges of the specific carrier and current interest rate environments.
Advanced Strategic Implementation: The ILIT
Because the goal of a $660 million policy is often to pay estate taxes, the policy itself must not be part of the taxable estate. If an individual owns a $660 million policy personally, the death benefit would be subject to the 40% estate tax, meaning only $396 million would remain after taxes.
To avoid this, advisors utilize an Irrevocable Life Insurance Trust (ILIT).
- Creation: The individual creates a trust and appoints a trustee.
- Funding: The individual gifts money to the trust (using lifetime gift exemptions or annual exclusions) to pay the premiums.
- Ownership: The ILIT applies for and owns the $660 million policy.
- Tax Neutrality: Because the individual does not own the policy and has no "incidents of ownership," the full $660 million death benefit passes to the beneficiaries (or the IRS on their behalf) federal income and estate tax-free.
Challenges in the $600M+ Market
Securing this volume of coverage is not a fast process. It typically takes four to nine months to complete the medical and financial underwriting and to secure the necessary reinsurance capacity.
Market Capacity Limits
There is a finite amount of life insurance "capacity" in the world for a single life. In 2026, the total "jumbo limit"—the maximum amount of insurance all companies combined will issue on one person—is generally around $150 million to $300 million for standard cases. Pushing to $660 million requires a specialized broker who can access global markets, including London (Lloyd’s) and Asian reinsurance hubs, to piece together the remaining capacity.
Regulatory Oversight
Under Internal Revenue Code Section 7702, a policy must meet specific cash-value-to-death-benefit ratios to be considered "life insurance." If a $660 million policy is funded too aggressively, it may be classified as a Modified Endowment Contract (MEC), which changes the tax treatment of loans and withdrawals.
Frequently Asked Questions
Can I buy a $660 million policy from one company?
No. While you may fill out one application with a lead carrier like Prudential, New York Life, or Northwestern Mutual, that company will share the risk with dozens of other reinsurers behind the scenes. Your contract will be with the lead carrier, but their ability to issue the policy depends entirely on the reinsurance syndicate.
What happens if I can't justify the $660 million amount?
If your financial records (tax returns, balance sheets, and estate valuations) only show a need for $200 million, the insurance companies will refuse to issue $660 million. They will "cap" your coverage at the amount of your documented financial loss or liability. This prevents "speculation" on human life.
Are the premiums for a $660 million policy tax-deductible?
Generally, no. Life insurance premiums paid by an individual or a trust are considered a personal expense and are not tax-deductible. If a corporation buys the policy on a key employee, the premiums are also typically not deductible under IRC Section 264.
Is a medical exam required for a policy of this size?
Yes, and it is exceptionally rigorous. It often includes a "senior inspection report," where a third-party investigator interviews your business associates and reviews your lifestyle. You will likely need to provide several years of audited financial statements to verify your net worth.
Can PPLI reduce the cost of a $660 million policy?
Private Placement Life Insurance (PPLI) can significantly reduce the long-term cost. Unlike retail policies with high commissions and administrative fees, PPLI has a "low-load" structure. The cash value can be invested in hedge funds or private equity, and the growth is tax-deferred. Over 20 or 30 years, the investment gains within the policy can effectively "pay for" the death benefit.
Recommended Next Actions
If you are pursuing a $660 million life insurance policy, the first step is to assemble a team consisting of a specialized high-limit insurance broker, an estate tax attorney, and a tax accountant. Do not apply to multiple carriers simultaneously; doing so can create "red flags" in the MIB (Medical Information Bureau) database and may cause reinsurers to reduce their offered capacity.
Instead, work with a lead broker to perform an "informal inquiry." This allows your team to shop your medical and financial profile to reinsurers anonymously to gauge pricing and capacity before a formal application is ever signed. This strategy preserves your standing in the market and ensures you receive the most competitive premium rates available in 2026.
Image Gallery
Select an image to open it in a new tab.


Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
