How to Build an Effective Corporate Credit Card Policy
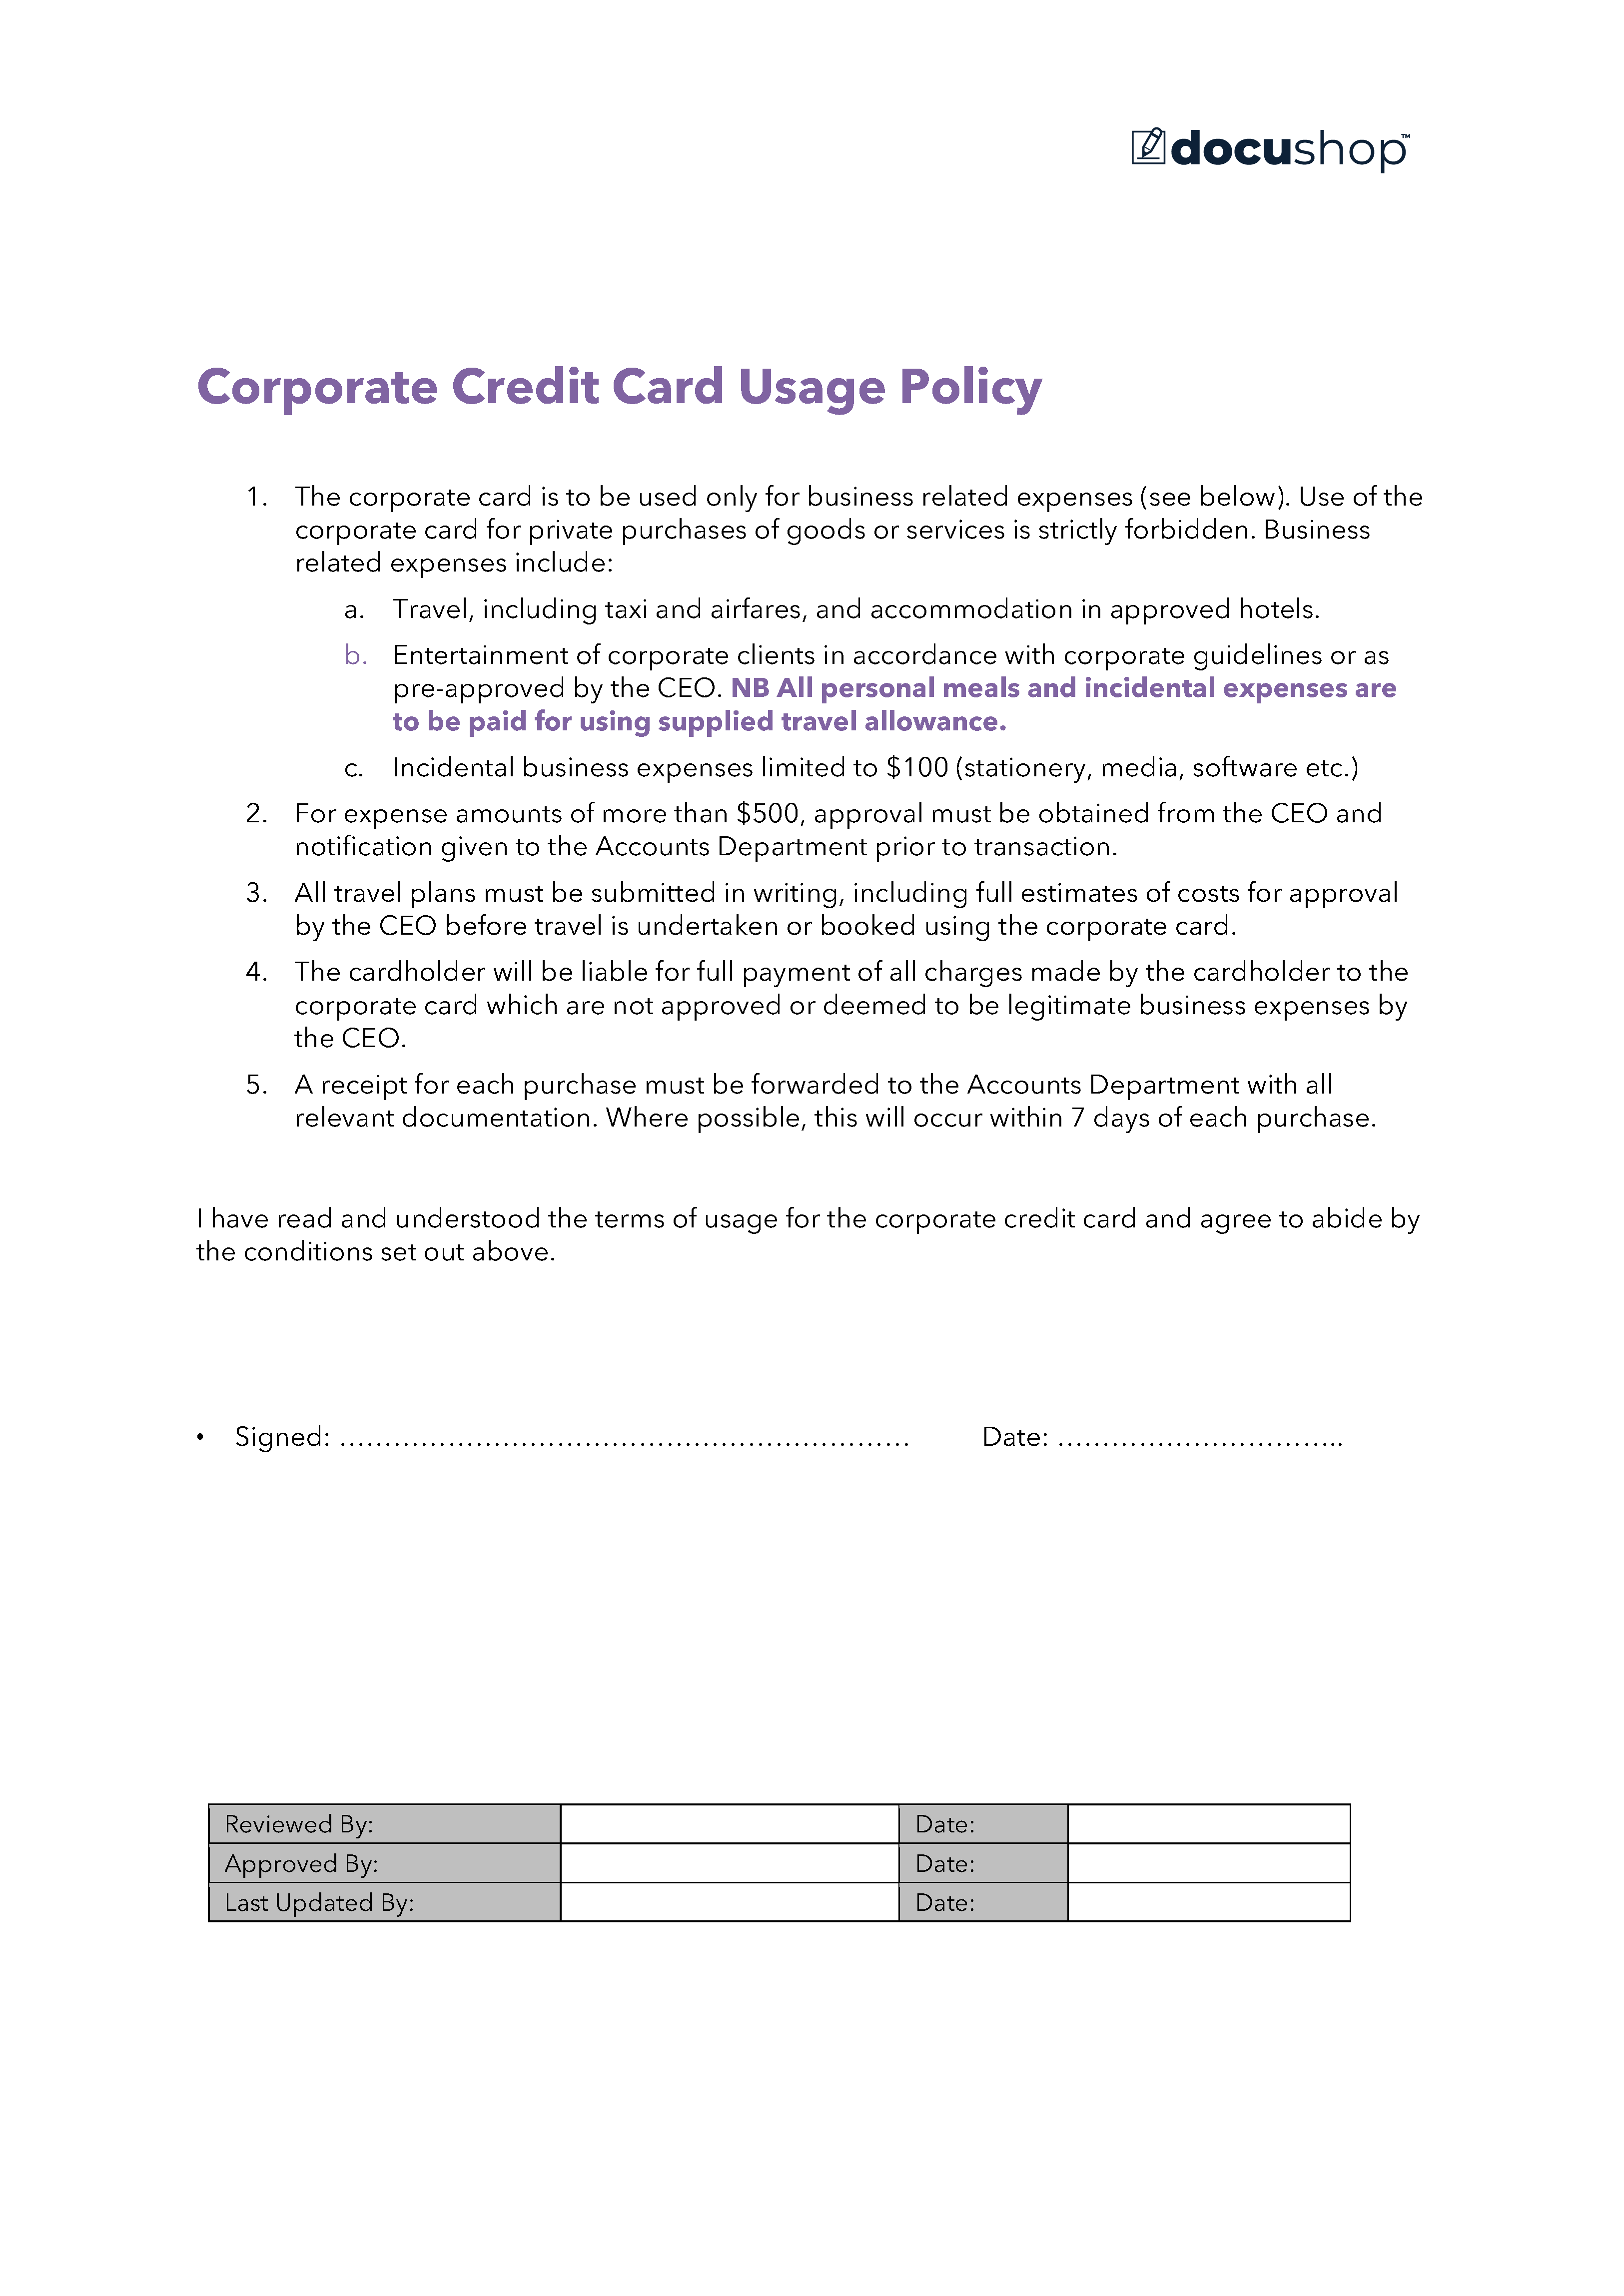
Building an effective corporate credit card policy requires establishing clear spending limits, defined categories, rigorous receipt submission workflows, and strict enforcement mechanisms to prevent fraud and misuse while empowering employees to conduct legitimate business expenses efficiently.
Implementing a corporate credit card program provides organizations with substantial advantages, including consolidated expense reporting, streamlined vendor payments, potential cash-back rewards, and optimized cash flow management. However, unmonitored plastic can quickly translate into disorganized finances, unnecessary expenditures, and severe compliance or tax risks. To capture the benefits of company-issued credit cards without suffering the pitfalls of financial leakage, finance leaders, operations managers, and business owners must draft, distribute, and enforce a robust corporate credit card policy.
Navigating the nuances of modern corporate spend management requires balancing employee trust with rigorous corporate governance. Whether your organization is issuing its first batch of business credit cards or overhauling an existing legacy framework, this guide outlines the operational steps, security considerations, and enforcement mechanisms needed to build a sustainable, transparent, and comprehensive corporate credit card policy.
Understanding the Purpose and Scope of a Corporate Credit Card Policy
A corporate credit card policy is a formal document that dictates who is eligible to receive a company credit card, what expenses are acceptable, how transactions must be documented, and what consequences follow policy violations. Without this foundational framework, employees are left to guess what constitutes an acceptable business meal, how much to tip, or whether they can book premium travel accommodations.
The scope of the policy should explicitly define the target audience. Does the policy apply to all full-time employees, only members of the executive team, or specific department heads who frequently travel? Clarifying eligibility prevents entitlement expectations and ensures that credit limits are distributed based strictly on business necessity rather than corporate hierarchy alone.
Furthermore, a well-structured policy mitigates organizational risk. In the event of an internal audit, tax inspection, or fraudulent activity, a documented policy acts as your primary legal and operational defense. It establishes clear lines of accountability, ensuring that unauthorized purchases are treated as direct policy breaches rather than ambiguous gray areas.
Core Elements of an Acceptable Use Framework
The backbone of any corporate credit card policy is the "Acceptable Use" section. This component leaves no room for interpretation regarding what the company will and will not pay for. Setting precise boundaries prevents awkward conversations between finance teams and employees down the line.
Permitted Business Expenses
Permissible expenses generally align with standard operational needs required to perform job duties. These typically include:
- Business Travel: Flights, hotel accommodations, rental cars, and rideshare services booked within company-approved booking tools or guidelines.
- Client Entertainment: Meals, coffee meetings, or events directly tied to business development, client retention, or prospective partnership discussions.
- Software and Subscriptions: One-off software licenses, digital tool subscriptions, or cloud services pre-approved by the IT or finance department.
- Office and Operational Supplies: Emergency purchases of office supplies, hardware components, or materials needed immediately when standard procurement channels are unavailable.
Strictly Prohibited Expenses
Equally important is a definitive list of non-reimbursable, strictly prohibited expenditures. Attempting to charge these items to a corporate card usually triggers immediate flags and disciplinary action. Prohibited items include:
- Personal Purchases: Groceries, personal clothing, household goods, or family entertainment.
- Fines and Penalties: Parking tickets, speeding tickets, or legal fees incurred due to personal negligence or traffic violations while traveling for business.
- Cash Advances: Withdrawing physical cash from an ATM using a corporate credit card, which frequently incurs exorbitant interest rates and is notoriously difficult to track.
- Unauthorized Luxury Upgrades: First-class flight upgrades, premium hotel suites, or high-end spa treatments unless specifically cleared in writing by an executive for a unique business justification.
Establishing Spending Limits and Approval Hierarchies
Financial governance relies heavily on structural constraints. Giving every employee an open-ended credit limit is a recipe for fiscal disaster. Instead, organizations must implement tiered spending limits and approval hierarchies tailored to specific roles and departments.
| Role / Department | Typical Monthly Credit Limit | Single Transaction Limit | Special Approval Requirements |
|---|---|---|---|
| Standard Employee / Individual Contributor | $1,000 – $2,500 | $250 – $500 | Manager approval for all non-travel expenses |
| Sales / Field Representative | $5,000 – $10,000 | $1,000 – $2,000 | Pre-approval required for client events over $500 |
| Department Head / Director | $10,000 – $25,000 | $2,500 – $5,000 | Executive sign-off for out-of-budget software |
| Executive Leadership | $25,000 – $50,000+ | $10,000+ | Annual board or finance committee review |
Implementing these limits is significantly easier today thanks to modern spend management software and corporate card platforms. Administrators can program dynamic rules directly into the card software, setting hard merchant category code (MCC) blocks—such as blocking gambling, adult entertainment, or jewelry stores—while automatically declining transactions that exceed single-swipe or monthly thresholds.
Receipt Management and Expense Reporting Workflows
A card policy is only as effective as its reconciliation workflow. Even with strict spending limits, corporate cards generate administrative chaos if receipts are missing, categorized incorrectly, or submitted months after the transaction occurred.
To maintain clean books, your policy must outline explicit deadlines and submission requirements:
- Digital Receipt Capture: Mandate that physical receipts be photographed and uploaded immediately using mobile expense management applications. Relying on paper receipts stuffed into wallets inevitably leads to lost documentation.
- Itemized Receipts: Clarify that credit card slips showing only the total amount are insufficient for accounting and tax purposes. Employees must submit fully itemized receipts displaying every purchased item, taxes paid, and tip amounts.
- Strict Timelines: Establish a hard deadline for expense report submissions, such as within five business days of month-end or within 48 hours of returning from a business trip. Delayed submissions disrupt cash flow forecasting and month-end close procedures.
- Mandatory Memos: Require a brief business justification note for every transaction, naming the attendees present for business meals or detailing the project associated with software purchases.
Security, Fraud Prevention, and Lost Card Protocols
Corporate cards represent a primary target for external fraudsters and internal misuse. Protecting the organization requires clear security protocols integrated directly into daily habits and policy text.
Employees must treat corporate cards with the same security consciousness as their personal banking instruments. Cards should never be left unattended in hotel rooms, visible in parked vehicles, or shared with colleagues. If a card is physically lost, stolen, or suspected of being compromised, the policy must explicitly state that the employee is required to report the incident immediately to both the card issuer and the internal finance team to freeze the account.
Furthermore, sharing card numbers via insecure channels—such as unsecured email, text messaging, or messaging apps—must be strictly forbidden. When recurring subscriptions or software tools require shared billing credentials, organizations should use virtual card numbers (VCNs) assigned to specific vendors with locked limits rather than physical plastic cards.
Enforcement, Auditing, and Consequences for Non-Compliance
A policy without teeth is merely a suggestion. For a corporate credit card policy to work, violations must carry predictable, standardized consequences enforced uniformly across all levels of the organization—from entry-level staff to C-suite executives.
Routine Audits
The finance team should conduct random audits of monthly expense reports, checking transaction patterns against submitted receipts and business justifications. Modern corporate card platforms often use automated anomaly detection to flag unusual spending hours, duplicate charges, or suspicious merchant categories instantly, drastically reducing manual review times.
Tiered Disciplinary Actions
When violations occur, responses should follow a transparent, progressive disciplinary structure:
- First Offense (Minor/Administrative): A polite reminder from the finance team accompanied by a request to correct the receipt or provide missing documentation within 24 hours.
- Second Offense or Moderate Violation: Temporary suspension of the corporate credit card privileges, requiring the employee to use personal funds and submit traditional reimbursement claims.
- Severe or Willful Violation: Permanent revocation of the corporate card, formal reprimand placed in the employee's personnel file, mandatory repayment of unauthorized charges, and potential termination of employment for fraud or gross negligence.
Best Practices for Launching and Maintaining the Policy
Rolling out a new corporate credit card policy requires careful change management to ensure adoption without alienating staff.
Begin by hosting an internal training session or distributing a comprehensive FAQ document that highlights why the policy exists—framing it not as an administrative hurdle, but as a tool to protect company resources and ensure smooth, hassle-free expense reimbursements for traveling employees.
Finally, treat the policy as a living document. Review your corporate credit card guidelines annually in collaboration with HR, legal, and finance leaders. As software platforms evolve, tax regulations shift, and company size scales, your policy must adapt to remain effective, modern, and aligned with organizational objectives.
Frequently Asked Questions
What should an employee do if they accidentally use a corporate credit card for a personal purchase?
If an accidental personal charge occurs, the employee must notify the finance department immediately upon noticing the error. They should provide a clear written explanation and reimburse the company directly—either via personal check, payroll deduction, or cash transfer—before the monthly expense report close date. Swift transparency prevents accidental charges from being misconstrued as intentional policy violations.
Are employees personally liable for unauthorized corporate card charges?
Generally, liability depends on the type of card program and the circumstances of the charge. Under true corporate liability cards issued directly to the company, the organization holds financial responsibility, though internal disciplinary action applies if the employee acted negligently. For individual liability corporate cards, where the employee's personal credit score is tied to the account, the employee is technically responsible for paying the bill and seeking reimbursement, making strict policy adherence even more critical.
How do you handle meal expenses when clients are present versus traveling alone?
Corporate policies typically set separate per diem limits or daily maximums for solo travel meals compared to client-hosted meals. When clients are present, the policy should require the employee to list the names, titles, and company affiliations of all attendees on the expense report to satisfy tax deduction compliance rules and substantiate the business purpose of the entertainment expense.
Can corporate credit cards be used to book personal travel and later separate the charges?
No. Mixing personal and business travel expenses on a corporate card—even with the intention of paying back the personal portion later—creates complex accounting errors, tax compliance risks, and auditing vulnerabilities. All travel booked on a corporate card must be strictly for business use. Personal extensions (such as staying an extra weekend after a business conference) must be booked and paid for using personal funds.
What are Merchant Category Codes (MCCs), and why do they matter for card policies?
Merchant Category Codes are four-digit numbers assigned to businesses by payment networks (such as Visa or Mastercard) to classify the type of goods or services they provide. Spend management software uses MCCs to automatically block corporate cards from being used at restricted merchant types—such as bars, casinos, or digital currency exchanges—preventing unauthorized spending before it happens rather than catching it after the fact.
Next Actions
To turn these guidelines into an operational reality, assemble a cross-functional team consisting of representatives from finance, human resources, and operations. Audit your current expense data to identify historical pain points, select a modern spend management software provider that supports granular MCC blocking and digital receipt capture, draft your finalized policy document using clear and definitive language, and schedule mandatory training sessions for all cardholders prior to your next fiscal quarter.
Image Gallery
Select an image to open it in a new tab.



Simon Caldwell
Enterprise Technology and Systems Editor
