Finding the Best Insurance for Tulsa Auto Coverage: A Comprehensive Guide
Securing the best auto insurance in Tulsa requires balancing Oklahoma’s state-mandated minimum liability requirements with the specific risks of urban driving, including high theft rates and unpredictable weather patterns. Evaluating coverage options involves comparing provider stability, local claims satisfaction, and personalized premium factors like your driving record, vehicle safety features, and chosen deductible levels.
Understanding Oklahoma’s Mandatory Auto Insurance Laws
Before selecting a policy, it is essential to understand the legal floor for insurance in Oklahoma. The Oklahoma Department of Public Safety mandates that all motorists carry liability insurance to operate a vehicle legally on public roads. As of 2026, the minimum liability coverage required is commonly referred to as the 25/50/25 rule.
This means your policy must provide at least:
- $25,000 for bodily injury or death of one person in an accident caused by the owner of the insured vehicle.
- $50,000 for total bodily injury or death of two or more people in an accident.
- $25,000 for property damage per accident.
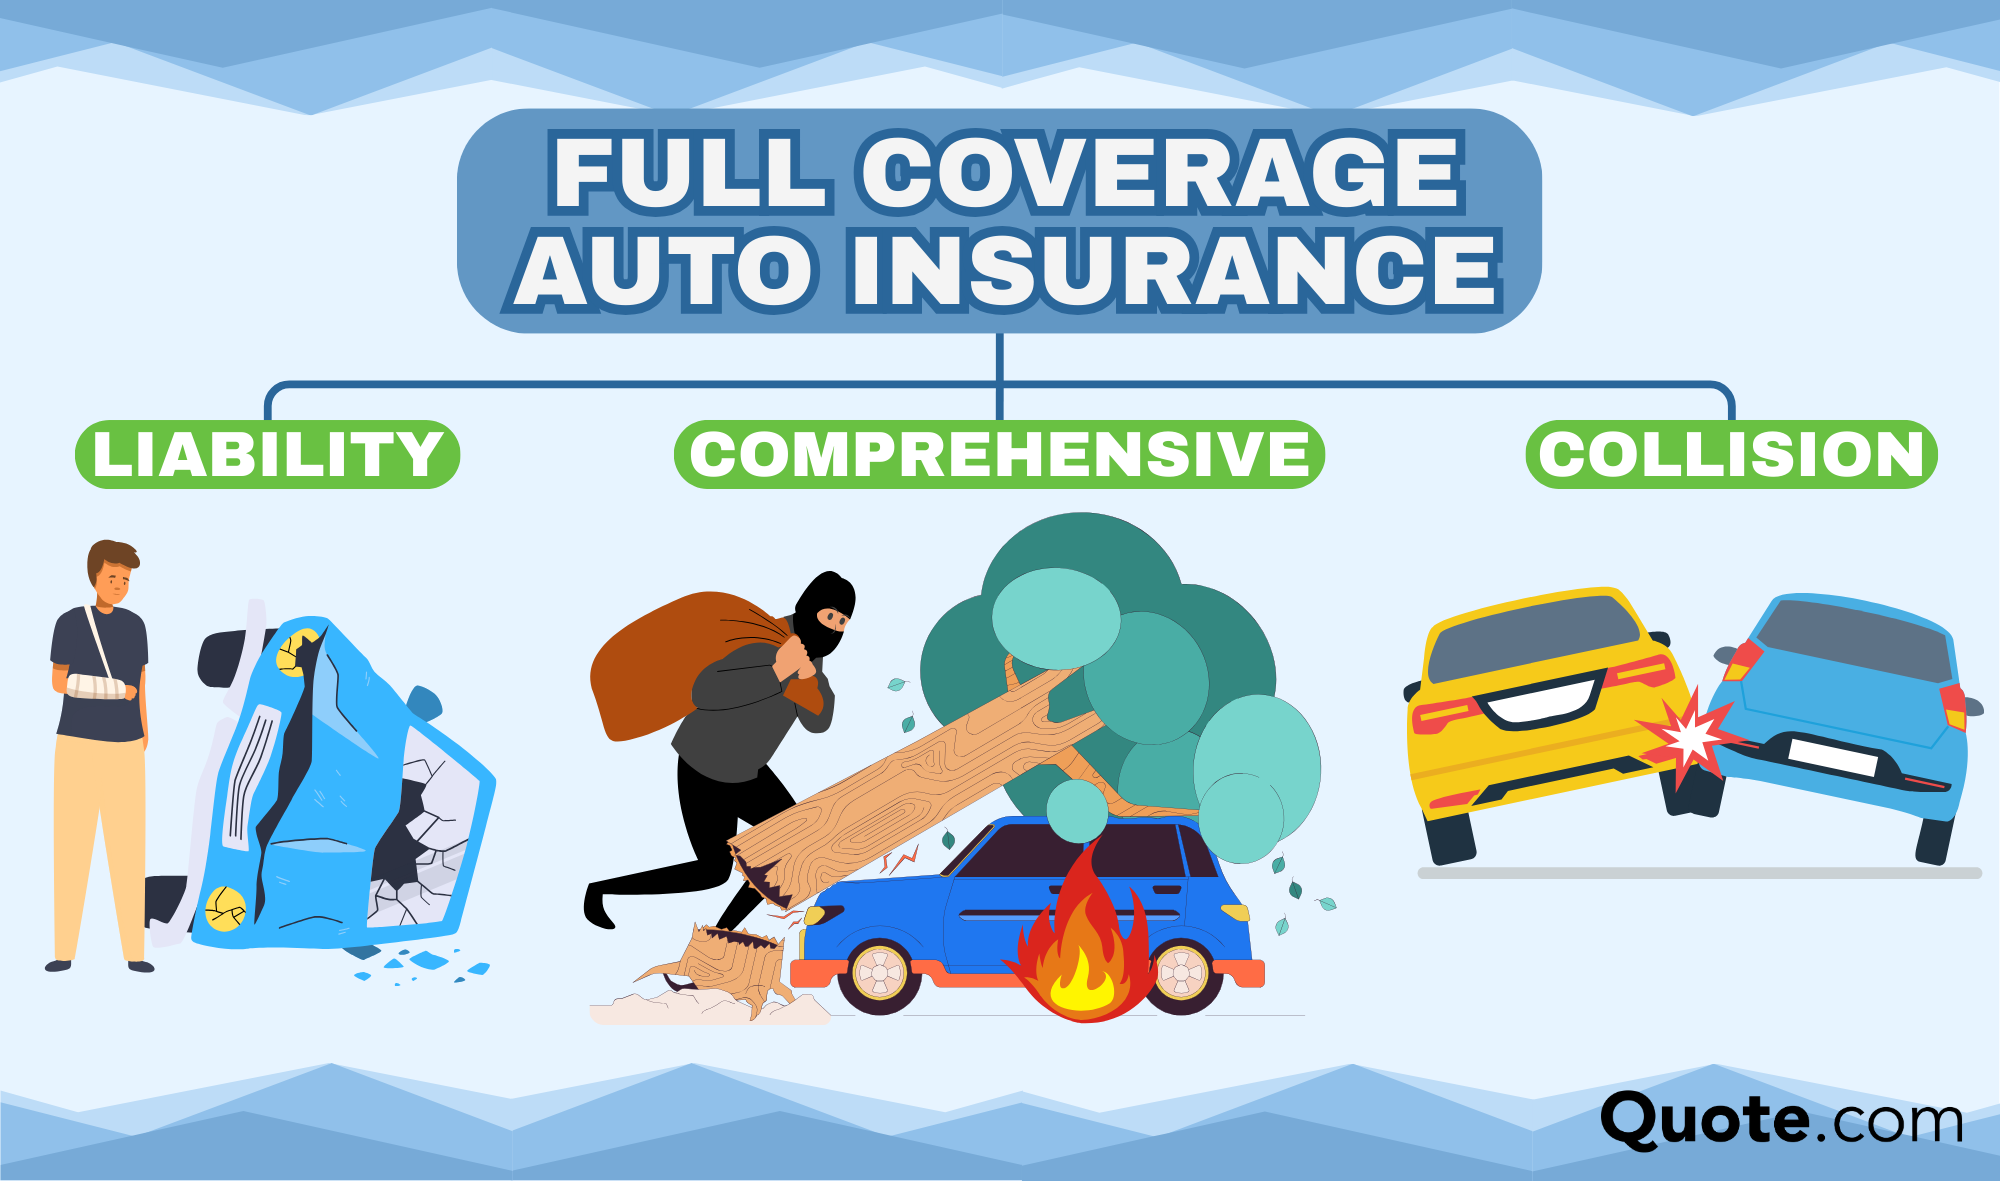
While these minimums satisfy the legal requirement for vehicle registration and license maintenance, they are frequently insufficient to cover the costs of a major accident. If you are found at fault in a collision where damages exceed these limits, you are personally liable for the remaining balance. Therefore, when searching for the "best" coverage, most experts recommend "full coverage"—which adds comprehensive and collision protection—to safeguard your personal assets.
Assessing Tulsa-Specific Risk Factors
Tulsa presents unique challenges that influence how insurance companies calculate premiums for the region. Unlike rural Oklahoma, Tulsa's metropolitan environment increases the frequency of minor traffic incidents and higher rates of vehicle theft or vandalism.
Furthermore, Tulsa is prone to severe weather, including hail and windstorms. Comprehensive coverage is a critical component of any "best" insurance policy in this area because it protects your vehicle against non-collision events, such as broken windshields from hail or damage from downed trees during severe weather cycles. If you reside in areas of Tulsa with higher traffic density, you should also consider Uninsured/Underinsured Motorist (UM/UIM) coverage, which protects you if you are hit by a driver who lacks sufficient insurance to cover your medical bills or repair costs.

Evaluating Insurance Providers: What Matters Most?
When comparing insurers, the lowest monthly premium is often a poor metric for "best." Instead, look for a balance between financial stability, mobile app utility, and claims processing speed.
Financial Strength and Claims Satisfaction
Large, national carriers often have the infrastructure to provide 24/7 claims support and sophisticated mobile applications that allow you to file a claim, upload photos of damage, and track repairs in real-time. Conversely, smaller, regional mutual insurance companies may offer more personalized service and local agent availability, which can be invaluable when navigating the aftermath of a specific Tulsa-based incident.
The Role of Independent Agents
Many residents in Tulsa prefer working with independent insurance brokers. An independent agent does not represent a single insurance company; instead, they represent multiple carriers. This allows the agent to pull quotes from several companies simultaneously, tailoring a policy that fits your specific budget and coverage needs. This is particularly useful for drivers with unique situations, such as those with a minor blemish on their driving record or those insuring specialized or high-value vehicles.
Comparing Coverage Options
To help visualize the difference between basic state compliance and a robust safety net, use the following comparison table.
| Coverage Type | What It Protects | Recommended For |
|---|---|---|
| Liability Only | Legal compliance; damages you cause to others. | Older vehicles with low market value. |
| Full Coverage | Liability plus damage to your own vehicle. | Newer vehicles or those with active loans. |
| Gap Insurance | The difference between your loan balance and car value. | New car buyers or those with small down payments. |
| UM/UIM Coverage | Your medical/repair costs from underinsured drivers. | All Tulsa drivers; high-traffic area commuters. |
| Comprehensive | Theft, vandalism, hail, fire, and animal collisions. | All Tulsa drivers due to weather/crime risks. |
Steps to Secure Your Policy
- Gather Necessary Documentation: Before requesting quotes, have your Vehicle Identification Number (VIN), current driver’s license, and an accurate estimate of your annual mileage ready.
- Verify Driving History: Obtain a copy of your Motor Vehicle Report (MVR). Insurance companies will pull this data, and knowing what they see prevents surprises regarding premium surcharges.
- Request Multiple Quotes: Obtain at least three quotes from different types of providers—one national brand, one regional provider, and one through an independent agent.
- Review the Declaration Page: Once you have selected a policy, read the "Declarations Page." This summarizes your coverage limits, deductibles, and any exclusions. Never assume "full coverage" implies coverage for every possible scenario.
- Check for Discounts: Inquire about specific discounts available in Oklahoma, such as defensive driving course credits, multi-policy (bundling) discounts for home or renters insurance, and telematics programs that track safe driving habits.
Troubleshooting Common Issues
If you find that your premiums are significantly higher than the average, investigate potential causes rather than simply accepting the cost.
- Credit-Based Insurance Scores: In Oklahoma, insurers are permitted to use credit-based insurance scores to determine pricing. If your score has recently improved, contact your agent to request a re-rating of your policy.
- Correction of Errors: Occasionally, MVRs contain errors, such as an incorrectly reported accident or a moving violation that was later dismissed. Disputing these with the Department of Public Safety can lead to a lower premium if the correction is verified.
- Vehicle Classification: Ensure your vehicle is properly classified. Sometimes, a high-safety-rating vehicle may be misclassified, leading to higher rates. Verify your vehicle’s make and model codes with your provider.
Frequently Asked Questions
Is "no-fault" insurance available in Tulsa?
No. Oklahoma is a "tort" state, which means the person who causes an accident is responsible for the damages. This is why liability insurance—and having sufficient coverage—is so important for your financial protection.
How does my credit score affect my Tulsa auto insurance?
Oklahoma insurers often use credit-based insurance scores to predict the likelihood of a claim. Higher credit scores generally correlate with lower premiums, while poor scores may lead to higher rates. If you have a low score, focus on consistent payment history to potentially lower your future premiums.
Should I choose a higher or lower deductible?
A higher deductible lowers your monthly premium but requires you to pay more out-of-pocket if you file a claim. If you have a healthy emergency fund, a higher deductible (e.g., $1,000) is often a strategic way to save money on annual insurance costs. If you lack liquid savings, a lower deductible (e.g., $500) is safer.
Are there specific discounts for Tulsa drivers?
Yes. Many carriers offer "telematics" programs—apps that track your braking, speed, and time of day you drive. If you are a safe driver, these programs can offer significant discounts. Additionally, bundling your home and auto insurance with the same provider is consistently one of the best ways to reduce total insurance costs in Oklahoma.
How often should I review my coverage?
You should review your insurance coverage at least once every twelve months or whenever you experience a major life event, such as moving, getting married, or purchasing a new vehicle. Over time, your vehicle’s value depreciates, and you may be able to reduce your comprehensive or collision premiums as the car ages.
Final Recommendation
To find the best insurance for your needs, start by evaluating your vehicle’s current market value and your financial ability to absorb an unexpected loss. If your car is worth less than $5,000, consider whether the cost of full coverage outweighs the potential payout in a total-loss scenario. If you have a newer vehicle, prioritize high liability limits and consistent comprehensive protection to mitigate Tulsa’s specific environmental risks. Ultimately, obtain quotes through multiple channels, verify your driving record for accuracy, and look for a carrier that offers responsive local claims support, as the true value of insurance is found when you need to file a claim.
Image Gallery
Select an image to open it in a new tab.



Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
