Digital Transformation in Life and Retirement: The Role of Howden Life and Health Software Systems
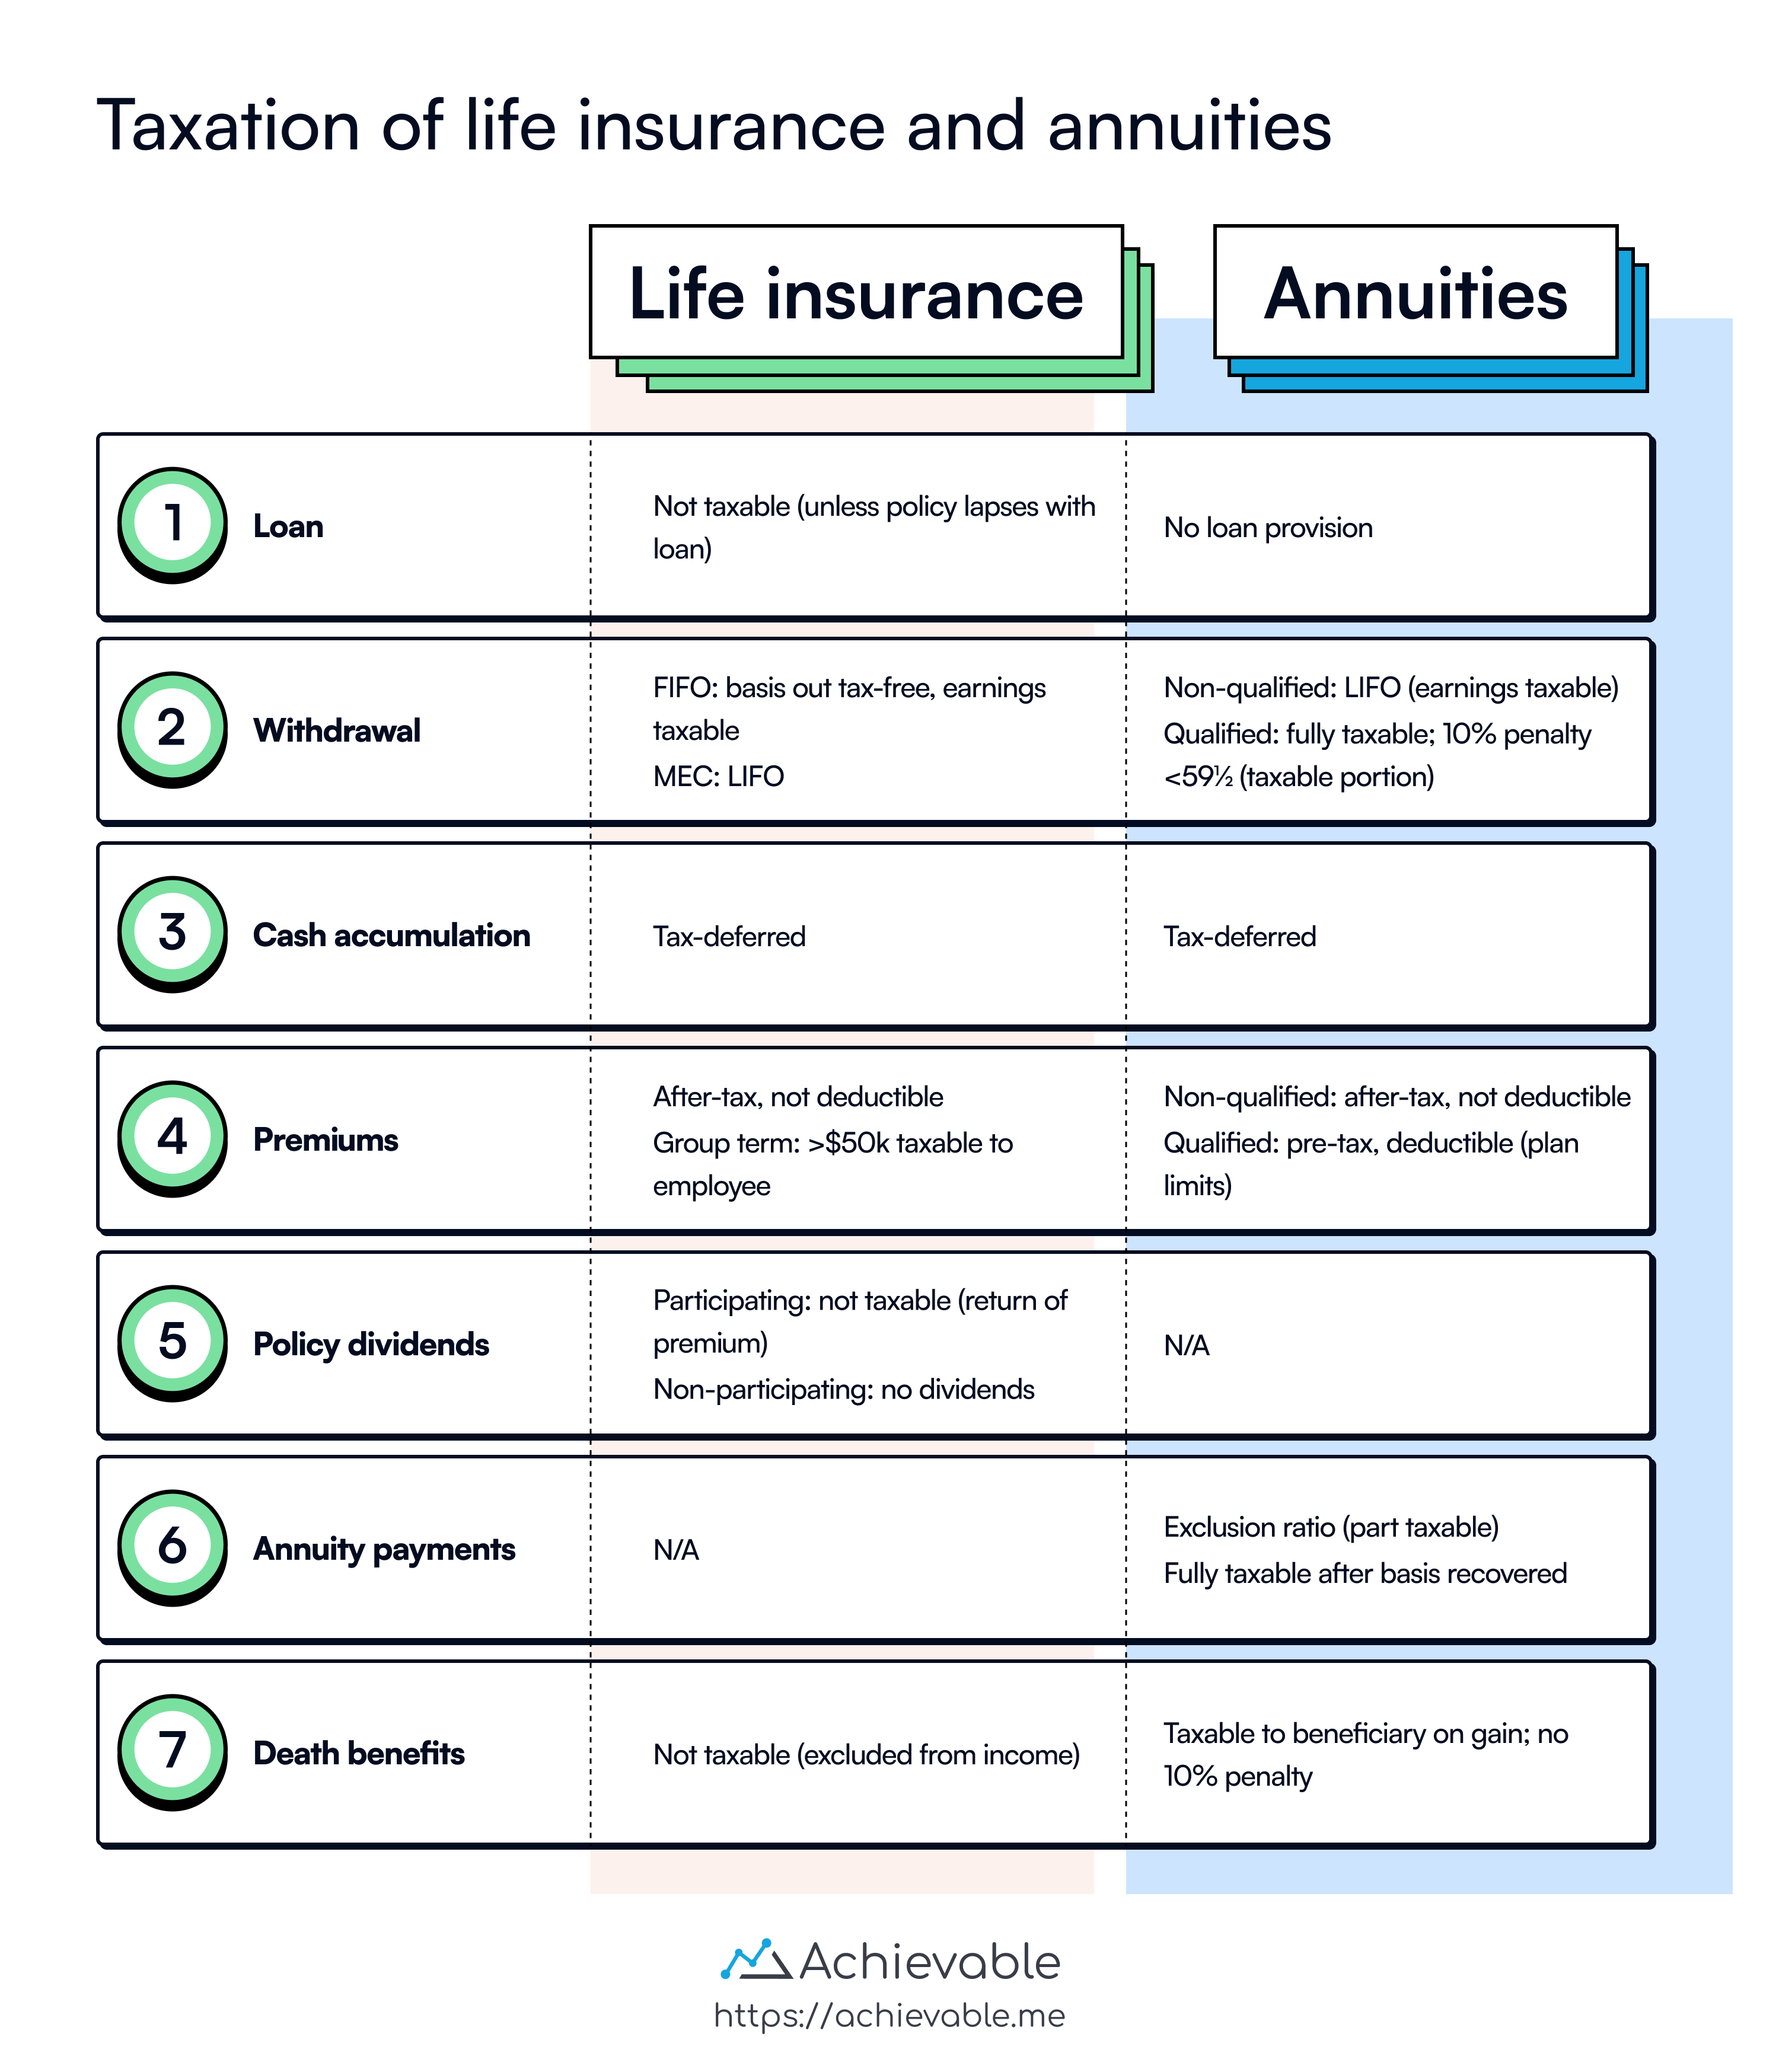
Howden Life and Health utilizes a sophisticated suite of insurance software designed to streamline the administration, underwriting, and distribution of life, annuity, and retirement products. These integrated platforms enable real-time quoting, automated risk assessment, and comprehensive policy management, ensuring that brokers and clients benefit from data-driven financial planning and regulatory compliance in the evolving 2026 landscape.
The insurance sector has moved beyond legacy systems, shifting toward agile, cloud-based architectures that prioritize the user experience and data integrity. As a major player in the global brokerage space, Howden Life and Health has invested heavily in proprietary and third-party software integrations to manage the complexities of long-term financial instruments. To understand the impact of this technology, one must examine the specific functionalities that support life insurance, annuities, and retirement planning.
The Architecture of Modern Life and Health Insurance Platforms
The software ecosystem employed by Howden Life and Health is not a single application but a modular framework. In 2026, these systems are characterized by "headless" architectures—where the back-end logic is separated from the front-end user interface—allowing for seamless updates and high levels of customization.
Policy Administration Systems (PAS)
At the core of the operation is the Policy Administration System. This software handles the entire lifecycle of an insurance policy, from the initial application to the final claim or maturity. For life insurance, the PAS must manage decades of data, tracking premium payments, beneficiary changes, and policy loans. In the context of Howden's operations, the software integrates with central databases to ensure that client records are updated across all jurisdictions, maintaining a "single source of truth."
Automated Underwriting Engines
One of the most significant advancements in life and health software is the transition from manual to automated underwriting. These engines use complex algorithms and machine learning models to analyze medical data, lifestyle choices, and financial history. By 2026, these systems have become capable of processing "fluidless" applications, where low-risk individuals can receive a policy offer in minutes rather than weeks, based on digital health records and predictive modeling.
Specialized Software for Annuities and Retirement Planning
Annuities and retirement products require a different technical approach than standard term life insurance. These products are investment-linked and involve long-term payout phases, necessitating robust actuarial calculation engines.
Actuarial and Payout Modeling
Software dedicated to annuities must perform millions of calculations to determine payout rates based on mortality tables, interest rate projections, and inflation hedging. Howden’s retirement software modules allow advisors to run "what-if" scenarios for clients. For instance, a client can see how a market downturn might affect their drawdown strategy or how an enhanced annuity might provide higher income based on specific health conditions.
Drawdown Management Tools
As more retirees opt for flexible access to their pensions rather than fixed annuities, software for "income drawdown" has become essential. These tools track the remaining fund value, monitor withdrawal rates to prevent "sequencing risk" (the risk of receiving lower returns early in retirement), and automate the tax reporting requirements associated with pension withdrawals.

Integration and API Connectivity
A defining feature of Howden Life and Health’s software strategy is its reliance on Application Programming Interfaces (APIs). In 2026, software is only as good as its ability to communicate with other platforms.
- Aggregator Integration: Software connects directly to price comparison websites and broker portals, ensuring that Howden’s products are visible and accurately priced in real-time.
- Reinsurance Portals: For high-value life policies, the software shares anonymized data with reinsurers to secure capacity and spread risk instantly.
- Client Portals and Apps: The "front-end" of the software is often a mobile app or a secure web portal where policyholders can view their retirement projections, download tax certificates, or update their address without calling a help desk.
Data Security and Regulatory Compliance in 2026
Given the sensitivity of health and financial data, the software used by Howden must adhere to stringent global standards. In the UK and Europe, this involves strict compliance with GDPR and the Financial Conduct Authority’s (FCA) "Consumer Duty" rules.
Encryption and Identity Management
Modern insurance software utilizes zero-trust architecture. Every access request, whether from a broker or a client, is verified through multi-factor authentication (MFA) and biometric checks. Data is encrypted both "at rest" (stored in databases) and "in transit" (moving between the server and the user’s device).
Audit Trails and Transparency
Regulatory bodies require that insurance companies explain how they arrived at a premium or why a claim was denied. The software maintains a comprehensive audit trail, logging every data point used in the decision-making process. This transparency is crucial for the "Right to Explanation" clauses found in modern data protection laws, ensuring that AI-driven decisions are not "black boxes."
Technical Specifications and Comparative Features
The following table outlines the functional differences between the primary software modules used within the life and retirement sectors at Howden.
| Feature | Life Insurance Module | Annuity Management Module | Retirement Planning Tool |
|---|---|---|---|
| Primary Goal | Risk protection and death benefit | Guaranteed lifetime income | Asset accumulation and drawdown |
| Calculation Logic | Mortality-based risk pricing | Actuarial present value | Stochastic market modeling |
| Data Requirements | Medical history, family health | Age, fund size, health status | Contribution history, risk appetite |
| Update Frequency | Annual review or life event | Monthly/Quarterly payouts | Real-time market valuation |
| Regulatory Focus | Underwriting fairness | Solvency II / Capital reserves | Suitability and "Best Interest" |
The Impact of Artificial Intelligence on Insurance Software
By 2026, AI is no longer a peripheral feature; it is embedded in the software’s DNA. For Howden Life and Health, AI serves several practical purposes:
- Predictive Analytics for Customer Retention: The software identifies patterns that suggest a client might be about to cancel their policy (e.g., missed payments or decreased portal logins) and alerts a broker to intervene with a better offer or a policy review.
- Claims Fraud Detection: AI scans life and health claims for anomalies that might indicate fraud, such as conflicting medical reports or suspicious timelines, protecting the premium pool for honest policyholders.
- Hyper-Personalization: Instead of generic "off-the-shelf" products, the software uses data to build "segments of one," where a retirement plan is tailored specifically to a client’s unique spending habits and longevity expectations.
Implementation Challenges and Professional Guidance
Deploying and maintaining insurance software of this scale is a massive undertaking. Organizations often face hurdles regarding "legacy debt"—older systems that do not speak the same language as modern cloud applications.
Data Migration
The most complex task is moving decades of policyholder data from old mainframes to the cloud. This requires rigorous data cleansing to ensure that an annuity purchased in 1995 remains accurately represented in the 2026 digital interface.
User Adoption
Brokers and advisors must be trained to use these tools effectively. While the software can automate the "drudge work," the human element remains vital for interpreting complex retirement needs and providing empathetic advice during life insurance claims.
Disclaimer: Financial planning and insurance involve significant long-term commitments. Software-generated projections are estimates and not guarantees of future performance. Always consult with a qualified financial advisor regarding specific policy terms and tax implications.
Frequently Asked Questions
How do I access my Howden Life and Health policy through the software?
Clients typically access their policies via a dedicated secure portal or mobile application provided by Howden. You will need your policy number and verified identity credentials. Once logged in, the software provides a dashboard showing your current coverage, fund values (for retirement products), and a secure messaging system to contact your broker.
Is the software used by Howden compatible with third-party financial apps?
In many cases, yes. Through "Open Finance" initiatives and secure APIs, Howden’s software can often export data to personal finance management apps or tax software. This allows you to see your insurance and retirement assets alongside your daily banking data, provided you have granted explicit permission for such data sharing.
How does the software handle health data for life insurance applications?
Howden uses encrypted gateways to receive data from medical professionals and diagnostic labs. The software is designed to minimize the data collected, adhering to the "data minimization" principle. This means it only processes information strictly necessary for underwriting your specific policy, and this data is siloed from other parts of the organization.
Can the retirement software predict exactly how much money I will have at 65?
No software can predict the future with 100% certainty due to market volatility and changing tax laws. However, the software uses "Monte Carlo simulations" to run thousands of potential market scenarios, providing you with a probability range. This helps you understand the likelihood of reaching your financial goals rather than giving you a single, potentially misleading figure.
What happens if the software makes a mistake in my annuity calculation?
All insurance software is subject to rigorous "UAT" (User Acceptance Testing) and regular audits by actuarial teams. If a discrepancy is found, the audit trail functionality allows the firm to trace the error back to its source. Under FCA guidelines, firms are required to have robust "back-testing" and error-correction protocols to ensure policyholders are not financially disadvantaged by technical glitches.
Recommendations for Moving Forward
For those interacting with Howden Life and Health or similar high-tech brokerages, the following steps are recommended to maximize the benefits of their software systems:
- Complete Your Digital Profile: Ensure your contact details and "Expression of Wish" (beneficiary) forms are updated within the portal. The software uses this data to trigger essential notifications and ensure claims are paid to the right people.
- Utilize the "Self-Service" Tools: Use the available calculators and projection tools to model different retirement ages or coverage levels. This will make your consultations with a human advisor much more productive, as you will already have a baseline understanding of your options.
- Review Security Settings: Enable biometric login (face or fingerprint ID) on your mobile devices to add an extra layer of security to your financial data.
- Stay Informed on Policy Updates: In 2026, many policies are "dynamic," meaning they may offer lower premiums if you share data from wearable fitness devices or participate in wellness programs integrated into the insurance software.
The integration of advanced software into Howden’s life and health operations represents a shift toward a more transparent, efficient, and personalized insurance experience. By leveraging these tools, clients can gain better control over their financial futures while benefiting from the scale and security of a global brokerage.
Image Gallery
Select an image to open it in a new tab.


Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
