
Choosing auto insurance in Hayward, Wisconsin, requires balancing the state’s mandatory liability requirements with the unique environmental and lifestyle risks inherent to the Northwoods region. Residents must evaluate their specific driving habits, vehicle value, and financial risk tolerance against the offerings of both national carriers and regional providers to secure a policy that balances premium costs with adequate protection against local hazards like wildlife collisions.
Understanding Wisconsin’s Mandatory Insurance Requirements
Before selecting a policy, every driver in Hayward must understand the legal foundation of auto insurance in the state. Wisconsin law mandates that all drivers maintain proof of financial responsibility. This is typically satisfied by purchasing an auto insurance policy that meets the state's minimum liability limits.
As of 2026, the minimum required coverage limits in Wisconsin are:
- $25,000 for the injury or death of one person in an accident.
- $50,000 for the total injury or death of two or more people in an accident.
- $10,000 for property damage caused to others.
While these limits satisfy the legal mandate, they are rarely sufficient for modern vehicle repairs or significant medical expenses. If you are found at fault in an accident involving a newer vehicle or a severe injury, the costs can easily exceed these amounts, leaving you personally liable for the remaining balance. Therefore, most insurance experts recommend “full coverage” or higher liability limits to protect your personal assets.
Analyzing Local Risks: Why Hayward is Different
Hayward’s geography significantly influences your insurance needs. Unlike urban centers where theft or vandalism might be the primary concern, rural Sawyer County presents a different set of challenges.
Wildlife Collisions
The prevalence of white-tailed deer and other wildlife on Wisconsin highways is a major factor for Hayward drivers. A collision with a deer is classified under "Comprehensive" coverage rather than "Collision" coverage. If you reside in or frequently commute through heavily wooded areas, ensure your comprehensive deductible is set at a level you can afford to pay out of pocket, as deer strikes are relatively common in Northern Wisconsin.
Harsh Winter Conditions
Wisconsin winters are notorious for icy roads and reduced visibility. The risk of sliding into a ditch or being involved in a multi-vehicle pileup increases dramatically between November and April. When choosing a policy, investigate if your insurer offers accident forgiveness or if they provide specific roadside assistance services that cover towing from rural locations, which may be farther away from major service centers than in urban areas.
Essential Coverage Types Beyond the Minimum
To build a robust insurance portfolio, you must look beyond the state-mandated minimums. A comprehensive policy in Hayward should generally include the following components:
- Collision Coverage: Pays for damage to your vehicle resulting from a crash with another object or vehicle, regardless of fault.
- Comprehensive Coverage: Covers non-collision events, including deer strikes, falling tree limbs, fire, theft, and vandalism.
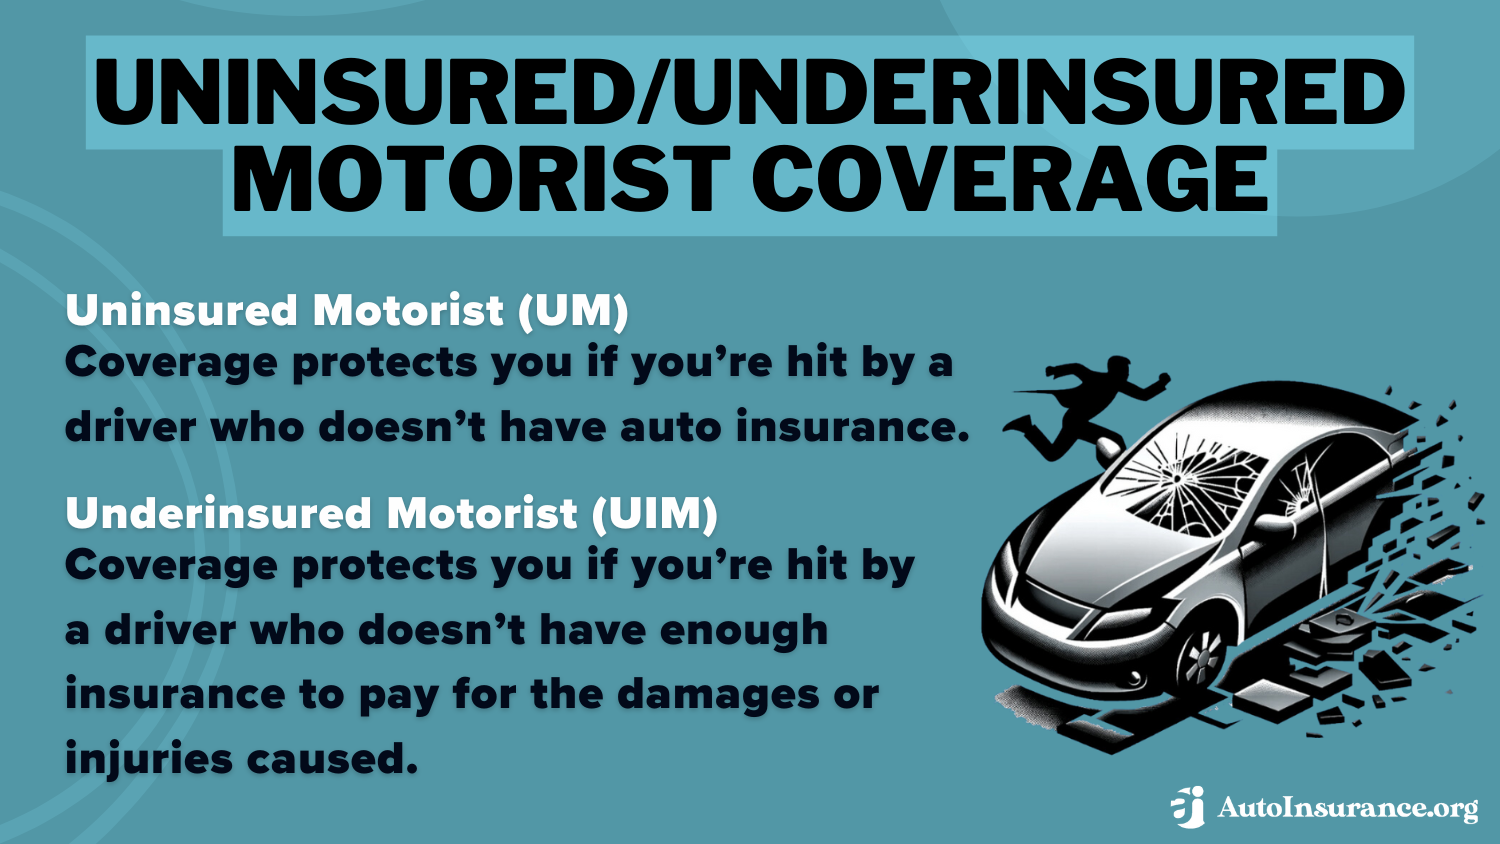
- Uninsured/Underinsured Motorist (UM/UIM) Coverage: This is critical in Wisconsin. It protects you if you are hit by a driver who lacks insurance or carries only the state-mandated minimum, which may not cover your medical bills.
- Medical Payments (MedPay): Covers medical expenses for you and your passengers regardless of who is at fault. This acts as a secondary layer of protection alongside your health insurance.
- Roadside Assistance: Essential for remote stretches of Highway 63 or 77, where cell service may be spotty and service stations are sparse.
Comparing Insurance Providers
When evaluating providers for a Hayward residence, focus on three pillars: financial strength, claims-handling reputation, and local agent availability.
Evaluating National vs. Local Carriers
National carriers often offer sophisticated mobile apps, 24/7 digital claims reporting, and aggressive bundling discounts for home and auto insurance. However, they may lack a physical presence in Sawyer County. Local agencies, by contrast, can provide personalized guidance regarding local road conditions and seasonal risks. They are often better equipped to explain how your specific policy will interact with Wisconsin’s unique subrogation laws.
The Importance of Quotes and Bundling
Most insurers offer a "Multi-Policy Discount" if you bundle your auto insurance with your homeowner’s or renter’s insurance. Given that many Hayward residents also own seasonal cabins or recreational properties, bundling can lead to significant annual savings.
| Feature | Minimum Liability Only | Full Coverage (Recommended) |
|---|---|---|
| Legal Compliance | Yes | Yes |
| Deer/Wildlife Damage | No | Yes |
| Personal Asset Protection | Low | High |
| Loan/Lease Gap Protection | No | Optional |
| Premium Cost | Lowest | Moderate to High |
Steps to Choosing the Right Policy
- Assess Your Asset Exposure: Calculate the value of your vehicle and your total personal assets. If you have significant savings or home equity, higher liability limits are a vital shield.
- Determine Your Deductible Tolerance: A higher deductible (e.g., $1,000) will lower your monthly premium, but you must be able to produce that cash immediately if you need to file a claim.
- Request Quotes from Multiple Sources: Gather quotes from at least three different companies. Ensure you are comparing "apples to apples" by requesting identical coverage limits from each.
- Review the Fine Print: Pay attention to "Exclusions." Some policies may exclude specific types of trailers or recreational vehicles often used in Northern Wisconsin.
- Verify Agent Licensing: Confirm that the agent you are working with is licensed by the Wisconsin Office of the Commissioner of Insurance (OCI).
Common Mistakes to Avoid
- Choosing on Price Alone: The cheapest policy often provides the least protection. A low premium is not a bargain if it leaves you with thousands of dollars in debt after a single incident.
- Neglecting Gap Insurance: If you are financing a new vehicle, your insurance payout in the event of a total loss may be less than the amount you still owe the bank. Gap insurance covers this difference.
- Forgetting Periodic Reviews: Life changes—such as moving, buying a new car, or even your children reaching driving age—significantly alter your risk profile. Review your policy every year at renewal.
Frequently Asked Questions
Does my insurance cover me if I hit a deer on a back road near Hayward? Yes, provided you have "Comprehensive" coverage. In Wisconsin, deer collisions are treated as no-fault claims under the comprehensive portion of your policy. Ensure your deductible is set appropriately to manage the cost of potential repairs.
Is it better to use a national insurance company or a local agent in Sawyer County? Both have advantages. National companies often provide robust digital tools and competitive pricing. Local agents offer personalized service and a deeper understanding of regional risks, such as winter road conditions and local repair shop networks.
Why is Uninsured Motorist (UM) coverage so important in Wisconsin? Many drivers carry only the state-mandated $25,000/$50,000/$10,000 limits. If you are involved in an accident with a serious injury, these limits can be exhausted almost immediately. UM coverage ensures your medical costs are covered even if the other driver is inadequately insured.
Can I get a discount for taking a defensive driving course? Many insurance providers in Wisconsin offer discounts for completion of approved defensive driving courses, especially for younger or older drivers. It is worth asking your agent if your specific policy qualifies for such a reduction.
Does my credit score affect my insurance rates in Wisconsin? Yes, insurance companies in Wisconsin are permitted to use credit-based insurance scores as a factor in determining premiums. Maintaining good credit can help you secure lower rates, as insurers view it as a factor in your overall risk assessment.
Next Steps for Hayward Drivers
To move forward, start by requesting a current summary of your existing coverage. If you are currently at the state minimum, use a quote comparison tool to see the cost difference for moving to $100,000/$300,000 liability limits with $500 or $1,000 deductibles. Contact a local independent agent to discuss how your vehicle usage—whether it is a daily commute to the office or occasional weekend trips into the Chequamegon-Nicolet National Forest—affects your specific risk profile. Being proactive in your selection process ensures that when the unexpected happens, you are protected by a policy designed for the realities of life in Hayward.

Image Gallery
Select an image to open it in a new tab.
Mateo Castillo
Decentralized Finance and E-Payments Strategist
