In 2026, requesting a physical replacement for a lost or damaged auto insurance card is rarely necessary because digital proof of insurance is now legally accepted across all 50 U.S. states and most international jurisdictions. Modern insurance providers prioritize instant access through mobile apps and digital wallets, allowing drivers to download, print, or display current coverage details immediately without waiting for mail delivery.
The Shift to Digital Sovereignty in Auto Insurance
For decades, the "pink slip" or the cardstock insurance certificate was a mandatory inhabitant of every glove box. If that piece of paper was lost, stolen, or became illegible due to age, drivers faced a stressful wait for the postal service to deliver a replacement. However, as we navigate 2026, the landscape of insurance documentation has fundamentally shifted toward digital-first verification.
The primary reason a replacement card is no longer a high-priority "need" is the universal adoption of Electronic Proof of Insurance (ePOI). This transition didn’t happen overnight; it was the result of coordinated legislative efforts led by organizations like the Property Casualty Insurers Association of America and the National Association of Insurance Commissioners (NAIC). By 2026, every state DMV and law enforcement agency has standardized the protocols for accepting digital screens as valid evidence of financial responsibility.
This evolution means that the "original" document is no longer a physical object held in a central office, but a digital record stored in a secure cloud. When you "replace" your card today, you aren't waiting for a printing press; you are simply refreshing a data stream on your smartphone.
Why Physical Replacements Have Become Obsolete
To understand why the traditional replacement process is a relic of the past, we must look at the technical and legal frameworks that support modern driving.
1. Instantaneous Mobile App Access
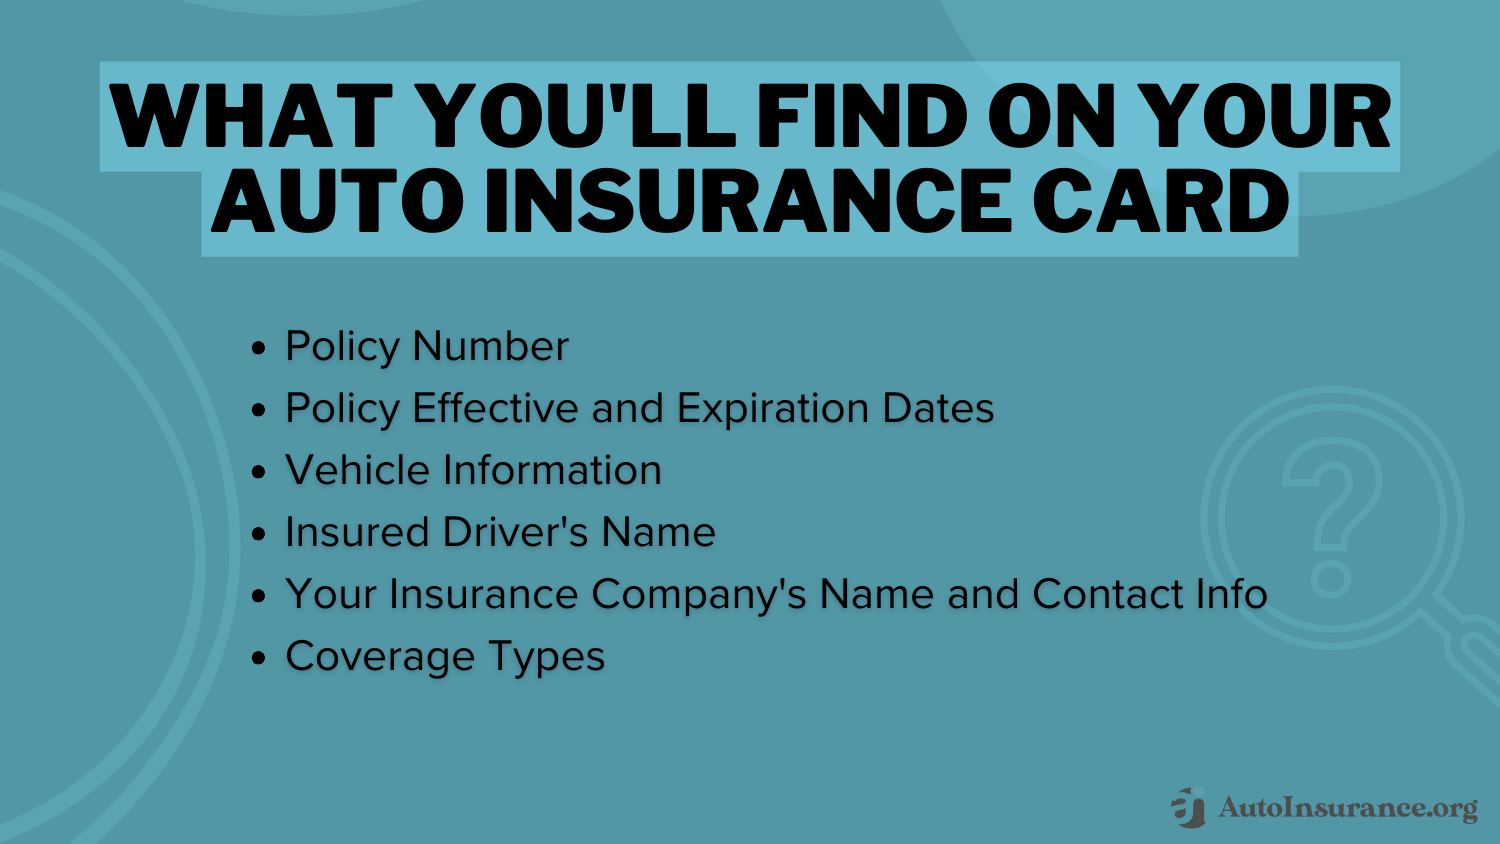
Almost every reputable insurance carrier—from giants like State Farm and GEICO to digital-native insurers—now offers a dedicated mobile application. These apps serve as a persistent, real-time portal to your policy details. When a policy renews or a vehicle is added, the digital card updates automatically. There is no longer a gap between the moment coverage begins and the moment you possess "the card."
Furthermore, these apps are designed to work offline. Most insurance apps cache (store) a copy of your ID card locally on your device. This ensures that even if you are pulled over in a remote area with zero bars of cellular service, you can still pull up the necessary documentation to satisfy a law enforcement officer’s request.
2. Integration with Digital Wallets
In 2026, the integration of insurance cards into Apple Wallet and Google Wallet has become standard practice. This is often more convenient than using a dedicated insurance app because it allows the card to be accessed via lock-screen shortcuts. These digital passes are cryptographically signed by the insurer, making them as difficult to forge as a physical card with a hologram, providing an extra layer of trust for authorities.
3. Print-on-Demand Capabilities
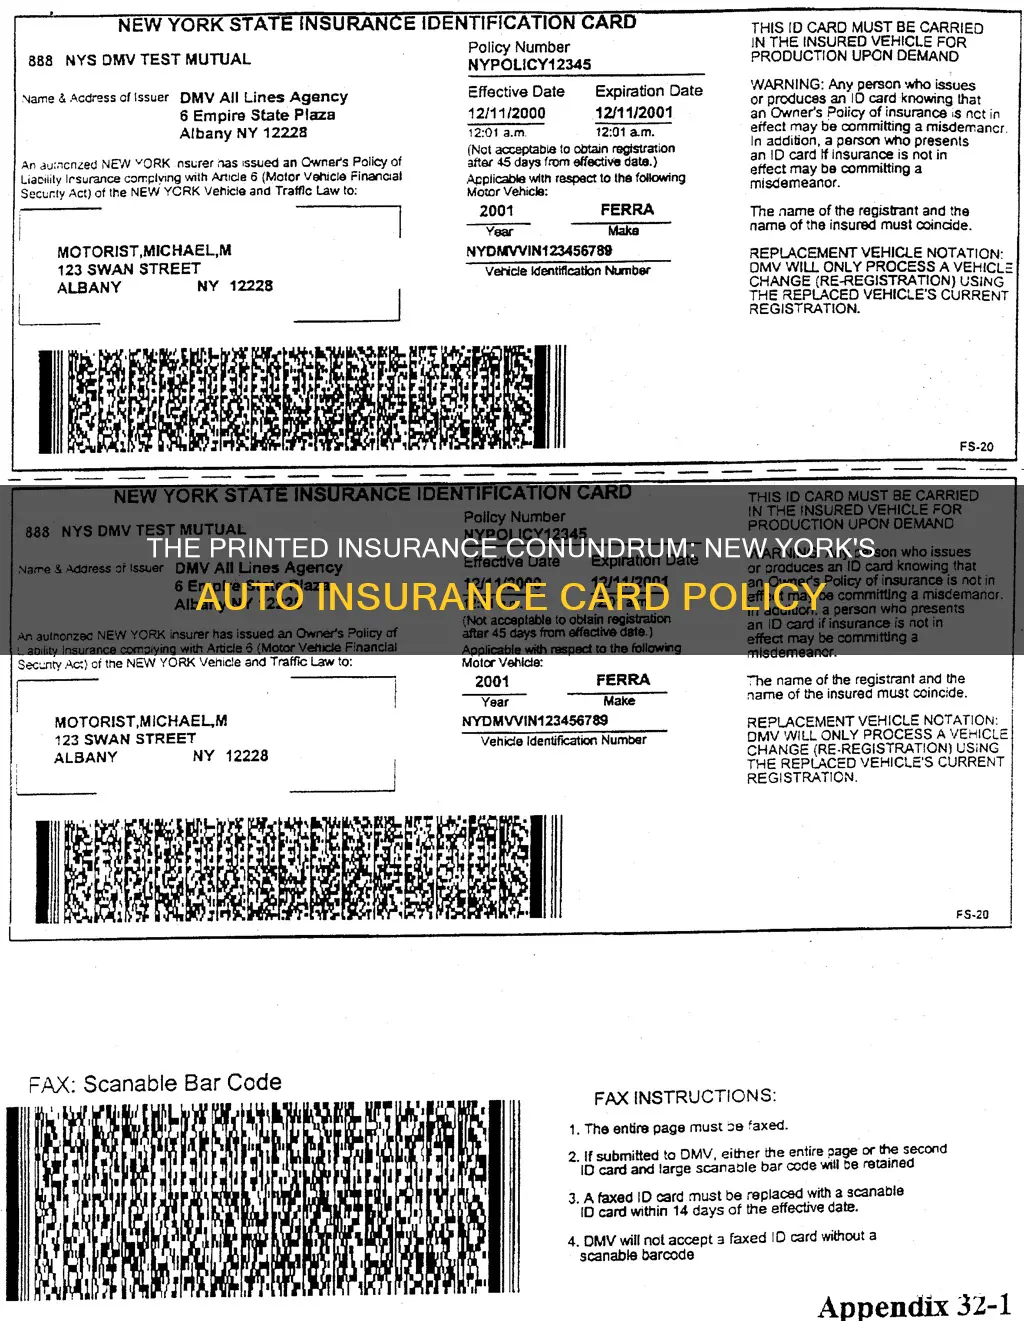
If you are someone who prefers the security of a physical backup, the need to call an agent for a replacement is still gone. Policyholders can log into their online portal from any computer and download a PDF version of their insurance ID card. This PDF is the exact legal equivalent of the card the company would mail to you. You can print it at home, at an office, or even at a local library, ensuring you have a paper copy in seconds rather than days.

Law Enforcement and Real-Time Verification Systems
A significant reason why you rarely need to present a fresh physical card is that law enforcement technology has caught up with the digital age. Many states have implemented real-time insurance verification systems, such as the Alabama Law Enforcement Agency’s ALIR system or similar databases in states like Utah and Nevada.
When a police officer runs your license plate through their onboard computer (Mobile Data Terminal), the system often communicates directly with a state-monitored database that receives daily or even hourly updates from insurance companies. In many instances, the officer already knows your insurance is active before they even walk up to your window. While you are still legally required to carry proof, the "crisis" of a missing card is mitigated by the fact that the officer has secondary ways to verify your status.
The Legal Framework of ePOI
The legal basis for not needing a physical replacement is rooted in state-specific statutes that explicitly permit electronic display. As of 2026, these laws are uniform enough that you can cross state lines without worrying about whether your digital card is valid in a neighboring jurisdiction. These statutes typically include "privacy protections" that prevent an officer from searching the rest of your phone just because you handed it to them to show your insurance.
When a Physical Card Is Still Relevant (The Exceptions)
While replacing a card is rarely needed, "rarely" is not "never." There are specific edge cases where having a physical, company-issued card (or a high-quality home-printed version) is still advisable.
- International Travel: If you are driving across the border into Mexico or shipping a vehicle overseas, international authorities may still demand a physical document. While Canada has largely adopted digital standards, Mexico's requirements can vary by state and may require a specific physical "Mexico Tourist Auto Insurance" certificate.
- Total Device Failure: If your phone's screen is shattered, the battery is dead, or you are in a location with extreme interference that prevents even cached files from loading, a paper backup is your only failsafe.
- Older Vehicle Registration Offices: While most DMVs are fully digital, some small, local county clerk offices in rural areas may still request a paper copy to scan into their specific legacy filing systems during an in-person registration renewal.
- Lienholders and Dealerships: When buying a new car, some dealership finance offices prefer a printed copy for their physical deal jacket, though most have moved to digital uploads by 2026.
Comparing Proof of Insurance Methods in 2026
The following table breaks down the different formats available to drivers and why the digital options have superseded the mailed replacement card.
| Feature | Physical Mailed Card | Mobile App / Digital Wallet | Self-Printed PDF |
|---|---|---|---|
| Availability | 7-10 Business Days | Instant | Instant |
| Cost | Free (but slow) | Free | Cost of Paper/Ink |
| Updates | Requires New Mailing | Automatic / Real-time | Requires Re-printing |
| Offline Access | Yes (Physical) | Yes (If Cached) | Yes (Physical) |
| Durability | Can be lost/torn | Dependent on Battery | Can be lost/torn |
| Legal Status | Universal | Universal (as of 2026) | Universal |
Troubleshooting: What to Do If You Can't Find Your Card
If you realize your insurance card is missing, follow these steps in order of efficiency. You will likely find that you do not need to contact your insurer for a replacement.
- Check the App: Download your insurer’s app. Log in using your policy number or email. Your card will be under a tab labeled "ID Cards" or "Documents."
- Save to Wallet: Look for the "Add to Apple Wallet" or "Add to Google Wallet" icon. This ensures the card is accessible even without an internet connection.
- Email a PDF to Yourself: Use the "Share" or "Email" function within your account portal to send a PDF copy to your inbox. This creates a permanent, searchable backup.
- Screenshot the Card: As a last resort, take a screenshot of the digital ID card. While some officers prefer the "live" app or wallet version, a screenshot is generally accepted as a valid electronic image.
- Check Your Recent Mail: If you recently renewed your policy, the new cards are often attached to the bottom of the "Declarations Page." Many people overlook this and throw it away, thinking it is just a bill.
Security and Privacy Concerns with Digital Proof
One common hesitation regarding the move away from physical cards involves privacy. Many drivers ask: "If I give my phone to a police officer to show my insurance, can they go through my photos or texts?"
By 2026, the legal precedent is well-established. In the United States, the Fourth Amendment protects against unreasonable searches. Most state laws that authorized ePOI specifically state that providing a mobile device for insurance verification does not constitute consent for a search of any other content on the device. To further mitigate risk, modern smartphone operating systems include "Guided Access" (iOS) or "App Pinning" (Android), which locks the phone to a single app before you hand it over.
The Environmental and Economic Impact
Beyond convenience, the move away from physical card replacements is driven by sustainability goals. Insurance companies print and mail millions of cards annually. By 2026, many carriers have adopted "Digital-By-Default" policies, where physical cards are only sent upon specific request (opt-in). This reduces paper waste, lowers postage costs (which helps keep premiums stable), and shrinks the carbon footprint associated with the logistics of document distribution.
Frequently Asked Questions
Do I need a physical insurance card for a car inspection?
In most states that require annual safety or emissions inspections, digital proof is perfectly acceptable. The inspector will simply view the digital card on your phone and transcribe the policy number and expiration date into their system. However, check your specific state's 2026 inspection guidelines, as a few jurisdictions may still require a printed copy for their records.
What if I am in an accident and the other driver needs my info?
If you are in an accident, you can simply show your phone to the other driver. Better yet, most insurance apps now have a "Share Coverage Info" feature that allows you to text or email your insurance details directly to the other party or the responding officer. This eliminates transcription errors and provides an immediate digital paper trail.
Can I use a screenshot of my insurance card?
Yes, a screenshot is generally considered a valid "electronic image" under most state ePOI laws. However, it is better to use the official app or digital wallet because those versions are easier to verify and often contain more up-to-date information, such as the most recent renewal dates.
Are there any states that still require a paper insurance card in 2026?
As of 2026, all 50 U.S. states have passed legislation or regulatory changes that allow for electronic proof of insurance during traffic stops. While the specific wording of these laws can vary slightly, the functional result is the same: a digital screen is a legal substitute for a paper card.
My phone battery died; can the officer look up my insurance?
While many officers have the ability to check your insurance status via their onboard computer and state databases, they are not legally required to do so for you. If you cannot provide proof of insurance (digital or paper), you may still be issued a citation. This is why keeping a backup printed copy in your glove box is still a recommended "best practice," even if a "replacement" from the company is unnecessary.
Summary of Actionable Advice
If you discover your auto insurance card is missing, do not spend time calling your agent to wait for a replacement in the mail. Instead, log into your provider's mobile app and add the digital card to your smartphone's wallet. For maximum security, print one copy of the PDF version and place it in your glove box alongside your vehicle registration. This two-pronged approach—digital for daily convenience and paper for emergency backup—ensures you are fully compliant with the law in 2026 without the need for traditional document replacement services.
Image Gallery
Select an image to open it in a new tab.
Zara El-Hashem
Sociocultural Dynamics and Academics Writer
