Understanding Price Differences for State Farm Auto Insurance Rates in Oklahoma
The price difference for State Farm auto insurance rates in Oklahoma is primarily driven by individual risk factors, including your specific zip code, driving record, vehicle type, and the level of coverage selected. Because State Farm operates through a network of independent local agents, premiums are highly personalized, reflecting Oklahoma's specific regulatory environment and localized risk assessment metrics for 2026.
The Dynamics of Insurance Pricing in Oklahoma
Insurance companies, including State Farm, do not offer a flat-rate premium to all residents of a state. Instead, they use complex actuarial models to determine the probability of a claim. In Oklahoma, these models are influenced by state-specific factors such as the frequency of weather-related claims (hail and wind damage), the prevalence of uninsured motorists, and the cost of vehicle repairs in specific regions.
When you investigate price differences, you are essentially looking at how your profile interacts with these risk variables. State Farm, being the largest auto insurer in the United States by market share, collects vast amounts of data. This allows them to refine their pricing tiers with high granularity. A driver in an urban center like Oklahoma City or Tulsa will often see different rate structures than a driver in a rural county, even if their driving records are identical.
Key Factors Influencing Your Premium
To understand why your specific quote from State Farm might differ from another driver’s, it is necessary to break down the primary components of the underwriting process:
1. Geographic Risk Assessment
Insurance rates are deeply connected to the "territory" in which the vehicle is garaged. In Oklahoma, the risk of damage from severe storms—which can involve hail the size of baseballs—varies by region. Insurers adjust premiums based on historical loss data for specific zip codes. If your neighborhood has a high density of cars parked on the street or a history of frequent severe weather claims, your comprehensive coverage premium will likely reflect that higher risk.
2. Driving Record and Claims History
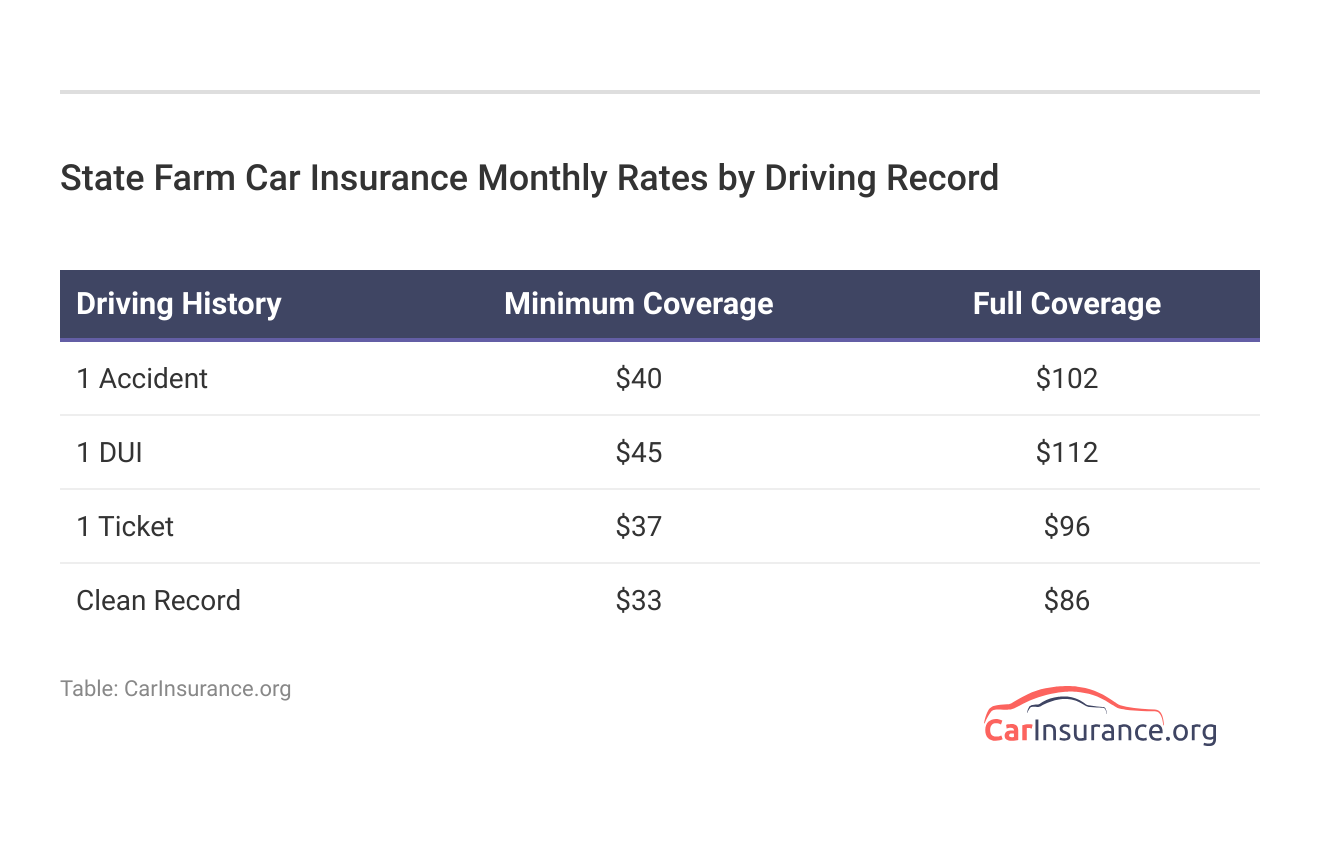
This is the most significant factor under a driver's direct control. State Farm uses your Motor Vehicle Record (MVR) to assign a risk tier. A single speeding ticket or an at-fault accident can lead to a premium surcharge that lasts for three to five years. In Oklahoma, the look-back period for major moving violations is a critical component of your rate calculation.
3. Vehicle Characteristics
The cost to repair your specific vehicle is a major driver of your premium. Newer vehicles with advanced driver-assistance systems (ADAS), such as lane-keeping sensors or automated emergency braking, often cost more to repair after a collision. If you drive a vehicle that is expensive to fix or has a high theft rate, your premium will be higher than that of a driver with an older, standard-repair-cost sedan.
4. Coverage Limits and Deductibles
The "price difference" you see between two different quotes is often a result of selecting different coverage levels. Choosing higher liability limits (the amount the insurer pays if you cause an accident) or a lower deductible (what you pay out-of-pocket before insurance kicks in) will increase your monthly premium. Many Oklahomans opt for higher Uninsured/Underinsured Motorist (UM/UIM) coverage due to the high number of uninsured drivers in the state, which directly impacts the total premium price.
Comparison of Coverage Types and Cost Impacts
Understanding what you are paying for is essential to identifying why your rate might seem high. Use the following table to understand how common coverage choices affect your bottom line.
| Coverage Component | Purpose | Cost Impact |
|---|---|---|
| Liability (BI/PD) | Covers damages to others | High (Mandatory) |
| Collision | Covers repairs to your car | High (Variable) |
| Comprehensive | Covers theft/weather | Moderate (Location Dependent) |
| UM/UIM | Covers accidents with uninsured drivers | Moderate (High priority in OK) |
| Medical Payments | Covers your medical expenses | Low to Moderate |
Working with State Farm Agents in Oklahoma
One unique aspect of the State Farm model is the role of the local agent. Unlike direct-to-consumer insurers that rely entirely on algorithms, State Farm agents can provide manual oversight and advice. In 2026, these agents play a crucial role in helping policyholders identify potential discounts that an automated website might miss.
For instance, if you have recently installed a security system in your garage, moved to a zip code with better theft statistics, or reached a milestone age, a conversation with your agent could reveal savings. The "price difference" between a quote generated online and one discussed with an agent often reflects the application of these situational discounts.
Common Misconceptions About Insurance Rates
Many consumers believe that simply switching insurance carriers every year will lead to the lowest price. While market competition is healthy, frequent switching can sometimes negatively impact your insurance score—a proprietary numerical representation of your risk level used by many insurers.
Another common myth is that credit scores do not affect auto insurance. In Oklahoma, insurers are permitted to use credit-based insurance scores in their rating models. A higher credit score generally correlates with lower risk in the eyes of an insurer, leading to lower premiums. If your credit score has fluctuated, your renewal rate may shift regardless of your driving habits.
Steps to Managing Your Oklahoma Auto Insurance Costs
If you find your State Farm rates higher than expected, take a systematic approach to review and potentially lower them:
- Request a Coverage Review: Sit down with your local Oklahoma agent. Ask them to walk through each line of your policy. Ensure you aren't carrying unnecessary coverage, such as collision insurance on a car with very low market value.
- Evaluate Your Deductibles: If you have enough cash in an emergency fund, increasing your deductible from $500 to $1,000 can significantly reduce your annual premium.
- Inquire About Bundle Discounts: State Farm offers significant discounts for customers who bundle their auto policy with homeowners, renters, or life insurance.
- Enroll in Usage-Based Programs: Programs like Drive Safe & Save monitor your driving habits via a mobile app or connected vehicle device. For safe drivers, this can lead to substantial discounts on premiums, bypassing traditional rating metrics.
- Verify Information Accuracy: Occasionally, errors occur in driving records or the information insurers have on file about your vehicle. Ensure your garage address and annual mileage estimates are accurate.
Regulatory Context in Oklahoma
The Oklahoma Insurance Department (OID) regulates the insurance industry within the state. They ensure that all insurance companies, including State Farm, file their rates and follow fair practices. While the OID does not set the specific rates for companies, they review filings to ensure rates are not excessive, inadequate, or unfairly discriminatory. If you believe your premium increase is unjustified or based on erroneous information, you have the right to request an explanation from the insurer and, if unsatisfied, contact the OID for further guidance.
Frequently Asked Questions
Does living in a rural area of Oklahoma save me money on State Farm insurance? Generally, yes. Rural areas often have lower rates of vehicle theft, less traffic congestion, and fewer frequent collisions compared to metropolitan areas like Oklahoma City or Tulsa. However, this may be offset if your specific area has a high historical frequency of hail or wind damage claims.
Why did my premium increase if I haven’t had an accident? Premium increases are often driven by macro factors outside of your personal control, such as the rising cost of vehicle parts and labor in 2026, increased frequency of natural disasters in Oklahoma, and general insurance industry trends. Even with a perfect record, your rate may adjust to reflect these statewide shifts in risk.
Are State Farm discounts the same for everyone in Oklahoma? No. While some discounts are standard, others are based on specific eligibility criteria. For example, the "Good Student" discount requires specific GPA thresholds, and age-based discounts are restricted to certain brackets. Your agent can verify which discounts you currently qualify for based on your personal profile.
Can I get a lower rate by changing my coverage mid-term? You can update your coverage at any time. However, reducing coverage to save money carries risk. Always ensure you are meeting the legal minimums required by the state of Oklahoma (25/50/25 liability limits) before removing any components of your policy.
How does my car’s age affect my insurance rate in Oklahoma? Older cars generally cost less to insure for physical damage (collision and comprehensive) because their actual cash value is lower. However, if your older car lacks modern safety features, you may miss out on certain safety-related discounts that newer vehicles qualify for.
Next Steps for Your Insurance Policy
To ensure you are receiving the best possible rate with State Farm in Oklahoma, schedule an annual policy review with your agent. During this meeting, present any life changes that may have occurred in the last twelve months, such as changes in your daily commute, new safety features added to your vehicle, or additional insurance needs that could qualify for a multi-policy discount. By maintaining an active relationship with your agent and keeping your driving record clean, you position yourself to receive the most competitive premiums available under your specific risk profile.
Image Gallery
Select an image to open it in a new tab.
Vivian Cho
Executive IT and Emerging Technologies Reporter
