
For a $100 monthly budget in 2026, a healthy 30-year-old can typically secure between $1.5 million and $2 million in term life insurance coverage. However, the exact amount varies dramatically based on your age, health status, and whether you choose term life or a permanent policy like whole life, which offers significantly lower death benefits for the same price.
The quest for life insurance is often a balancing act between the protection your family needs and the monthly premium your budget allows. As of 2026, the $100 monthly price point remains a significant benchmark—it is high enough to secure substantial protection for most working-age adults, yet low enough to remain a sustainable part of a household budget. To understand how much "peace of mind" $100 buys, we must examine the specific levers that insurance companies use to price their products.
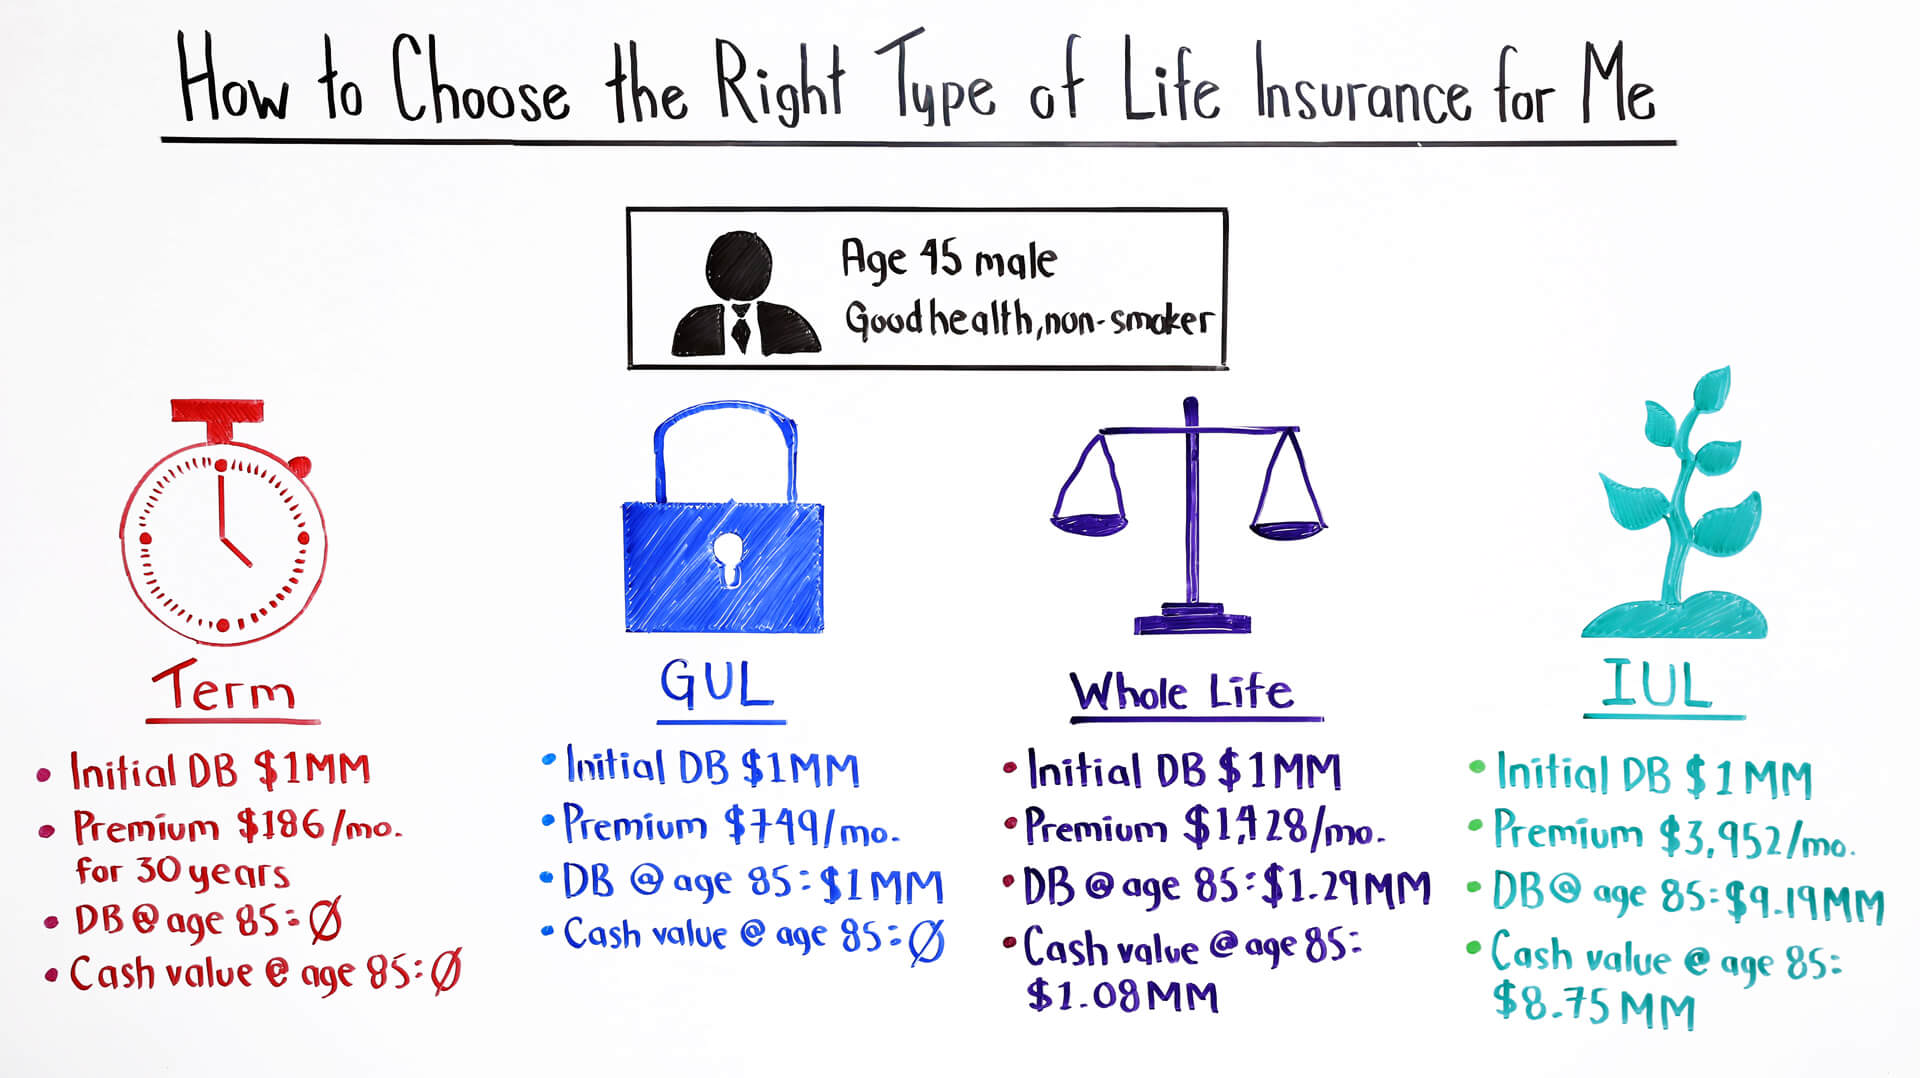
The Critical Distinction: Term Life vs. Permanent Life Insurance
When you allocate $100 per month to life insurance, your first decision is the architecture of the policy itself. In 2026, the market remains bifurcated into two primary categories: term life and permanent (whole or universal) life.
Term Life Insurance: Maximum Coverage for Your Dollar
Term life insurance is designed for pure protection. It covers you for a specific period—typically 10, 20, or 30 years. Because the policy has no cash value and most policies expire before the insured person passes away, the insurance company can offer massive death benefits for a relatively low premium.
For $100 a month, a 35-year-old non-smoker in excellent health might secure a 20-year term policy with a death benefit of $1.2 million to $1.5 million. This is often the preferred choice for families looking to cover a mortgage, replace income during working years, or fund children's future education.
Permanent Life Insurance: Protection with an Investment Component
Whole life or Universal life insurance lasts your entire life and includes a cash value accumulation component. Because the insurer is guaranteed to pay the death benefit eventually (as long as premiums are paid) and a portion of your $100 goes into a savings-like account, the death benefit is much lower.
For that same $100 a month, a 35-year-old might only receive $50,000 to $100,000 in whole life coverage. While this provides a permanent safety net and a small growing asset, it rarely provides the high-level income replacement that young families require.
How Age and Gender Influence Your $100 Coverage Limit
Insurance is the business of pricing risk, and the two most significant risk factors are age and gender. As we move through 2026, actuarial tables have become even more precise, utilizing historical data and modern health trends to determine how much coverage $100 can buy at different life stages.
The Cost of Aging
Every year you wait to purchase life insurance, the amount of coverage you can get for $100 decreases. This is often referred to as the "cost of waiting." In your 20s and 30s, $100 buys a surplus of coverage. By your 50s, that same $100 might only buy half as much. By the time you reach 65, $100 a month might not even meet the minimum requirements for a standard term policy, forcing you toward "final expense" or "burial" insurance which offers much smaller benefits.
The Gender Gap in Premiums
Statistically, women have longer life expectancies than men. In the insurance world, this lower risk of early death translates to lower premiums. A 40-year-old woman will almost always get more coverage for her $100 monthly premium than a 40-year-old man of similar health. This gap can range from 10% to 25% more coverage for women depending on the carrier and the policy length.
Health Classifications and the "Underwriting" Impact
When you apply for a policy, the insurer assigns you a "health class." These classifications are the primary reason two people of the same age can pay the same $100 but receive vastly different death benefits.
- Preferred Plus (Super Preferred): You are in peak physical condition, have no chronic issues, and a clean family medical history. This class gets the most "bang for the buck."
- Preferred: Excellent health, but perhaps one minor issue like slightly elevated cholesterol that is well-controlled.
- Standard Plus: Better than average health, but some minor red flags.
- Standard: You have average life expectancy and perhaps some manageable health issues or a higher BMI (Body Mass Index).
- Substandard (Rated): You have significant health issues (diabetes, heart disease). Here, $100 might buy a very small fraction of what a Preferred Plus individual receives.
The Smoker Penalty
In 2026, the distinction between smokers and non-smokers remains the single most expensive lifestyle factor. If you smoke or use nicotine products, your $100 a month will often buy only 30% to 50% of the coverage a non-smoker would get. For many insurers, even occasional vaping or nicotine replacement therapy can trigger smoker rates.
Estimated Coverage Amounts for $100/Month (2026 Data)
The following table provides estimated coverage amounts for a 20-year term life policy and a standard whole life policy based on "Preferred" health status and non-smoking habits.
| Age at Purchase | Gender | Term Life (20-Year) | Whole Life (Permanent) |
|---|---|---|---|
| 25 Years Old | Male | $2,000,000+ | $150,000 |
| 25 Years Old | Female | $2,500,000+ | $175,000 |
| 35 Years Old | Male | $1,250,000 | $90,000 |
| 35 Years Old | Female | $1,500,000 | $110,000 |
| 45 Years Old | Male | $550,000 | $50,000 |
| 45 Years Old | Female | $675,000 | $65,000 |
| 55 Years Old | Male | $200,000 | $25,000 |
| 55 Years Old | Female | $275,000 | $35,000 |
| 65 Years Old | Male | $60,000 | $12,000 |
| 65 Years Old | Female | $85,000 | $18,000 |
Note: These are approximations for 2026. Actual quotes depend on specific carrier algorithms and individual medical exams.
The Role of Policy Riders in Your $100 Budget
A "rider" is an optional add-on to a life insurance policy that provides extra benefits, usually at an additional cost. If you have a strict $100 monthly limit, adding riders will reduce your total death benefit.
- Waiver of Premium: If you become totally disabled and cannot work, the insurance company pays your premiums for you. This might cost $5-$10 of your $100 budget.
- Child Term Rider: Adds a small amount of life insurance for your children to the same policy.
- Accelerated Death Benefit: This is often included for free in 2026. It allows you to access a portion of your death benefit if you are diagnosed with a terminal illness.
- Accidental Death Benefit: Doubles the payout if you die in an accident. While tempting, it often isn't the best use of a limited $100 budget compared to simply buying more "all-cause" coverage.
Modern Underwriting in 2026: Accelerated vs. Traditional
As of 2026, the way you "buy" your $100 policy has shifted significantly toward digital, data-driven underwriting.
Accelerated Underwriting (No-Exam)
Many companies now offer "accelerated underwriting." By using AI to scan your medical records, prescription history, and even motor vehicle records, they can approve a policy in minutes without a medical exam. For a $100 monthly premium, this is often the most convenient route. However, be aware that if you have complex health issues, accelerated underwriting might result in a higher price (and thus lower coverage) than a traditional exam-based policy where you can prove your health through blood tests.
Traditional Underwriting
For those seeking the absolute maximum coverage for their $100, a traditional medical exam is still often the best path. By providing a blood and urine sample, you give the insurer more certainty. Reduced uncertainty for the insurer usually results in a lower "risk premium" for you, allowing your $100 to stretch further.
How to Calculate if $100 Monthly is Enough for You
While $100 is a convenient round number for budgeting, you should ensure it meets your family's actual needs. Financial planners often use the DIME formula to determine the necessary death benefit:
- Debt: Total all your outstanding debts (excluding mortgage).
- Income: Multiply your annual income by the number of years your family needs support (e.g., 10 or 15 years).
- Mortgage: The remaining balance on your home.
- Education: The estimated cost of tuition for your children.
If your DIME calculation says you need $1.5 million in coverage, and your $100 budget only buys $800,000 because of your age or health, you may need to adjust your budget or consider a shorter term (e.g., a 15-year term instead of a 30-year term) to get the coverage amount you need within that $100 price point.
Common Mistakes When Buying Life Insurance with a $100 Budget
1. Buying Too Much "Permanent" Insurance Too Early
Many people are attracted to the "cash value" of whole life insurance. However, if you have a young family and a $100 limit, spending it all on a $100,000 whole life policy leaves your family severely underinsured if the primary breadwinner passes away. In 2026, experts generally recommend prioritizing the death benefit amount via term insurance first.
2. Ignoring the "Convertible" Feature
In 2026, most quality term policies are "convertible." This means you can turn your term policy into a permanent policy later without a medical exam. If you start with a $100 term policy today, you protect your insurability for the future, even if your health declines.
3. Not Shopping Around
Insurance rates can vary by 20% to 50% between companies for the exact same person. One company might be more "friendly" toward people with a history of anxiety, while another might offer better rates for those with a high BMI but good cardiovascular health. Using an independent broker who can compare multiple 2026 rate tables is essential to maximizing your $100.
Frequently Asked Questions
Can I get life insurance for $100 a month if I have a pre-existing condition?
Yes, but the coverage amount will be lower. For chronic conditions like well-managed Type 2 diabetes, you might still get a substantial term policy, but you will likely be placed in a "Standard" or "Substandard" health class. This means your $100 might buy $400,000 in coverage instead of the $1 million a "Preferred" individual would receive.
Does $100 a month cover both me and my spouse?
It can, but usually through two separate, smaller policies or a "joint" policy. However, joint policies are less common in 2026 because they are less flexible. It is generally better for each spouse to have their own policy. For a combined $100 ($50 each), a young healthy couple could each potentially secure $500,000 to $750,000 in term coverage.
Will my premium stay at $100 forever?
If you buy a Level Term or Whole Life policy, yes. The premium is locked in at the time of purchase. However, if you buy "Annual Renewable Term," the price starts very low but increases every year. For long-term budgeting, level-premium policies are highly recommended so that your $100 commitment remains predictable.
What happens if I can no longer afford the $100 monthly payment?
If you have a term policy and stop paying, the coverage will lapse after a grace period (usually 30 days), and you get nothing back. If you have a whole life policy, you may be able to use the accumulated "cash value" to pay the premiums for a while, or you can surrender the policy for its current cash value.
Is $100 a month considered "expensive" for life insurance in 2026?
For a young person in their 20s, $100 is quite a high premium, likely buying more coverage than they strictly need. For someone in their 50s, $100 is a modest budget that requires careful selection to ensure enough coverage. "Expense" is relative to the death benefit you receive in return.
Practical Recommendation: Your Next Steps
If you have decided that $100 is your monthly limit for life insurance in 2026, your next action should be to prioritize the death benefit over cash value. For most people, this means choosing a 20-year or 30-year level term policy.
Start by obtaining quotes from at least three different carriers. In the current 2026 market, many insurers allow you to adjust the "coverage slider" on their websites. Move the slider until the premium hits exactly $100 and see which company offers the highest death benefit for that price. Once you find the best value, check the insurer's financial strength rating (such as from A.M. Best or S&P Global) to ensure they have the long-term stability to pay out a claim decades from now. If you are unsure about your health class, consult with an independent agent who can "pre-shop" your medical history across multiple carriers without triggering a formal application.
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
