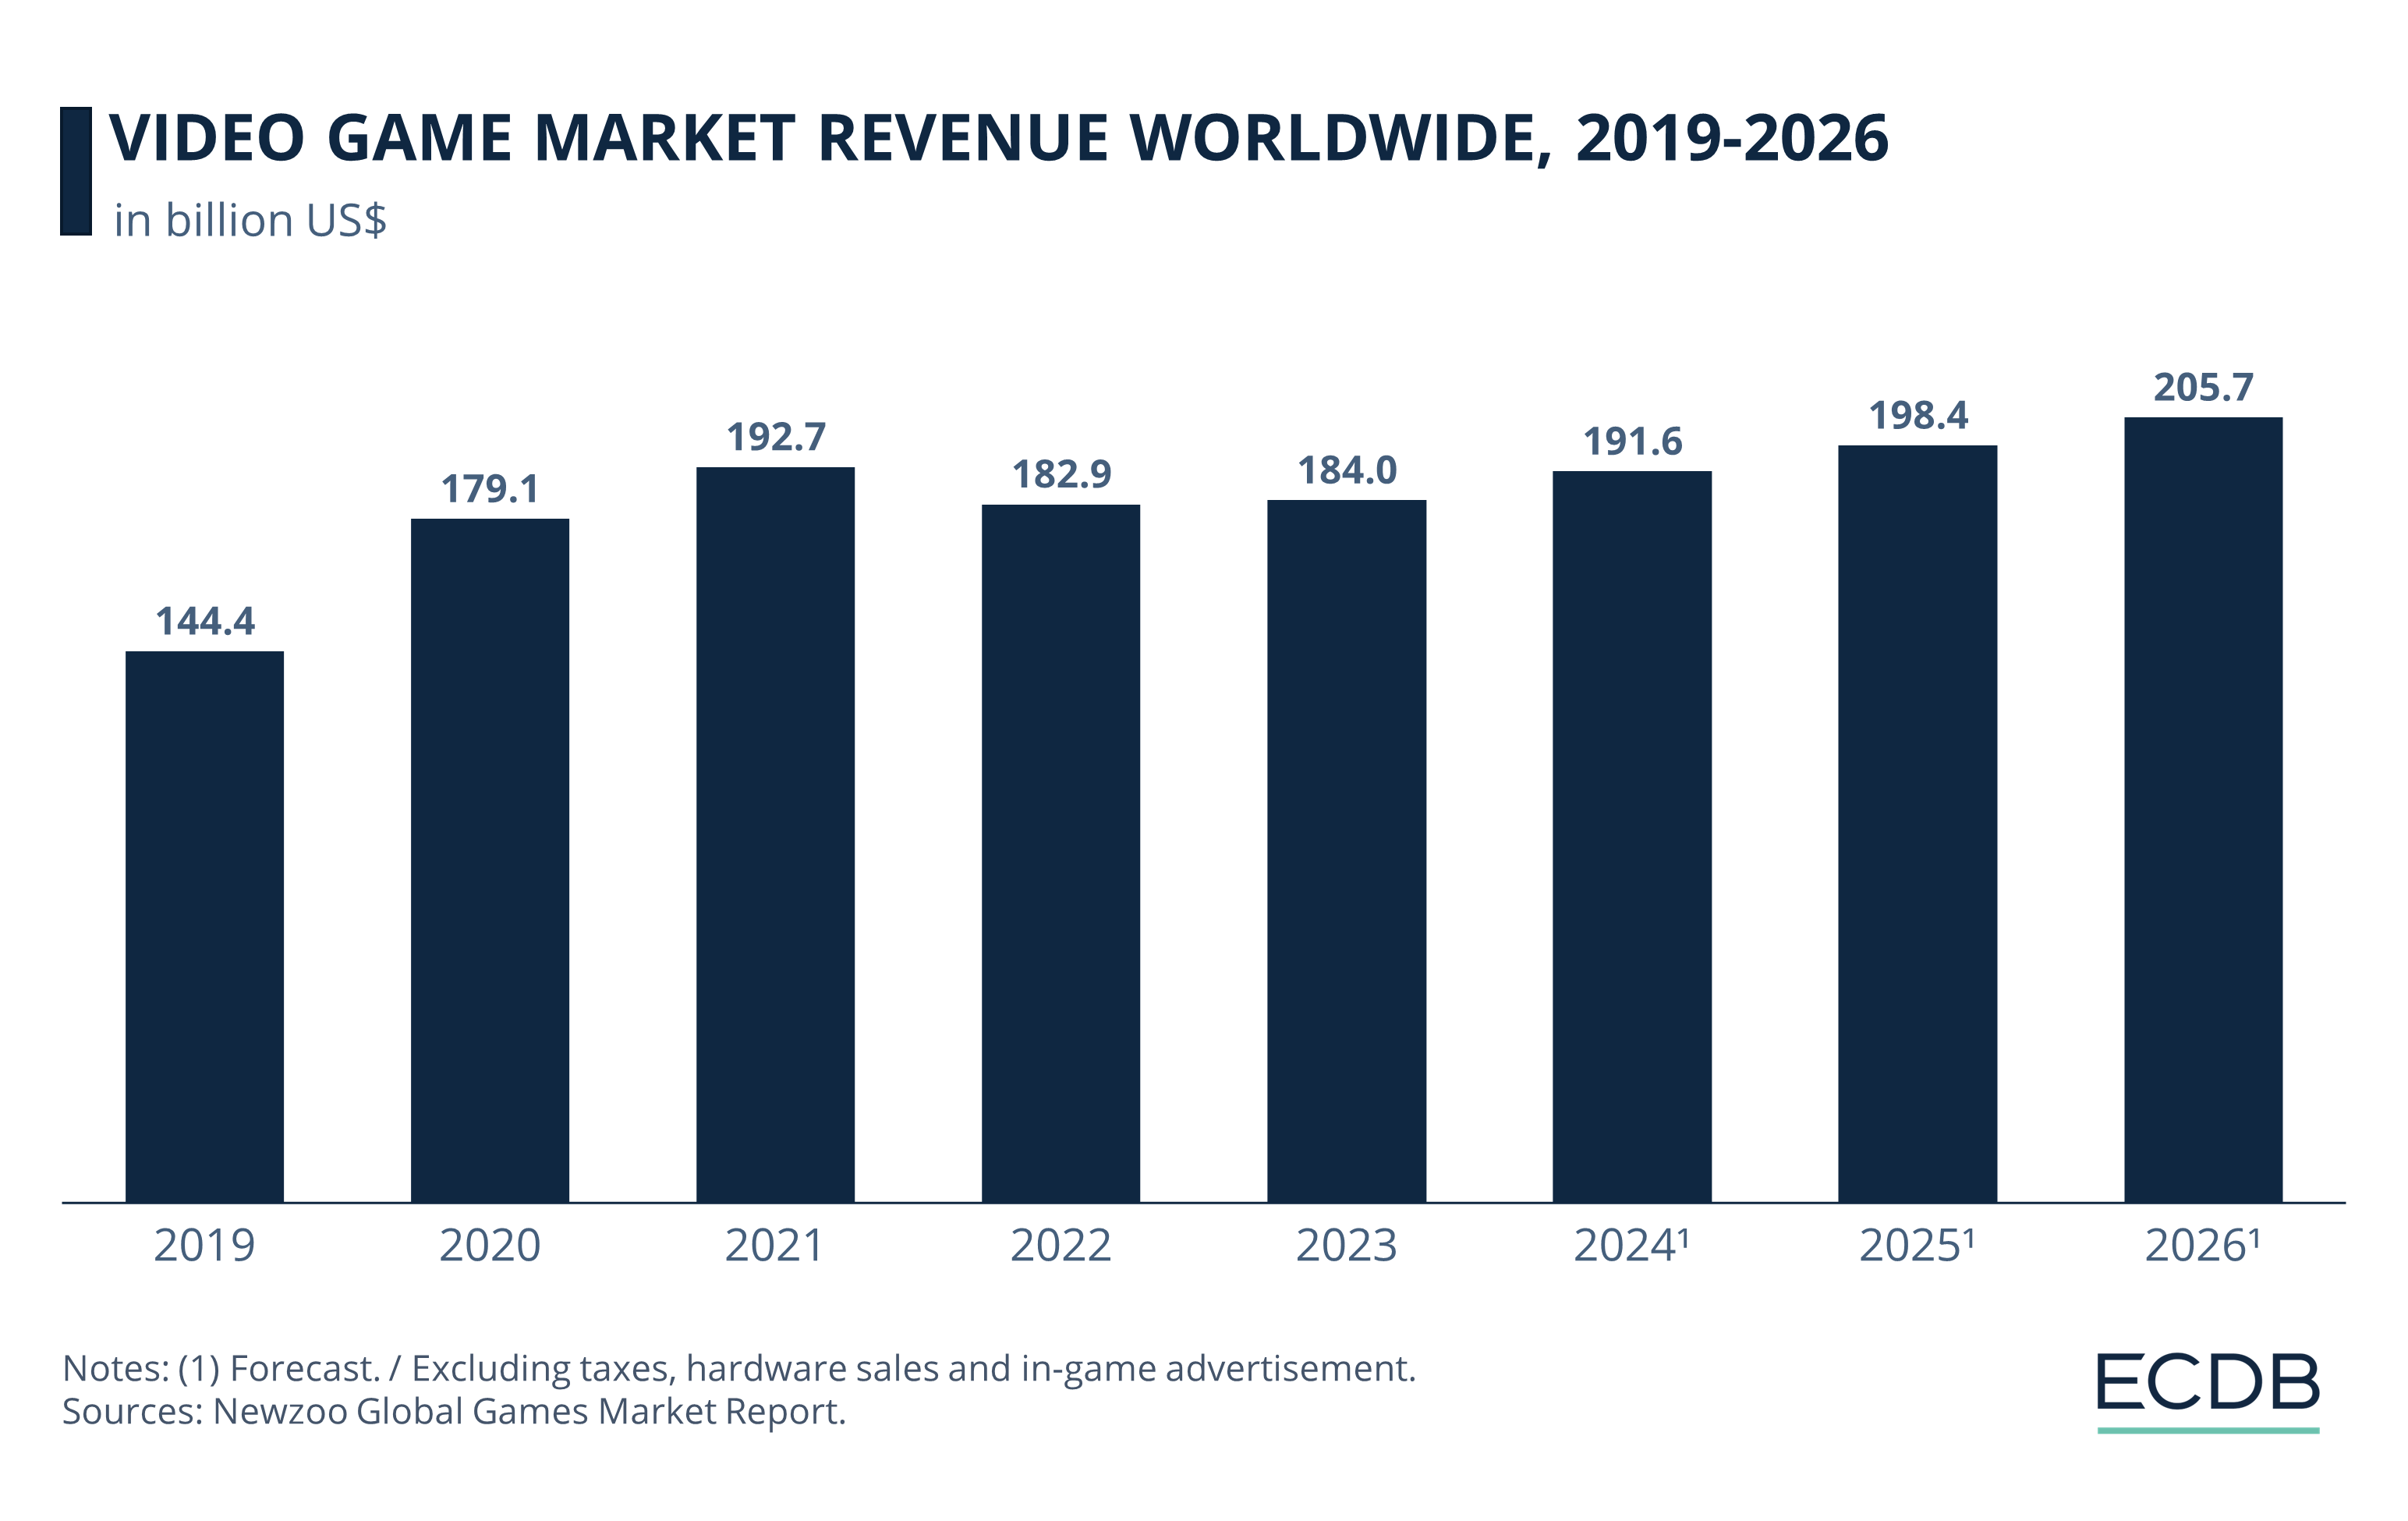
The global video game industry is valued at approximately $225.6 billion in 2026. This valuation reflects a steady recovery and subsequent expansion following the post-pandemic market correction, driven by advancements in mobile processing power, the ubiquity of subscription services, and the integration of sophisticated artificial intelligence in game development and live-service management.
The Evolution of Market Valuation: From Niche to Dominance
The journey to a quarter-trillion-dollar valuation has been characterized by several distinct eras of growth. In the late 20th century, the industry was primarily hardware-centric, with value tied almost exclusively to the sale of physical consoles and cartridges. By the mid-2010s, the shift toward digital distribution began to decouple value from physical retail, allowing for higher profit margins and the birth of "games as a service" (GaaS).
In 2026, the value of the industry is no longer measured solely by unit sales. Instead, it is calculated through a complex ecosystem of recurring revenue, intellectual property (IP) licensing, and cross-media integration. The industry has effectively outpaced both the global film and music industries combined for several years, cementing its status as the world’s premier form of interactive entertainment. This valuation is supported by a global player base exceeding 3.4 billion people, meaning nearly 40% of the world’s population engages with video games in some capacity.
Segment Analysis: Where the Value Resides
The total market value is distributed across three primary pillars: mobile, console, and PC gaming. While each segment contributes to the $225.6 billion total, their growth trajectories and economic structures vary significantly.
Mobile Gaming: The Financial Juggernaut
Mobile gaming continues to hold the largest share of the market, accounting for roughly 52% of total industry revenue. In 2026, the value of the mobile segment is driven by the maturation of "hybrid-casual" games and the increasing capability of smartphones to handle high-fidelity, "console-quality" experiences. The proliferation of 5G networks has eliminated many of the latency barriers that previously limited mobile gaming to simple puzzle genres.
Mobile's value is also deeply rooted in its accessibility. Unlike consoles or high-end PCs, the entry cost for mobile gaming is often zero, as most titles utilize a freemium model. According to Newzoo, the ability of mobile developers to monetize through microtransactions and highly targeted in-game advertising remains the industry's most efficient revenue engine.
Console Gaming: The Premium Experience
Consoles represent approximately 25% of the market value. In 2026, the industry is seeing the tail end of the ninth generation of consoles (PlayStation 5 and Xbox Series X|S) while anticipating mid-generation refreshes and the continued success of Nintendo’s hardware iterations. The value here is increasingly shifting from individual game sales to ecosystem lock-in.
Subscription models like Xbox Game Pass and PlayStation Plus have transformed how console manufacturers calculate value. Instead of a one-time $70 purchase, the lifetime value of a customer is now measured by their monthly subscription fee and their propensity to purchase downloadable content (DLC) within that ecosystem.
PC Gaming: The Innovation Hub
The PC segment remains the most stable and technologically advanced portion of the industry, contributing about 20% of the total value. PC gaming thrives on digital storefronts like Steam, Epic Games Store, and GOG. Its value is bolstered by the high average revenue per user (ARPU) found in dedicated gaming communities, particularly those involved in competitive esports and complex simulation genres.
Revenue Models and the Shift to Recurring Income
The valuation of the video game industry has been significantly boosted by the transition from transactional to recurring revenue models. In 2026, the traditional "buy-once-play-forever" model is largely reserved for indie titles and specific prestige single-player experiences.
Subscriptions and Battle Passes
Subscriptions have become the primary driver of predictable revenue. By providing a "Netflix-style" library of games, platforms ensure a constant stream of income regardless of individual game release cycles. Furthermore, the "Battle Pass" system—a seasonal monetization strategy where players pay for the right to earn rewards through gameplay—has become the standard for multiplayer titles. This model incentivizes long-term engagement, which is a key metric for modern industry valuation.
Microtransactions and In-Game Economies
Microtransactions, including cosmetic "skins," loot boxes (where legally permitted), and currency packs, account for a massive portion of the industry's net value. Critics often point to the ethical concerns of these models, but from a purely economic standpoint, they have allowed games like Fortnite, Roblox, and Genshin Impact to generate billions of dollars in revenue years after their initial release.
Comparative Market Data (2026 Estimates)
| Segment | Estimated Revenue (USD) | Market Share | Key Drivers |
|---|---|---|---|
| Mobile | $117.3 Billion | 52% | 5G adoption, microtransactions, emerging markets |
| Console | $56.4 Billion | 25% | Subscription services, hardware loyalty, AAA exclusives |
| PC | $45.1 Billion | 20% | High-end hardware, Steam ecosystem, Esports |
| VR/AR/Other | $6.8 Billion | 3% | Immersive tech, cloud gaming, peripheral sales |
The Role of Emerging Technologies
By 2026, the value of the video game industry is inextricably linked to technological innovation. These are not merely "gimmicks" but are fundamental to how games are made and sold.
Artificial Intelligence (AI) in Development
AI has become a major value multiplier. Generative AI tools are now used to create vast open worlds, procedural dialogue, and localized voice-overs at a fraction of the historical cost. This efficiency allows studios to maintain the high graphical standards expected in 2026 while managing the ballooning budgets that previously threatened the stability of major developers.
Cloud Gaming and Infrastructure
Cloud gaming has moved from a niche concept to a legitimate market segment. Services like NVIDIA GeForce Now and Xbox Cloud Gaming allow players to stream high-end games to low-powered devices. This expands the "addressable market"—the number of people who can potentially buy and play a game—by removing the $500 hardware barrier of a console or the $1,500 barrier of a gaming PC.
Regional Dominance: Asia-Pacific and Beyond
Geographically, the value of the video game industry is heavily weighted toward the Asia-Pacific (APAC) region. China remains the world’s largest individual gaming market by revenue, despite regulatory hurdles. The growth in Southeast Asia and India is particularly notable in 2026, as increasing internet penetration and smartphone ownership bring hundreds of millions of new players into the ecosystem.
North America and Europe remain the leaders in terms of "spend per player." The Entertainment Software Association (ESA) reports that gaming is the primary form of entertainment for Americans under the age of 45, surpassing television and social media in total hours spent. This high level of engagement translates directly into sustained market value through hardware sales and software subscriptions.
The Impact of Esports and Content Creation
The value of the industry extends beyond the games themselves into the "peripheral" economy of esports and content creation. Platforms like Twitch and YouTube Gaming serve as the marketing arm of the industry. In 2026, the synergy between game developers and "influencers" is a formalized part of the valuation chain.
Esports, while experiencing a period of consolidation, has settled into a sustainable model focused on regional leagues and high-value sponsorships. The "viewer value" is now a recognized metric, as fans who watch gaming content are significantly more likely to purchase in-game items and follow a franchise for multiple years.
Challenges and Economic Headwinds
Despite the $225.6 billion valuation, the industry faces several structural challenges in 2026:
- Development Costs: The cost of producing a "AAA" title can now exceed $300 million, making every major release a "make-or-break" moment for even large publishers.
- Regulatory Scrutiny: Governments in the EU and North America continue to investigate monetization practices, particularly those involving "dark patterns" or gambling-adjacent mechanics.
- Market Saturation: With thousands of games released monthly, "discoverability" is a major hurdle. The value of the industry is increasingly concentrated at the top, with a few mega-hits capturing the majority of player time and money.
Frequently Asked Questions
Is the video game industry bigger than the movie industry?
Yes, the video game industry has been significantly larger than the global box office for several years. In 2026, the interactive entertainment market is roughly three times the size of the global film industry in terms of annual revenue. This is largely due to the recurring nature of gaming revenue compared to the one-time ticket sales of movies.
What is the most valuable gaming company in 2026?
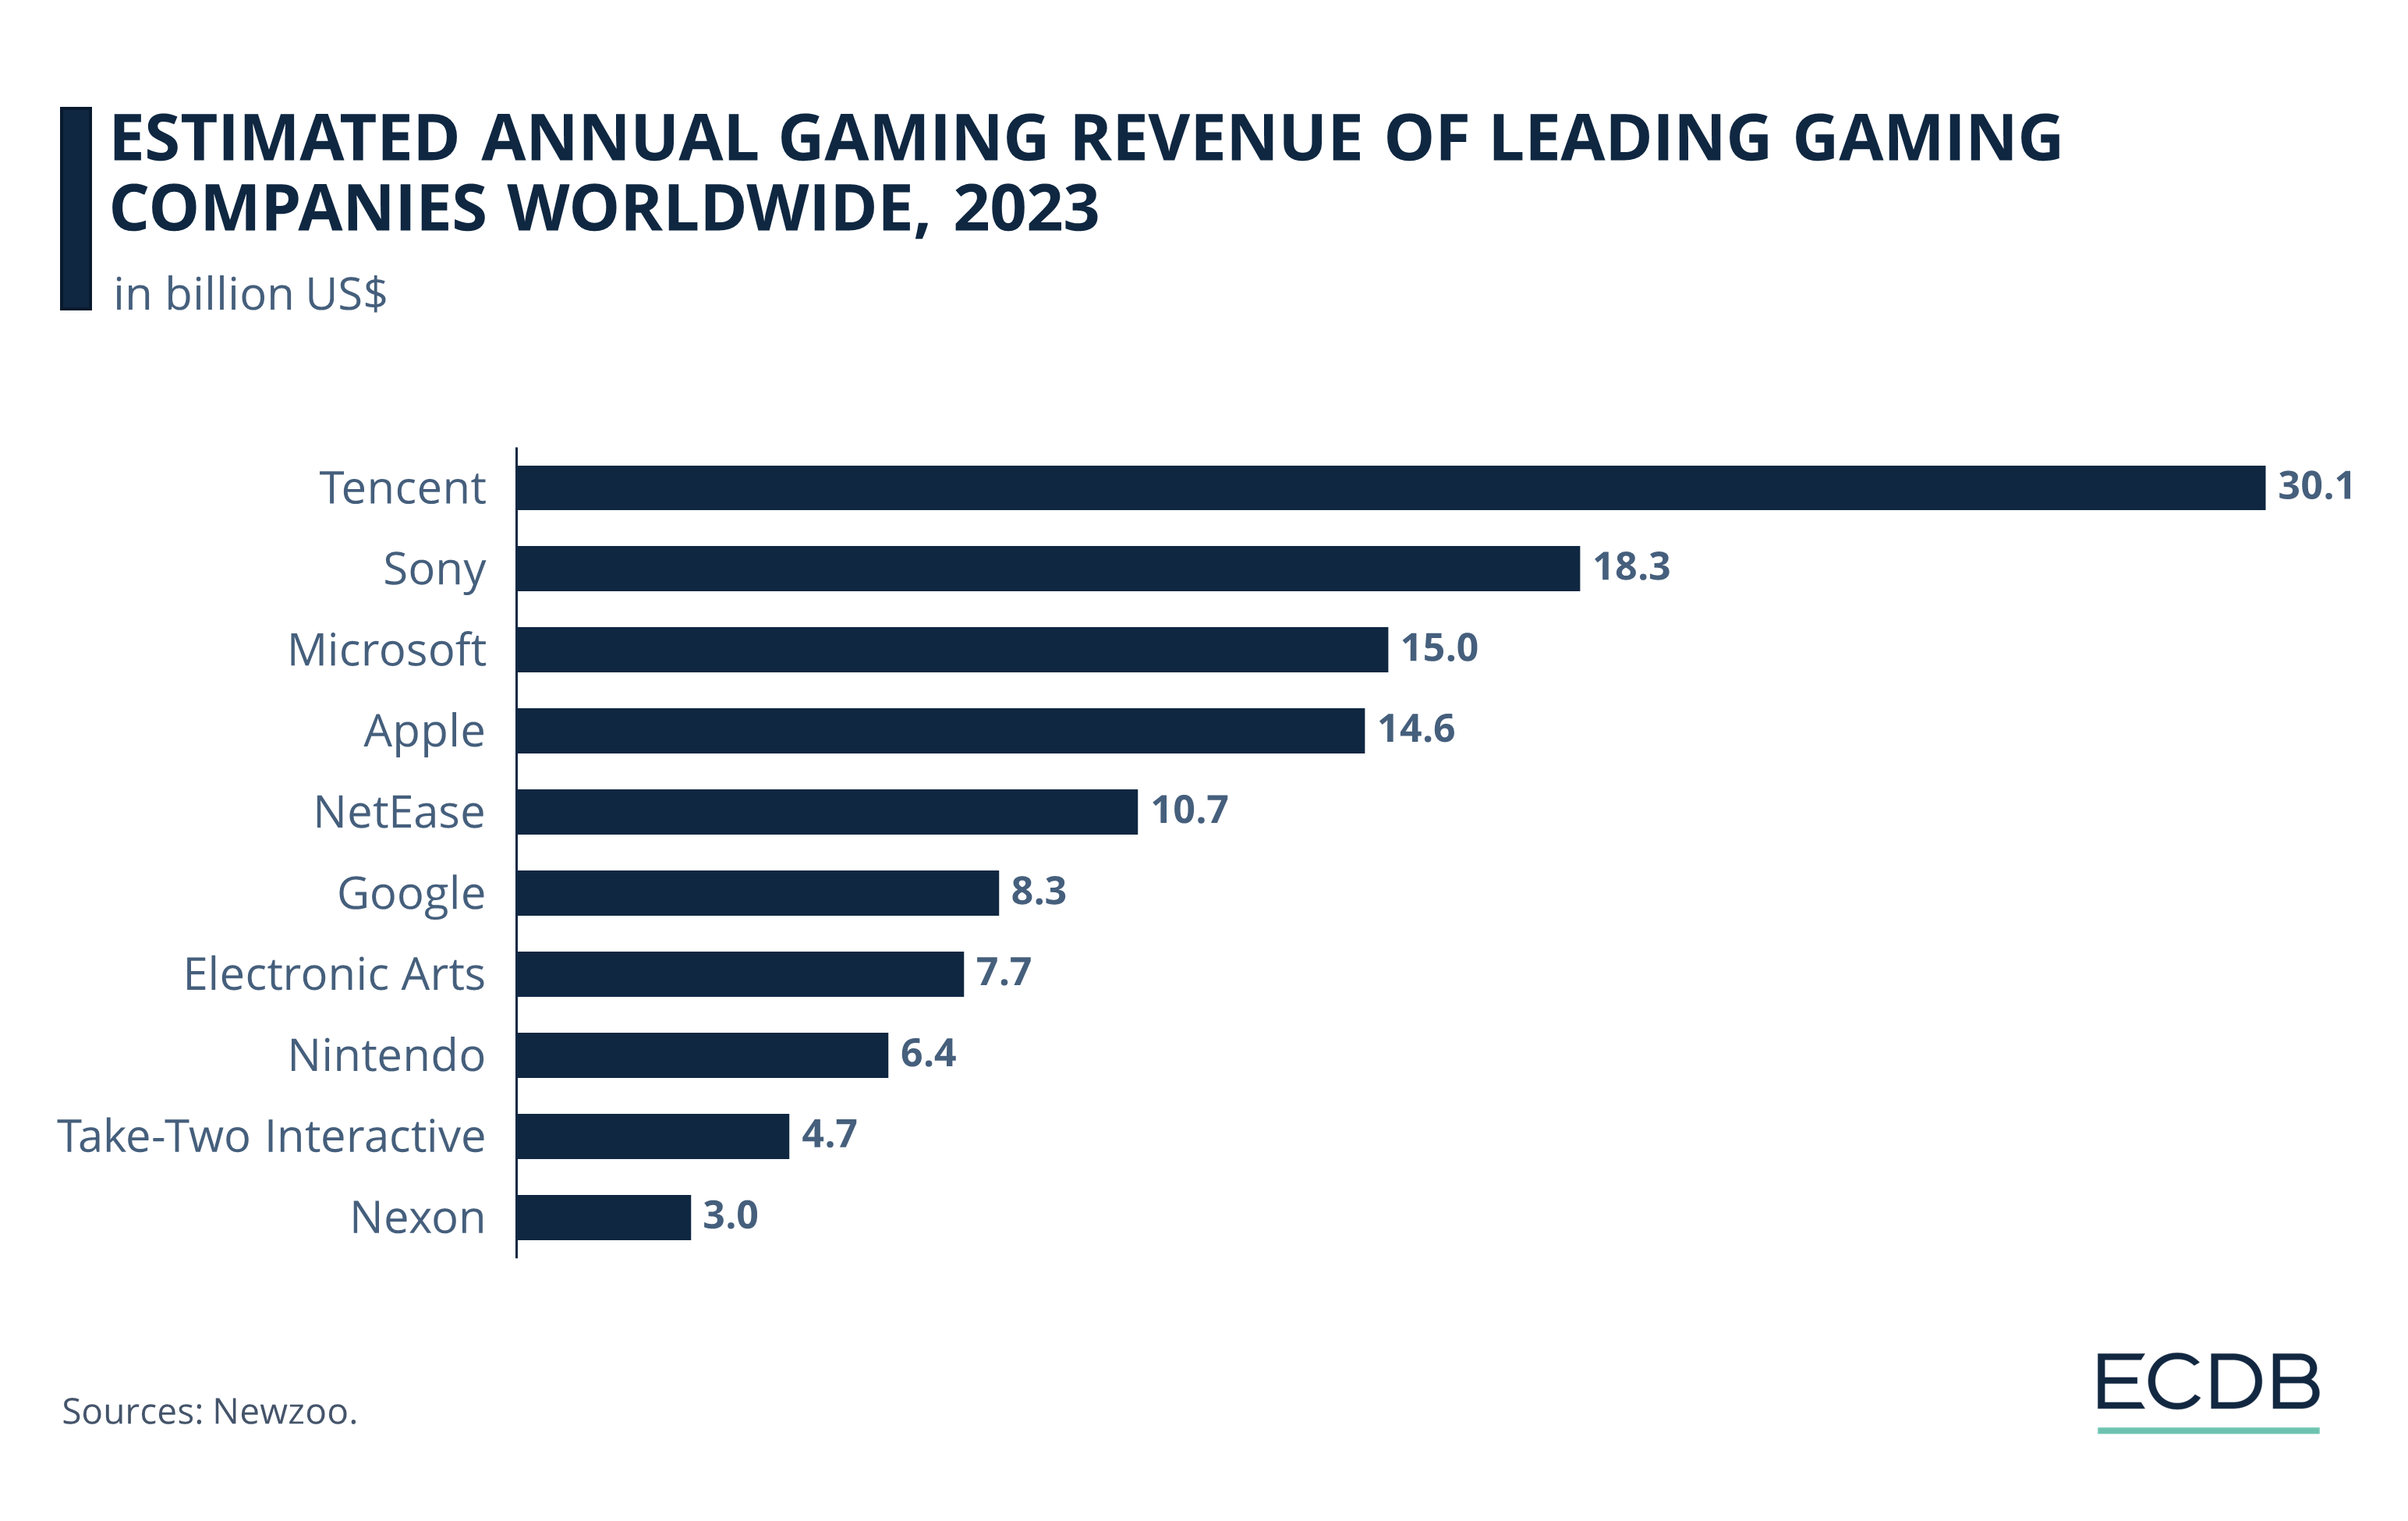
Tencent remains the world's largest video game company by revenue, thanks to its massive portfolio of mobile titles and stakes in Western developers like Epic Games and Riot Games. Microsoft (Xbox) and Sony (PlayStation) follow closely, particularly after the major acquisitions that reshaped the landscape in the early 2020s.
How much do gamers spend on average?
Spending varies wildly by region and platform. In established markets like the US and Japan, the average "hardcore" gamer may spend upwards of $500–$1,000 annually when hardware, subscriptions, and individual software purchases are included. In emerging markets, the spend is much lower, often centered around small, frequent microtransactions in mobile games.
Does the $225.6 billion include hardware sales?
Yes, comprehensive industry valuations typically include the revenue generated from consoles, PC gaming components (GPUs, peripherals), and VR headsets. However, the software and services segment usually accounts for about 70-80% of the total value, as hardware is often sold at low margins to build an install base for software.
Is VR (Virtual Reality) a major part of the industry's value?
While growing, VR and AR (Augmented Reality) remain a smaller slice of the total market, estimated at around 3% in 2026. The value in this sector is driven by specialized headsets and the "Metaverse" applications in enterprise and social gaming, but it has not yet reached the mass-market ubiquity of mobile or console gaming.
Next Actions for Stakeholders
For investors and analysts, the primary focus in 2026 should be on platform-agnostic IP. Companies that can successfully transition their brands across mobile, PC, and film/TV (transmedia) are seeing the highest valuation multiples.
For developers, the "value" lies in retention. In a saturated market, the cost of acquiring a new player is higher than ever. Strategies that prioritize community building, regular content updates, and fair monetization are essential for maintaining the long-term asset value of a gaming franchise.
To stay updated on real-time shifts in market value, it is recommended to monitor quarterly earnings reports from major players like Sony, Microsoft, and Tencent, as well as annual data releases from the ESA and Statista.
Image Gallery
Select an image to open it in a new tab.


Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
