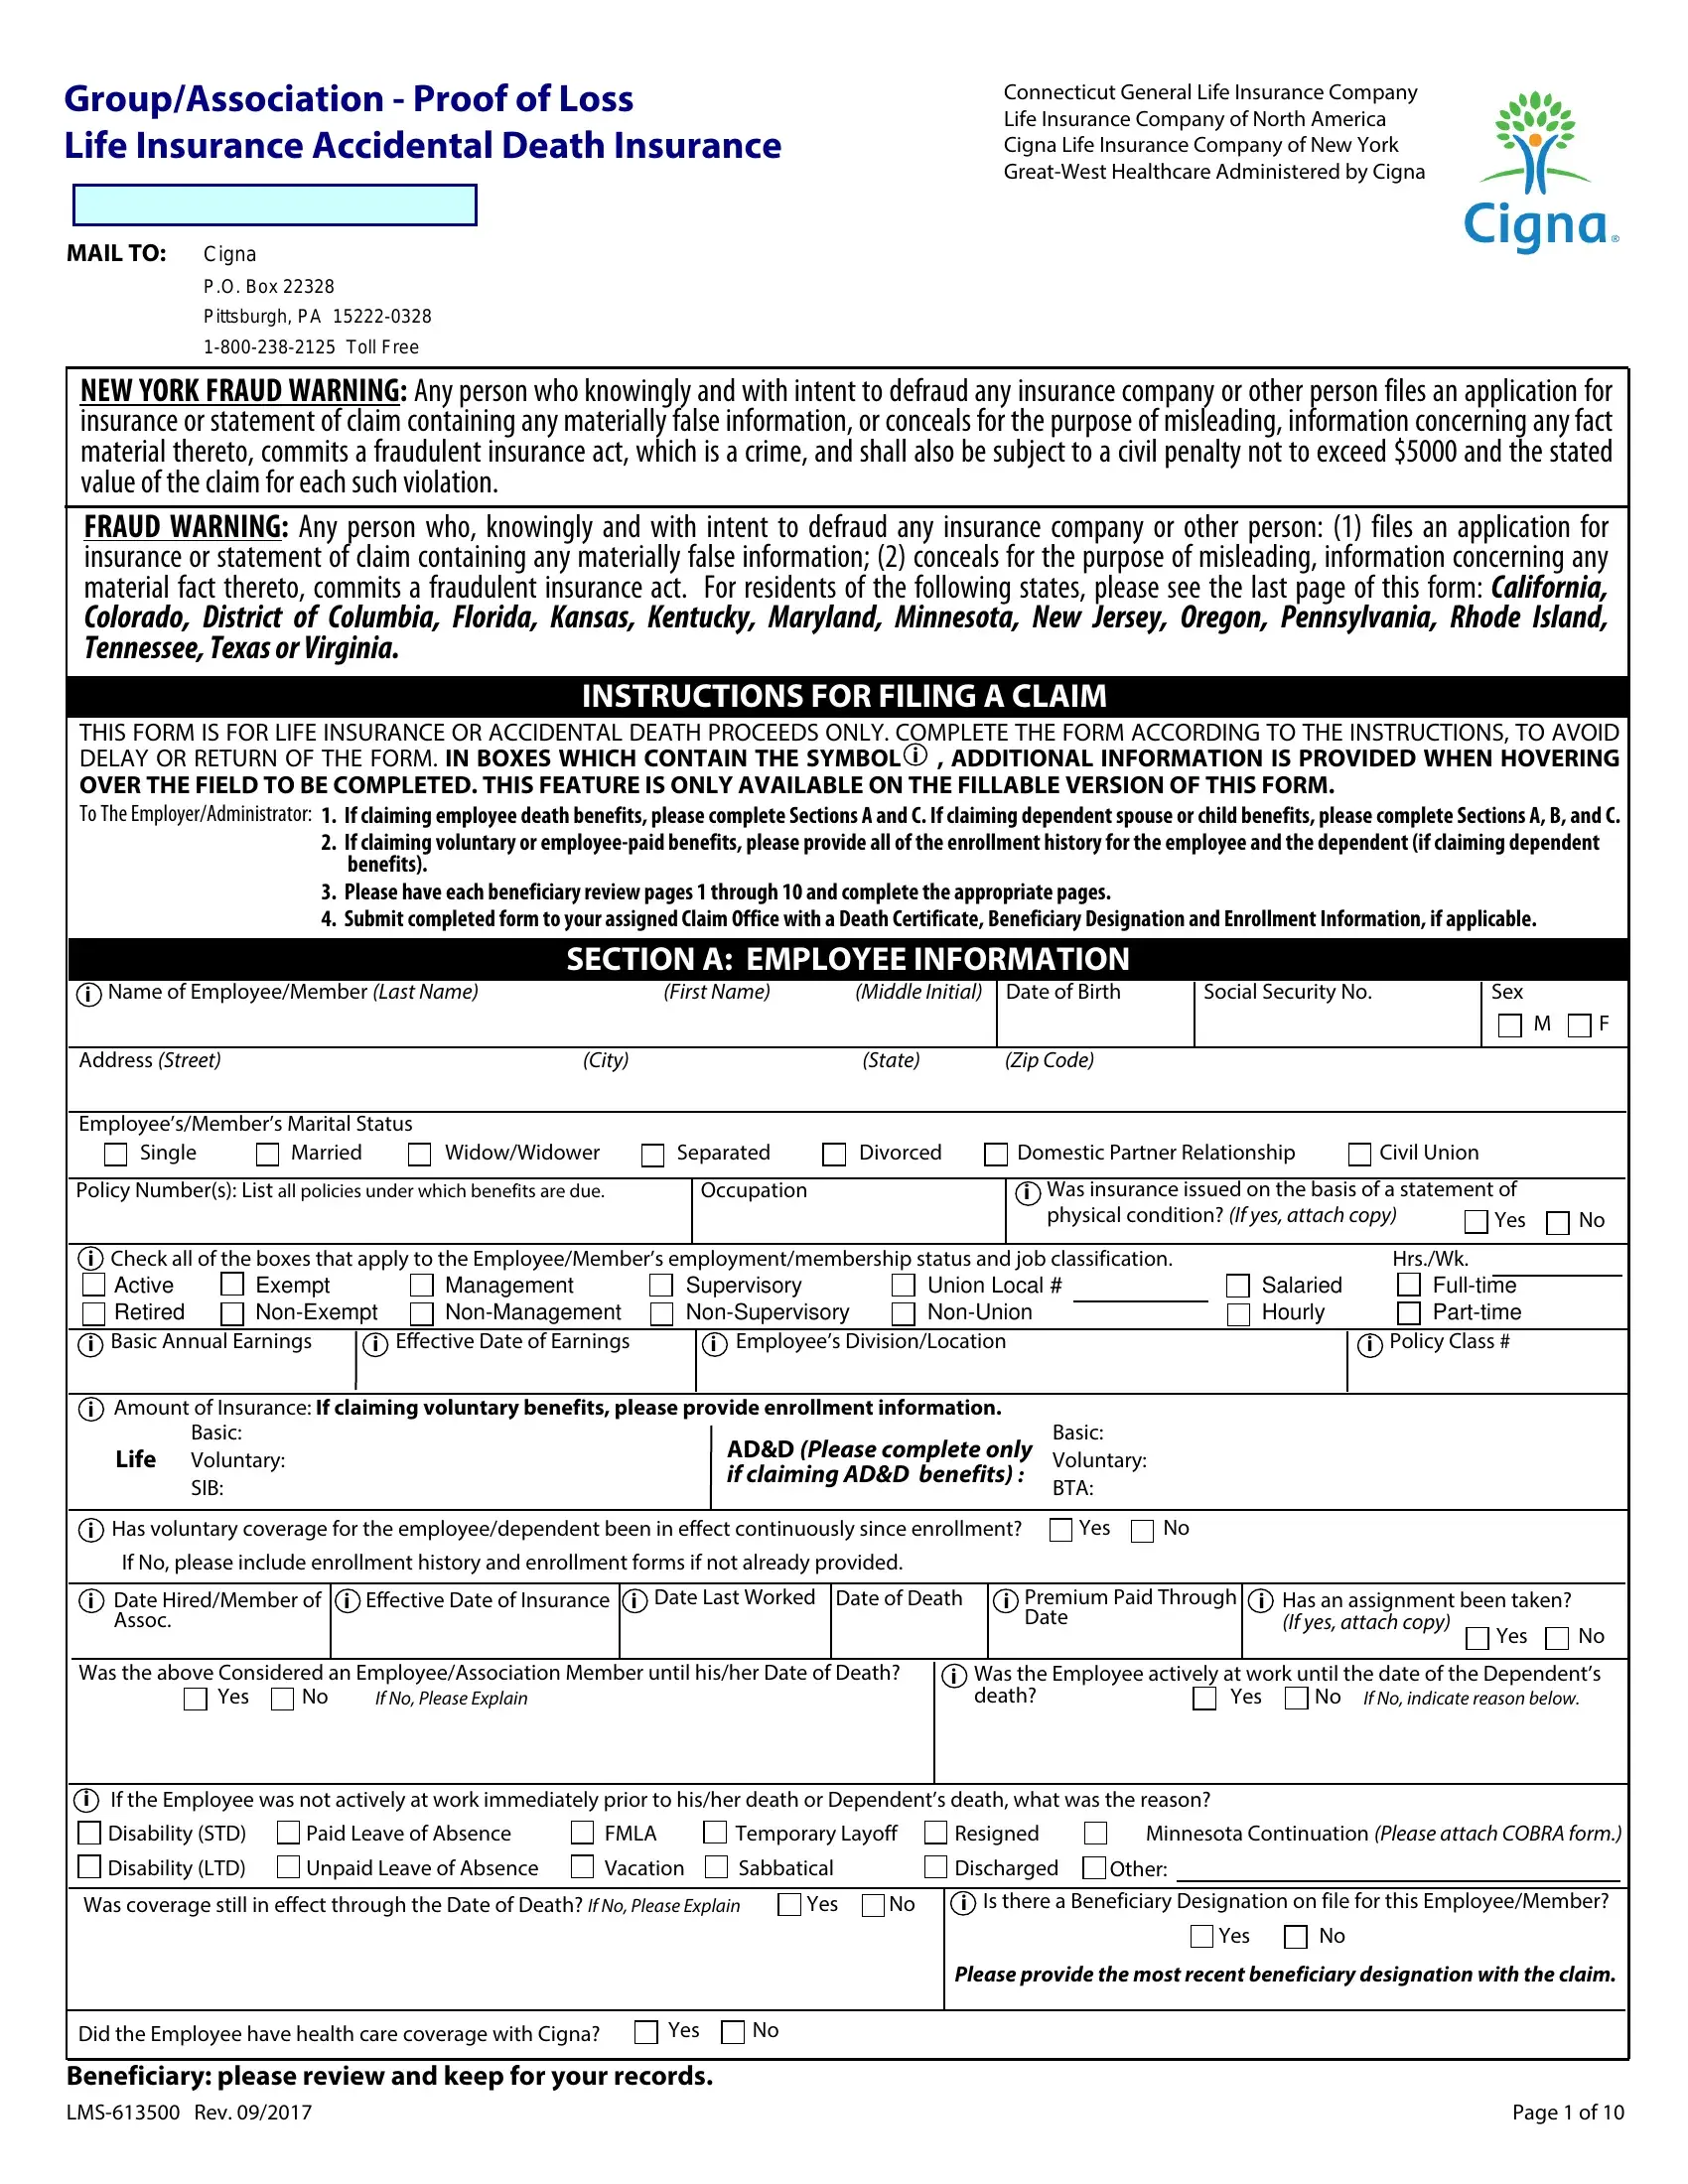
Paychex supplemental life insurance forms are the essential documents used by employees to apply for, manage, or change additional life insurance coverage beyond the basic policy provided by their employer. These forms facilitate the communication between the employee, the employer's HR department, the Paychex Flex administration portal, and the third-party insurance carrier to ensure accurate coverage and payroll deductions.
Navigating the landscape of employer-sponsored benefits often involves a significant amount of paperwork and digital data entry. As of 2026, Paychex continues to streamline these processes through its integrated HRIS (Human Resources Information System), Paychex Flex. However, the complexity of supplemental life insurance—which often involves medical underwriting and specific legal designations—means that understanding the nuances of these forms is critical for ensuring your family’s financial security.
This guide provides an in-depth analysis of the various Paychex supplemental life insurance forms you may encounter, the requirements for completing them, and the common pitfalls to avoid during the enrollment process.
What is Supplemental Life Insurance via Paychex?
Most modern employers provide a "Basic Life Insurance" policy at no cost to the employee. This is typically a flat amount, such as $25,000, or a multiple of the employee's salary (e.g., 1x annual earnings). While valuable, this basic coverage is often insufficient for individuals with mortgages, children, or significant debt.
Supplemental life insurance is an optional policy that employees can purchase through their employer’s group plan. Because it is a group policy, the rates are often lower than those found on the individual market. Paychex acts as the benefits administrator, meaning they handle the technology that hosts the forms, the data transfer to the insurance carrier (such as Unum, New York Life, or The Hartford), and the automated payroll deductions that pay the premiums.
When you interact with "Paychex forms," you are often interacting with a digital interface that populates a formal document for the insurance carrier. Understanding this relationship is the first step in successfully managing your benefits.
Essential Paychex Insurance Forms and Documents
The following table summarizes the primary forms associated with supplemental life insurance and their specific functions within the Paychex ecosystem.
| Form Name | Purpose | Primary Requirement | Triggering Event |
|---|---|---|---|
| Enrollment/Change Form | Selects coverage amounts and authorizes payroll deductions. | Basic personal info and coverage election. | New hire onboarding or Open Enrollment. |
| Evidence of Insurability (EOI) | Provides medical history for underwriting approval. | Detailed health questionnaire; sometimes a physical. | Requesting coverage above the "Guaranteed Issue" limit. |
| Beneficiary Designation | Defines who receives the death benefit. | Legal names, SSNs, and birthdates of beneficiaries. | Initial enrollment or life changes (marriage/divorce). |
| Portability/Conversion Form | Transfers coverage to an individual policy after leaving a job. | Timely submission (usually within 31 days of termination). | Employment termination or loss of eligibility. |
| Claim Form | Initiates the payout process after a death. | Death certificate and claimant identification. | Death of the insured party. |

Navigating the Digital Enrollment Form in Paychex Flex
In 2026, the majority of supplemental life insurance "forms" are completed digitally through the Paychex Flex portal. When you log in during your Open Enrollment period, the system guides you through a wizard-style interface.
Steps to Complete the Digital Enrollment
- Access the Benefits Segment: From the Paychex Flex dashboard, navigate to the "Benefits" tab and select "Health & Welfare."
- Select Supplemental Life: You will see your basic coverage listed. Choose the option to "Add" or "Increase" supplemental coverage.
- Choose Increments: Coverage is usually offered in increments of your salary (e.g., 1x, 2x, 3x) or flat dollar amounts (e.g., $10,000 units). The form will dynamically calculate the monthly or per-pay-period cost based on your current age.
- Confirm Attestations: You must check boxes confirming you understand the terms, that you are "actively at work" on the date of enrollment, and that you authorize the necessary payroll deductions.
The "form" produced by this process is a digital record that serves as a legal contract between you and the insurer, facilitated by Paychex.
Decoding the Evidence of Insurability (EOI) Form
Perhaps the most misunderstood document in the benefits package is the Evidence of Insurability (EOI), also known as a Statement of Health.
When is an EOI Required?
You are not always required to prove your health status. Most plans have a Guaranteed Issue (GI) limit. For example, a plan might allow you to buy up to $150,000 in coverage without answering any health questions. However, if you want $300,000 in coverage, you must fill out the EOI form for the remaining $150,000.
An EOI is also typically required if you decline coverage when you are first hired but decide to sign up later during a standard Open Enrollment period. This prevents "adverse selection," where people only sign up for insurance when they know they are sick.
Components of the EOI Form
- Medical History: You will be asked about chronic conditions (diabetes, heart disease, etc.), recent hospitalizations, and tobacco use.
- Physician Information: You must provide contact details for your primary care provider.
- Authorization to Release Information: This allows the insurance carrier to request medical records if the questionnaire identifies potential risks.
If you are filling this out via Paychex, the system may provide a link to the carrier’s specific EOI portal. It is vital to complete this step promptly; if the EOI is not approved, your coverage will remain capped at the Guaranteed Issue limit, or you may be denied supplemental coverage entirely.
Managing Beneficiary Designation Forms
The Beneficiary Designation form is a legal document that overrides a will. If your will says your estate goes to your sibling, but your Paychex beneficiary form says it goes to your ex-spouse, the insurance company is legally obligated to pay the ex-spouse in most jurisdictions.
Primary vs. Contingent Beneficiaries
The form will ask you to name a Primary Beneficiary. This is the first person or entity in line to receive the payout. You should also name a Contingent Beneficiary, who receives the benefit only if the primary beneficiary is deceased at the time of your death.
Distribution Percentages
If you name multiple beneficiaries (e.g., three children), the form requires you to specify the percentage each will receive. Ensure these total exactly 100%. Paychex forms generally validate this data in real-time, but paper forms are prone to errors that can delay payouts for months.
The Importance of SSNs
While some older forms allowed you to simply name "my children," modern Paychex forms require Social Security Numbers and dates of birth for all beneficiaries. This is to ensure the insurance carrier can accurately locate the individuals and comply with "Unclaimed Property" laws.
Costs and Payroll Deduction Calculations
One of the primary benefits of using Paychex for supplemental life insurance is the automated calculation of premiums. The forms you sign authorize the "Benefits Bridge"—the logic that connects your insurance election to the payroll engine.
Age-Banded Rates
Supplemental life insurance rates are almost always "age-banded." This means your premium increases as you enter new age brackets (e.g., 30-34, 35-39). The Paychex system uses your date of birth from your employee profile to update these rates automatically. When you sign the enrollment form, you are agreeing to these future adjustments.
Tax Implications (Section 79)
Under IRS Section 79, the value of employer-provided life insurance over $50,000 is considered a taxable benefit (imputed income). However, because supplemental life insurance is usually paid for by the employee with after-tax dollars, you typically do not pay taxes on the premiums or the death benefit. Always verify the "tax class" of the deduction on your Paychex pay stub to ensure it matches the form you signed.
Common Mistakes and Troubleshooting
Errors on supplemental life insurance forms can lead to a "denial of claim" or a lapse in coverage.
- Missing the "Actively at Work" Requirement: Most forms stipulate that you must be actively working (not on long-term disability or an extended leave of absence) for the coverage to take effect. If you sign a form while on leave, the coverage may be void.
- Incomplete EOI: If the insurance carrier requests more information after you submit an EOI and you don't respond within the 30-60 day window, they will "close the file." Your Paychex portal might show you have coverage, but the carrier’s records will show a denial.
- Naming Minors as Beneficiaries: Insurance companies cannot pay death benefits directly to minors. If you name a minor on your Paychex form without a designated trust or guardian, the court may have to appoint a representative, which can be costly and slow.
- Incorrect Salary Data: Since many supplemental plans are based on multiples of salary, ensure your "Annual Salary" field in Paychex Flex is accurate. If you received a raise but it wasn't updated in the system, your coverage amount (and premium) will be lower than expected.
What Happens When You Leave Your Job?
The Paychex supplemental life insurance forms you sign during employment are tied to your status as an active employee. If you leave the company, this group coverage typically ends on the last day of the month in which you were terminated.
To keep your coverage, you must look for the Portability or Conversion forms.
- Portability: Allows you to take the group policy with you at a similar rate.
- Conversion: Allows you to convert the group policy into an individual whole-life policy (usually much more expensive, but guaranteed regardless of health).
These forms are time-sensitive. Per U.S. Department of Labor guidelines, you generally have only 31 days from your last day of employment to submit these documents to the carrier. Paychex may provide these forms in your "Termination Packet," but the responsibility for submission lies with the former employee.
Frequently Asked Questions
Can I change my supplemental life insurance coverage at any time?
Generally, no. You can usually only change your coverage during the annual Open Enrollment period or within 30 days of a Qualifying Life Event (QLE), such as marriage, birth of a child, or divorce. If you experience a QLE, you will need to submit a "Life Event" form through Paychex Flex and may still be subject to EOI requirements if you are increasing coverage.
Why does my Paychex Flex portal say "Pending" for my insurance?
This status almost always refers to the Evidence of Insurability process. The insurance carrier has received your request but has not yet approved your medical questionnaire. Until they move to an "Approved" status, your payroll deductions will either not start or will only cover the Guaranteed Issue portion.
Is the Paychex supplemental life insurance form the same as a will?
No. Life insurance is a non-probate asset. This means it passes directly to the named beneficiary on the Paychex form, regardless of what your will says. It is vital to keep your Paychex beneficiary designations updated independently of your legal will.
What if I cannot find the paper EOI form?
Most carriers integrated with Paychex now use electronic EOI (eEOI). Check your email (including spam) for a link from the insurance carrier (e.g., Unum or Guardian) after you finish your enrollment in Paychex Flex. If a paper form is required, it can usually be downloaded from the "Documents" or "Forms" library within the Paychex Flex portal.
Can I name my estate as a beneficiary on the form?
Yes, but it is generally discouraged. Naming your estate means the death benefit must go through the probate court process, which can take months and subjects the money to creditors. Naming individuals or a living trust allows for a much faster, private payout.
Final Recommendations
Understanding Paychex supplemental life insurance forms is about more than just checking boxes; it is about ensuring that the financial bridge you are building for your dependents is legally sound.
To ensure your coverage is active and accurate:
- Audit your Paychex Flex profile annually during Open Enrollment.
- Review your beneficiaries after every major life change.
- Complete any EOI requests immediately to avoid a lapse or denial of coverage.
- Keep a digital copy of your "Benefit Summary" and any submitted EOI forms in a safe place outside of your work computer.
If you are unsure about the specific limits or carrier for your plan, contact your company’s HR administrator or the Paychex Employee Support line for clarification. Taking these steps today ensures that your supplemental coverage functions exactly as intended when it is needed most.
Image Gallery
Select an image to open it in a new tab.
Lars Thomsen
Global Labor Markets and Economic Strategy Editor
