Where to Go for Financial Advice: A Comprehensive Guide to Professionals and Platforms
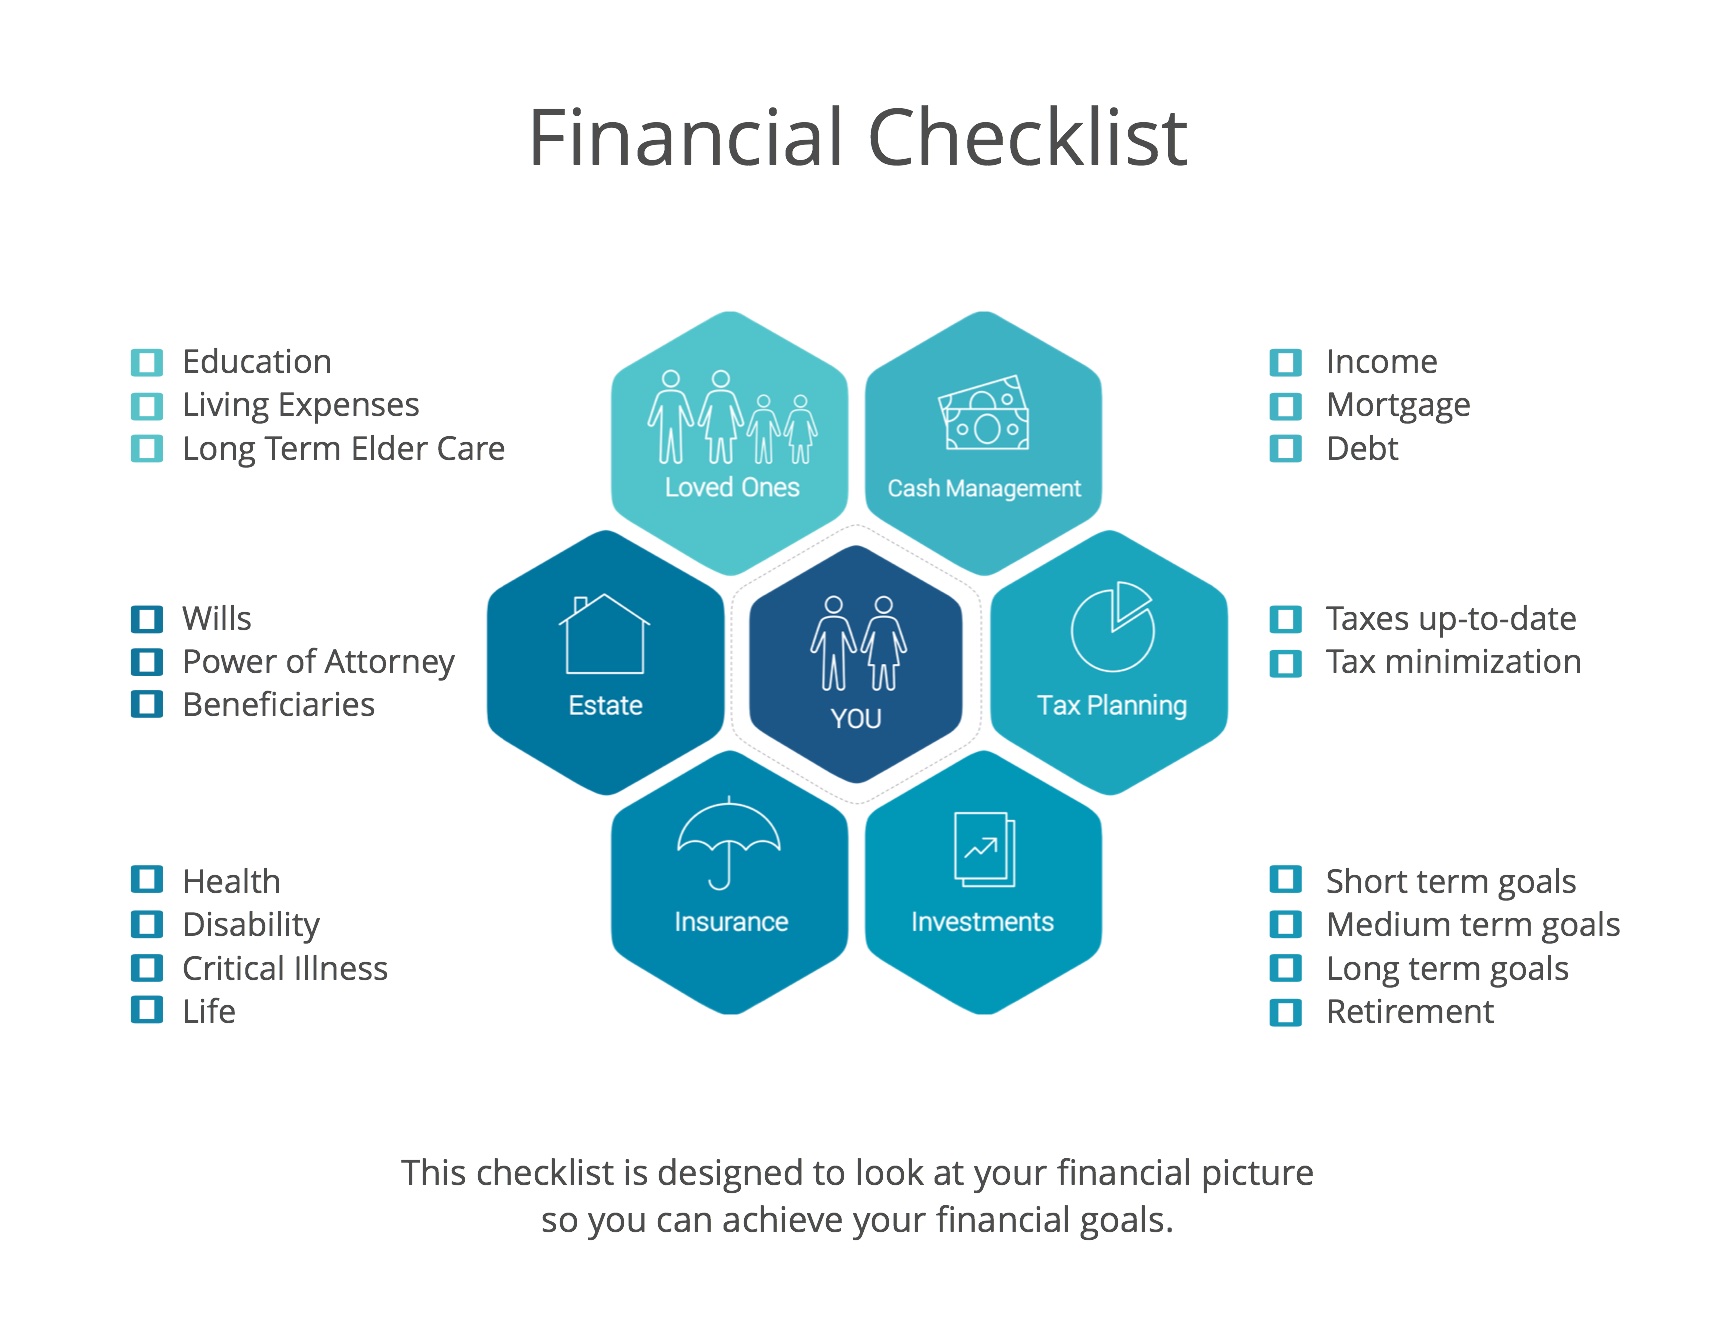
Determining where to go for financial advice depends on your specific goals, the complexity of your assets, and your preferred level of involvement. You can seek guidance from Certified Financial Planners (CFPs) for holistic planning, Registered Investment Advisers (RIAs) for fiduciary portfolio management, or robo-advisors for automated, low-cost investment strategies.
The landscape of financial services in 2026 is more diverse than ever, blending high-touch human expertise with sophisticated algorithmic tools. Navigating this environment requires understanding the distinct roles of different providers, their legal obligations to you, and how their compensation models might influence the advice you receive. This guide breaks down the primary avenues for financial guidance to help you make an informed decision for your unique situation.
Assessing Your Financial Advice Needs
Before searching for a provider, you must categorize the type of help you require. Financial advice is not a monolithic service; it ranges from simple "set-it-and-forget-it" investment management to complex estate planning and tax mitigation strategies.
Short-Term vs. Long-Term Guidance
If you are looking to resolve a specific issue—such as how to allocate your 401(k) or how to pay down student loan debt—you may only need a one-time consultation or a project-based engagement. Conversely, if you are planning for a multi-decade retirement, managing a significant inheritance, or navigating business succession, a long-term relationship with a wealth management firm is more appropriate.
Holistic Planning vs. Investment Management
Many people use the terms "financial advisor" and "investment manager" interchangeably, but they represent different scopes of work.
- Investment Management: Focuses primarily on your portfolio—asset allocation, risk tolerance, and rebalancing.
- Holistic Financial Planning: Includes investment management but also encompasses insurance needs, tax planning, retirement cash flow analysis, estate documentation, and even charitable giving.
In 2026, the trend has shifted toward holistic planning, as automated tools have commoditized basic investment management. Most modern human advisors now justify their fees through comprehensive lifestyle planning rather than just picking stocks.
Where to Find Professional Human Advice
Human advisors remain the gold standard for complex financial situations that require emotional intelligence, nuanced judgment, and personalized strategy.
Certified Financial Planners (CFPs)
The Certified Financial Planner (CFP) designation is widely considered the industry standard for personal financial planning. To earn this credential, professionals must meet rigorous education and experience requirements and pass a comprehensive exam. Most importantly, CFPs are held to a fiduciary standard by the CFP Board when providing financial planning services, meaning they must act in your best interest.
You can find and verify CFP professionals through the CFP Board’s Find a CFP Professional tool. This is an ideal starting point for families, mid-career professionals, and retirees who need a comprehensive roadmap for their finances.
Registered Investment Advisers (RIAs)
RIAs are firms (or individual practitioners) registered with either the Securities and Exchange Commission (SEC) or state securities authorities. Unlike traditional "brokers," RIAs have a legal fiduciary duty to their clients under the Investment Advisers Act of 1940. This is a crucial distinction: they are legally required to put your interests ahead of their own and must disclose any potential conflicts of interest.
RIAs often charge a fee based on a percentage of assets under management (AUM), though many have moved to flat-fee or subscription models by 2026 to accommodate a wider range of clients.
Fee-Only vs. Fee-Based Advisors
Understanding how an advisor is paid is perhaps the most important step in choosing where to go.
- Fee-Only Advisors: These professionals are paid directly by you. They do not accept commissions from mutual fund companies or insurance providers. This model is designed to minimize conflicts of interest. Organizations like the National Association of Personal Financial Advisors (NAPFA) only admit fee-only practitioners.
- Fee-Based Advisors: This sounds similar but is significantly different. Fee-based advisors charge a fee to the client but may also earn commissions for selling specific financial products. While many are ethical, this structure inherently creates a conflict of interest.

Digital and Automated Advice Platforms (Robo-Advisors)
For those in the wealth-building phase or individuals with straightforward investment needs, digital platforms—commonly known as robo-advisors—offer a highly efficient and cost-effective alternative to human advisors.
The Evolution of the Robo-Advisor
By 2026, robo-advisors have evolved beyond simple portfolio rebalancing. Using advanced algorithms and, in many cases, integrated AI, these platforms now offer tax-loss harvesting, automated dividend reinvestment, and goal-based "buckets." Leading services like Betterment and Wealthfront provide a low barrier to entry, often requiring no minimum balance and charging as little as 0.25% annually.
When to Choose a Digital Platform
A robo-advisor is often the best "place to go" if:
- You are starting out: If you have less than $50,000 to invest, the fees of a human advisor might outweigh the benefits.
- You prefer a hands-off approach: If you want your investments to grow in the background without needing to attend quarterly meetings.
- You have a simple tax situation: Automated platforms are excellent at managing standard taxable brokerage accounts and IRAs.
Hybrid Models
Many traditional firms and digital platforms now offer a "hybrid" service. This provides the low-cost automation of a robo-advisor with the ability to schedule occasional video calls with a human CFP. This middle-ground approach has become the most popular choice for "HENRYs" (High Earners, Not Rich Yet) in 2026.
Specialized Advice for Specific Situations
Sometimes, a general financial advisor isn't the right destination. Certain financial tasks require specialists with specific legal or regulatory credentials.
Tax Advice: CPAs and Enrolled Agents
If your primary concern is minimizing your tax liability or handling complex filings (such as those involving international assets or business ownership), you should go to a Certified Public Accountant (CPA) or an Enrolled Agent (EA). While some CFPs are also CPAs, many financial advisors will work in tandem with your tax professional rather than replacing them. You can verify a tax professional's status through the Internal Revenue Service (IRS) Directory.
Debt and Budgeting: Credit Counselors
If you are struggling with high-interest debt or cannot manage a basic budget, a wealth manager is likely not the right fit, as they typically focus on asset growth. Instead, look for a non-profit credit counseling agency. These organizations help you create debt management plans and negotiate with creditors.
Hourly and Project-Based Advice
If you just want a professional to review your plan for two hours, look for networks like the Garrett Planning Network or the XY Planning Network. These groups specialize in "advice-only" or hourly financial planning, allowing you to pay for expertise without committing to a long-term AUM fee structure.
Comparison of Financial Advice Channels
The following table compares the primary options available in 2026 to help you narrow down your choice.
| Advice Type | Best For | Typical Cost | Fiduciary Status |
|---|---|---|---|
| Robo-Advisor | Beginners, small accounts, hands-off investing. | 0.25% - 0.40% AUM | Yes (for the algorithm) |
| Hourly CFP | Specific questions, DIYers needing a second opinion. | $200 - $500 per hour | Yes |
| Full-Service RIA | High net worth, complex tax/estate needs. | 0.75% - 1.25% AUM | Yes |
| Hybrid Platforms | Mid-career professionals wanting tech + human access. | $30 - $100/mo + AUM fee | Yes |
| Broker-Dealer | Simple product purchases (insurance, annuities). | Commissions per sale | Suitability Standard* |
*Note: While some brokers act as fiduciaries in specific capacities, they are often held to the "suitability standard," meaning the product must be appropriate for you, but not necessarily the least expensive or "best" option.
How to Verify an Advisor’s Credentials
In 2026, the ease of digital communication has unfortunately made it easier for unqualified individuals to pose as experts. You must conduct your own due diligence before sharing any financial data or moving funds.
Using BrokerCheck and IAPD
The Financial Industry Regulatory Authority (FINRA) provides a free tool called BrokerCheck. This allows you to search for the employment history, certifications, and, most importantly, the disciplinary record of any individual broker or firm.
- Visit FINRA BrokerCheck to search for individuals.
- For RIAs, use the SEC’s Investment Adviser Public Disclosure (IAPD) website.
Red Flags to Watch For
When deciding where to go for financial advice, be wary of any individual or platform that:
- Promises "guaranteed" returns: No legitimate advisor can guarantee market performance.
- Pressures you into "urgent" investments: Financial planning is a slow, deliberate process.
- Cannot explain their fee structure clearly: If you don't know how they are making money, they are making it in a way that likely doesn't benefit you.
- Asks you to make checks out to them personally: Funds should always be held by a third-party custodian (like Schwab, Fidelity, or Vanguard).
The Importance of the Discovery Process
Once you have identified a few potential advisors or platforms, the final step is the discovery meeting. Most human advisors offer a free initial consultation. Use this time to ask critical questions:
- "Are you a fiduciary at all times during our relationship?"
- "How specifically do you get paid, and do you receive any third-party incentives?"
- "What is your investment philosophy (e.g., active management vs. low-cost indexing)?"
- "How often will we meet, and what reports will I receive?"
Choosing where to go for financial advice is not a permanent decision, but it is a significant one. In 2026, the best advice usually comes from a source that aligns with your technological comfort level and the complexity of your financial life.
Frequently Asked Questions
Is it worth paying for a financial advisor if I don't have much money?
If you are just starting out, a full-service wealth manager charging a percentage of assets is likely not worth the cost. However, a one-time "project-based" meeting with an hourly CFP can be invaluable for setting up your initial budget, understanding your employer's 401(k) options, and establishing an emergency fund. For many, a robo-advisor is the most efficient starting point.
What is the difference between a fiduciary and a regular financial advisor?
A fiduciary is legally obligated to act in your best interest, even if it reduces their own compensation. A "regular" advisor (often a broker) may only be held to a "suitability" standard, which means they can recommend a product that pays them a higher commission as long as it is generally suitable for your age and risk profile. Always ask for a written fiduciary oath.
Can I get financial advice from my bank?
Yes, most major banks have wealth management divisions. However, be cautious: bank advisors are often incentivized to steer you toward the bank's proprietary products (like their own mutual funds or insurance). While convenient, these may not be the most competitive options on the market.
How has AI changed where I should go for financial advice in 2026?
AI has made high-quality financial guidance more accessible. In 2026, many apps use AI to analyze your spending patterns and suggest real-time adjustments. While AI is excellent for data analysis and budgeting, it still lacks the ability to navigate complex human emotions—such as those involving family dynamics in estate planning or the fear associated with a market crash.
Where should I go for help with my 401(k)?
Your first stop should be your HR department or the online portal of your 401(k) provider (e.g., Fidelity, Vanguard, or TIAA). Many employer-sponsored plans offer free access to basic financial counseling or managed account services. If your plan is complex, an independent CFP can provide an "outside-in" analysis of your investment choices within the plan.
Next Steps for Seeking Advice
To begin your journey, follow these three practical steps:
- Define your goal: Do you need a portfolio, a tax plan, or a debt repayment strategy?
- Choose your model: Decide between a low-cost robo-advisor for simple investing, an hourly CFP for specific questions, or a full-service RIA for ongoing management.
- Verify and Interview: Use the SEC IAPD or FINRA BrokerCheck tools to vet any professional, and interview at least two candidates to compare their approach and transparency.
Image Gallery
Select an image to open it in a new tab.


Vivian Cho
Executive IT and Emerging Technologies Reporter
