How to Find the Most Competitive Auto Insurance Prices
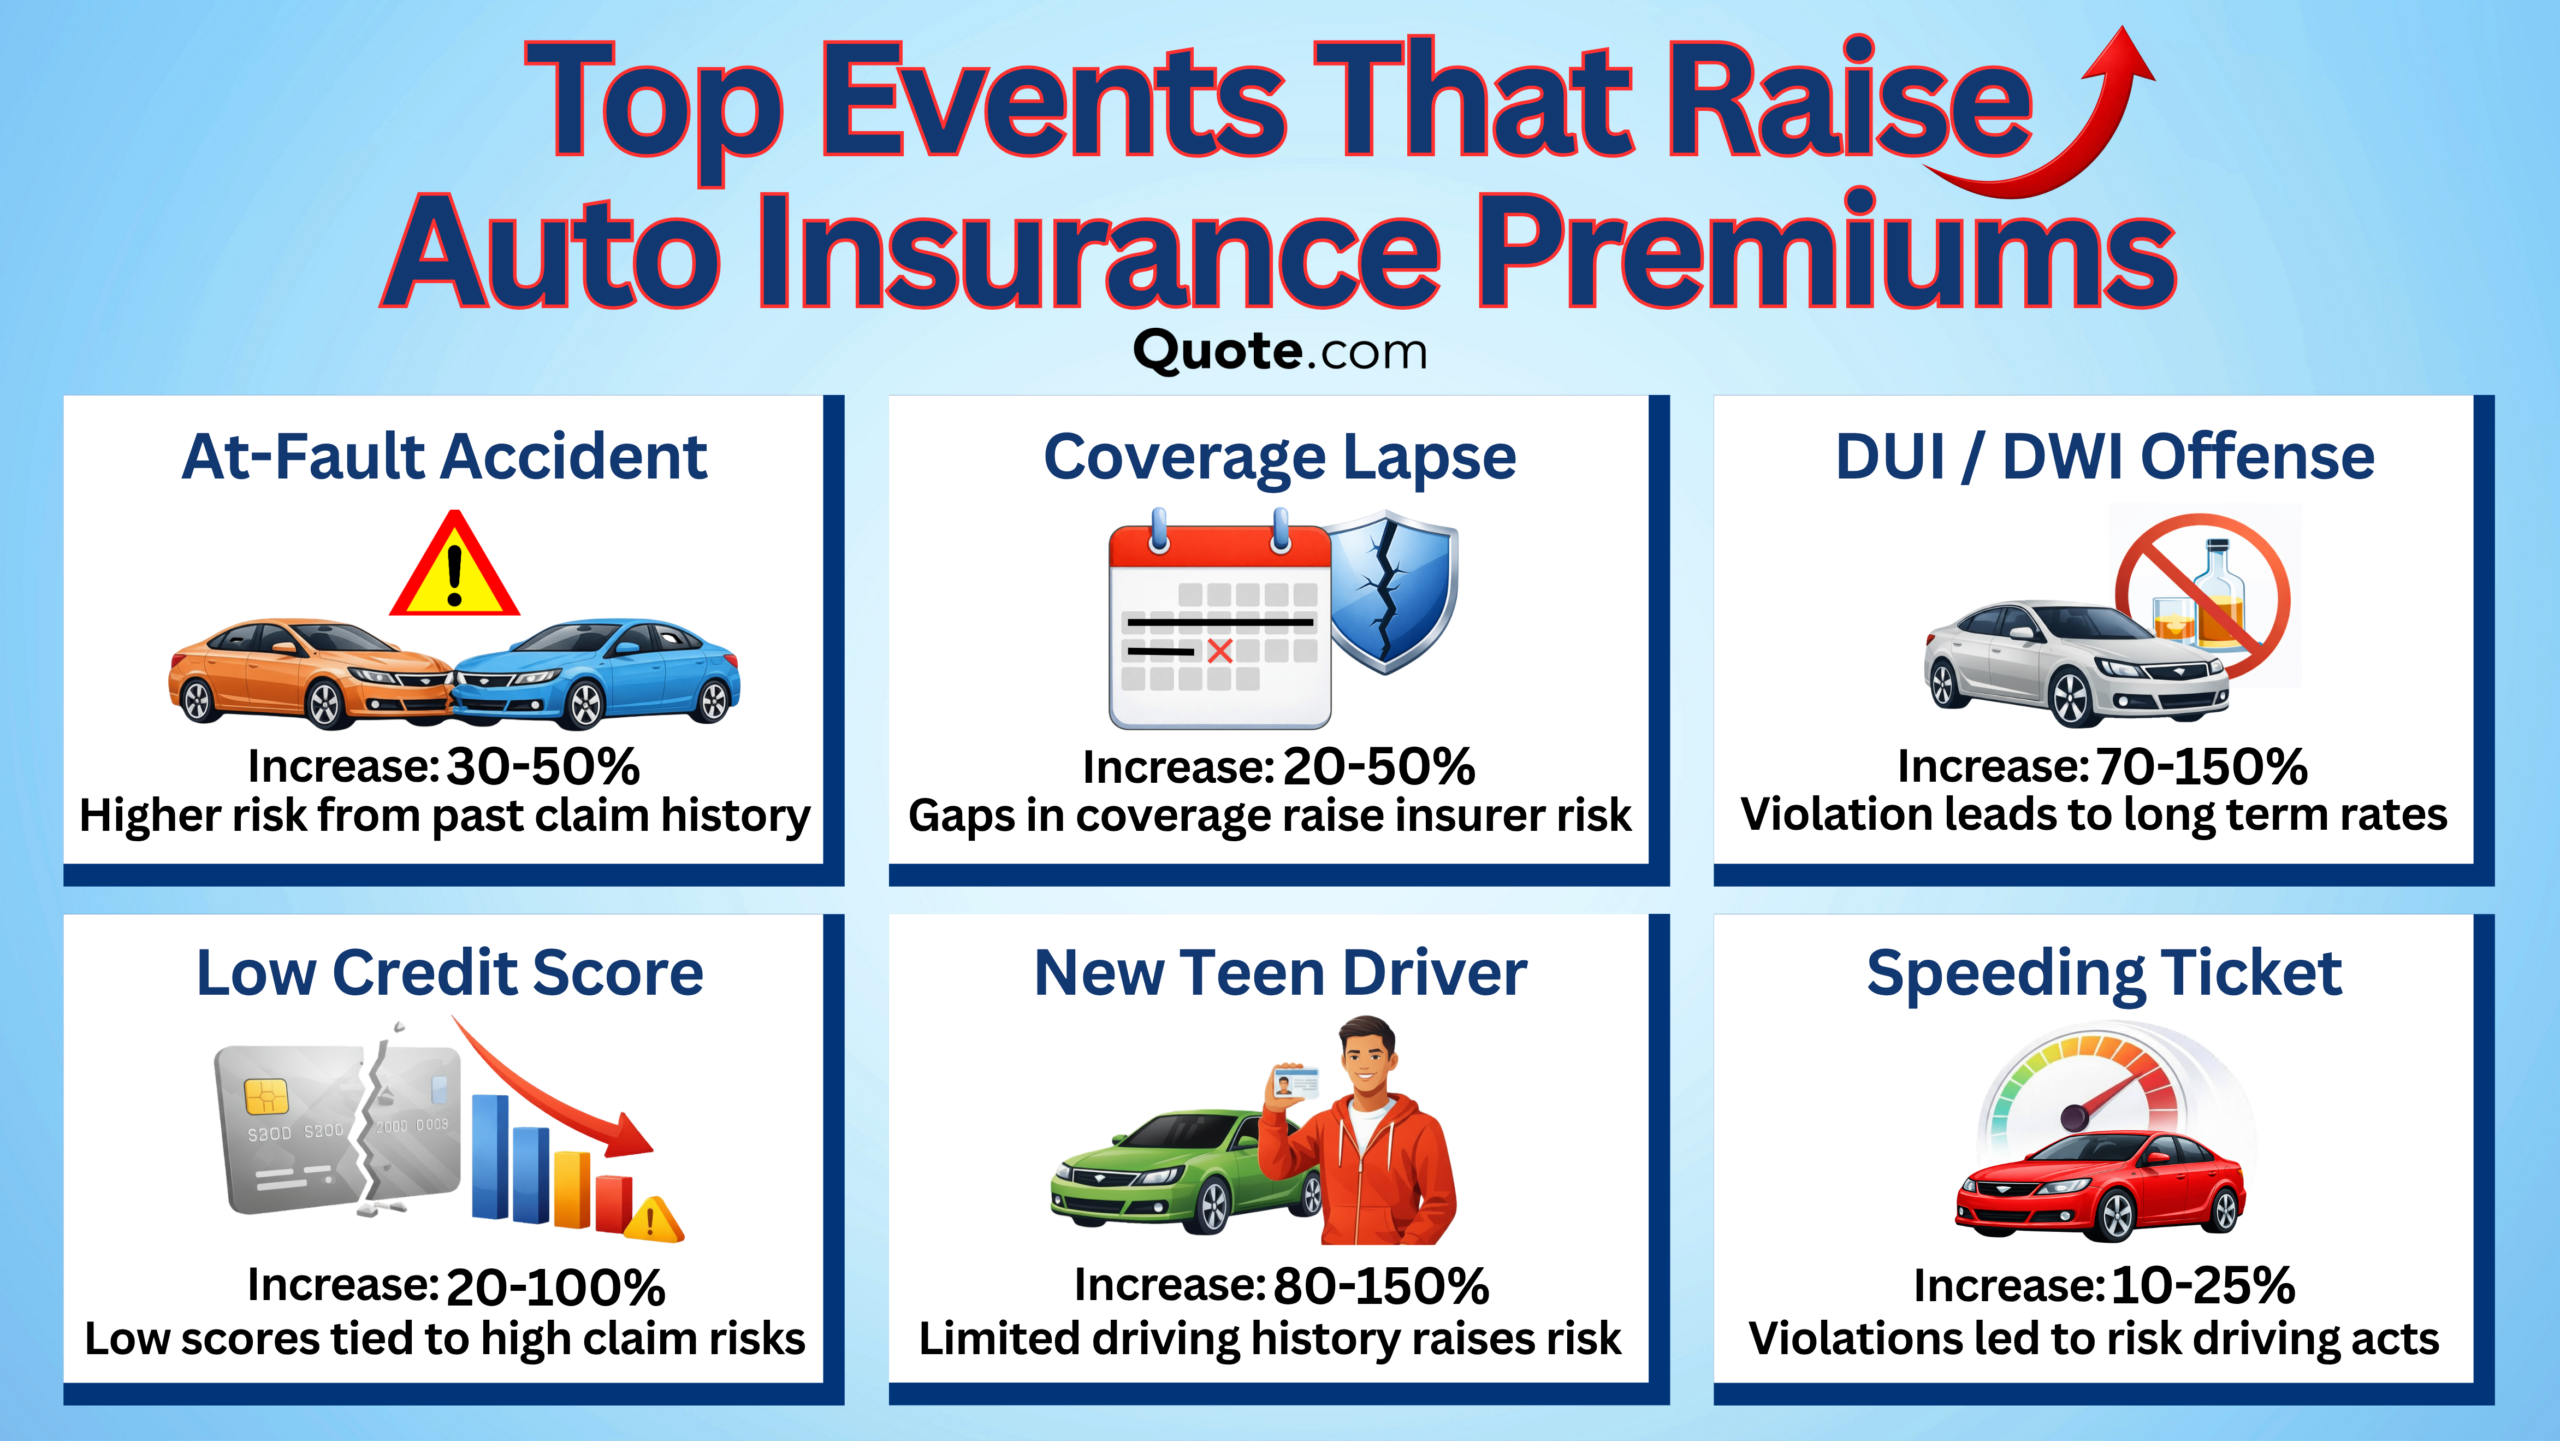
Finding the most competitive auto insurance prices requires a systematic approach involving a review of your current coverage limits, gathering multiple quotes from distinct carriers, evaluating deductible options, and utilizing available discounts for safe driving, bundling, and vehicle safety features.
Securing affordable motor vehicle coverage is an essential part of responsible vehicle ownership. Because insurance companies use complex, proprietary algorithms to evaluate risk, the cost for the exact same coverage can vary dramatically from one carrier to another. Finding the most competitive auto insurance prices is not merely a matter of picking the lowest sticker price; it involves balancing policy limits, out-of-pocket deductibles, and insurer reliability to ensure you receive true value. Whether you are shopping for a new policy or looking to lower your current recurring premium, understanding how the underwriting process works empowers you to secure the best possible rates without compromising your financial protection.
Understanding the Factors That Influence Auto Insurance Rates
Before you begin shopping for competitive coverage, it is vital to understand how insurance companies calculate premiums. Underwriters evaluate a matrix of personal and vehicular risk factors to determine the probability that a policyholder will file a claim. When you know which variables you can control and which you cannot, you can make strategic adjustments to lower your baseline risk profile in the eyes of insurers.
Personal Risk Characteristics
Your personal background remains one of the heaviest weighted categories in pricing algorithms. Insurers look closely at your driving record, noting any at-fault accidents, moving violations, or speeding tickets accumulated over the past three to five years. Additionally, your age, gender, and marital status statistical trends influence your baseline tier. In many jurisdictions, insurance companies also use a credit-based insurance score—distinct from your standard credit score—to predict the likelihood of future claims. Drivers with higher credit-based insurance scores typically qualify for more competitive pricing because statistical data suggests they are more likely to maintain their vehicles and less likely to file small claims.
Vehicle Specifications and Coverage Choices
The make, model, year, and safety ratings of your automobile directly impact your physical damage premiums. Vehicles equipped with advanced driver-assistance systems (ADAS), anti-theft devices, and high crash-test ratings often cost less to insure because the likelihood of severe injury or total loss is diminished. Furthermore, your selections regarding coverage types—such as liability limits, comprehensive, and collision—form the financial core of your policy. Opting for state-minimum liability limits reduces your immediate premium, but it exposes you to significant personal financial liability if you cause a major collision. Balancing adequate coverage with competitive pricing requires analyzing your personal asset protection needs.
Preparing to Shop for Coverage
A disorganized shopping process often leads to inconsistent quotes and poor policy choices. To secure a true apples-to-apples comparison among different insurance companies, you must compile specific documentation and define your coverage requirements before requesting estimates.
Gathering Essential Documentation
To generate accurate quotes efficiently, assemble the following documents and information for every driver and vehicle in your household:
- Driver's License Numbers: For all licensed drivers residing in your home or operating your vehicles.
- Vehicle Identification Numbers (VIN): Located on your current insurance card, vehicle registration, or the driver’s side dashboard.
- Current Decile and Mileage Data: Your approximate annual mileage and daily commute distance.
- Driving History: Details regarding any claims, accidents, or tickets from the past five years.
- Current Policy Declarations Page: A document showing your existing coverage limits, deductibles, and premium amounts.
Determining Ideal Coverage Limits
Choosing the right coverage limits protects you from catastrophic financial loss. While purchasing only the state-mandated minimum liability insurance guarantees the lowest upfront price, it rarely provides adequate protection. Financial experts typically recommend looking beyond the minimums to safeguard your savings and future income.
| Coverage Type | Recommended Standard | Purpose |
|---|---|---|
| Bodily Injury Liability | $100,000 per person / $300,000 per accident | Pays for injuries you cause to others in an accident. |
| Property Damage Liability | $50,000 to $100,000 per accident | Pays for physical damage you cause to other vehicles or property. |
| Comprehensive & Collision | Actual Cash Value minus deductible | Covers damage to your own vehicle from collisions, theft, weather, or vandalism. |
| Uninsured/Underinsured Motorist | Match your liability limits | Protects you if you are hit by a driver with little or no insurance. |

Collecting and Comparing Multiple Quotes
The most effective method for finding competitive auto insurance prices is soliciting quotes from multiple independent and captive carriers. Relying on a single quote leaves money on the table, as pricing structures diverge significantly across the industry.
Captive Agents Versus Independent Agents Versus Direct Writers
When gathering quotes, you can choose from three primary distribution channels:
- Captive Agents: These agents represent only one insurance company (e.g., State Farm or American Family). While they possess deep knowledge of their specific company's products, they cannot shop the broader market for you.
- Independent Agents: These professionals represent multiple insurance carriers. They can run quotes across several different companies simultaneously, matching you with the most competitive option available in their network.
- Direct-to-Consumer Online Portals: Many modern insurers allow you to bypass agents entirely, generating custom quotes directly on their websites or via digital aggregators.
Conducting an Apples-to-Apples Comparison
When evaluating quotes, ensure that every policy configuration matches precisely. If Carrier A quotes you with a $500 deductible and $250,000/$500,000 liability limits, you must compare it against Carrier B using those exact same figures. Changing a single deductible or coverage limit invalidates the price comparison, making it impossible to determine which company truly offers the most competitive rate.
Maximizing Discounts and Credits
Insurance companies offer a wide array of discounts that can dramatically reduce your premium. When speaking with agents or completing online applications, explicitly ask which of the following savings categories apply to your household:
- Multi-Policy Bundling: Combining your auto insurance with homeowners, renters, or umbrella policies usually triggers a substantial multi-policy discount from the same carrier.
- Multi-Car Discount: Registering and insuring more than one vehicle under the same household policy reduces the per-vehicle administrative cost for the insurer.
- Safety and Anti-Theft Equipment: Factory-installed safety features, passive restraints, anti-lock brakes, and verified tracking or alarm systems can lower comprehensive and collision rates.
- Good Driver and Defensive Driving Discounts: Maintaining a clean driving record for three to five years, or voluntarily completing an approved defensive driving course, often qualifies you for percentage-based rate reductions.
- Telematics and Usage-Based Programs: Enrolling in smartphone applications or plugging small tracking devices into your car's diagnostic port allows insurers to monitor your actual driving habits—such as speed, braking, and phone distraction—offering deep discounts for low mileage and safe driving behaviors.
Evaluating Insurer Reliability and Financial Strength
A low price loses its appeal if the insurance company fails to pay out claims fairly or struggles with financial solvency. Before finalizing a policy with the cheapest provider, verify the company's background to ensure long-term stability and quality customer service.
Checking Financial Ratings
Independent rating agencies evaluate the financial health and claims-paying ability of insurance institutions. Look up prospective carriers on platforms such as A.M. Best, Demotech, or Standard & Poor's. Selecting an insurer with a strong financial strength rating (such as "A" or higher) ensures the company maintains adequate capital reserves to handle large-scale catastrophe claims without defaulting.
Reviewing Customer Satisfaction and Claims Handling
Price is only one component of the consumer experience. Research customer satisfaction indexes, such as those published annually by J.D. Power, to gauge how efficiently a carrier handles claims, resolves disputes, and treats policyholders. Reading independent consumer reviews and checking state insurance commissioner complaint ratios can also reveal whether a low-cost provider maintains a reputation for denying legitimate claims or dragging out payout timelines.
Common Mistakes to Avoid When Shopping for Auto Insurance
Navigating the insurance market involves several common pitfalls that can cost you money or leave you dangerously underinsured. Awareness of these missteps helps protect your financial interests:
- Prioritizing Price Over Coverage: Selecting the absolute cheapest policy without verifying liability limits or exclusions can leave you exposed to ruinous out-of-pocket costs after an accident.
- Failing to Update Personal Information: Neglecting to inform your insurer about life changes—such as a change in your daily commute distance, moving to a safer neighborhood, or a youthful driver moving out of the home—can cause you to miss out on earned discounts.
- Allowing Coverage Lapses: Even a brief lapse in insurance coverage signals high risk to underwriters, driving up your future premiums significantly when you attempt to reinstate a policy.
- Setting Unrealistic Deductibles: Choosing a high deductible (e.g., $1,000 or $2,000) to lower your monthly premium is counterproductive if you do not have sufficient emergency savings to cover that out-of-pocket expense in the event of a sudden claim.
Frequently Asked Questions
How often should I shop around for auto insurance?
You should review and compare auto insurance quotes at least once a year, or whenever you experience a major life event. Significant milestones—such as getting married, buying a new vehicle, moving to a different ZIP code, adding a teenage driver, or improving your credit score—can alter your risk profile and make different insurance carriers more competitive than your current provider.
Do speeding tickets affect my auto insurance rates permanently?
No, speeding tickets and minor moving violations do not affect your rates permanently. In most states, moving violations remain on your motor vehicle record and impact your insurance premiums for three to five years. Once that statutory period passes, the violation drops off your record, and your rates should naturally adjust downward assuming you maintain a clean driving record.
Will filing a comprehensive claim for weather damage raise my rates?
Whether a comprehensive claim raises your rates depends on the specific underwriting rules of your insurance company and the nature of the incident. Claims resulting from "acts of God" or weather events outside your control—such as hail damage, tree branches falling, or comprehensive glass breakage—frequently have less impact on your rates than at-fault collision claims, though frequent claims of any type can trigger underwriting reviews.
What is the difference between collision and comprehensive coverage?
Collision coverage pays for damage to your vehicle when it collides with another vehicle or object, such as a guardrail, tree, or building, regardless of who is at fault. Comprehensive coverage protects your vehicle against non-collision incidents, including theft, vandalism, fire, animal strikes (like hitting a deer), and weather events such as floods, hail, or windstorms.
Can I change my auto insurance policy in the middle of a term?
Yes, you can change or cancel your auto insurance policy at any time during your policy term. Most insurance companies will refund the unused portion of your premium on a prorated basis if you cancel early. However, before switching providers mid-term, verify whether your current insurer charges a nominal cancellation fee, and ensure your new policy is active before your old one terminates to prevent any coverage lapses.
Next Actions for Securing Your Policy
Begin your search today by gathering your current policy declarations page, vehicle identification numbers, and driver's license details. Contact at least three distinct insurance providers or consult an independent insurance agent to run parallel quotes using identical coverage limits and deductibles. Evaluate the resulting estimates alongside each carrier's financial stability ratings, and select the policy that provides robust protection at the most competitive price point.
Image Gallery
Select an image to open it in a new tab.
Mateo Castillo
Decentralized Finance and E-Payments Strategist
