Average Cost of Life Insurance Calculator with Age: Estimating Your Premiums in 2026

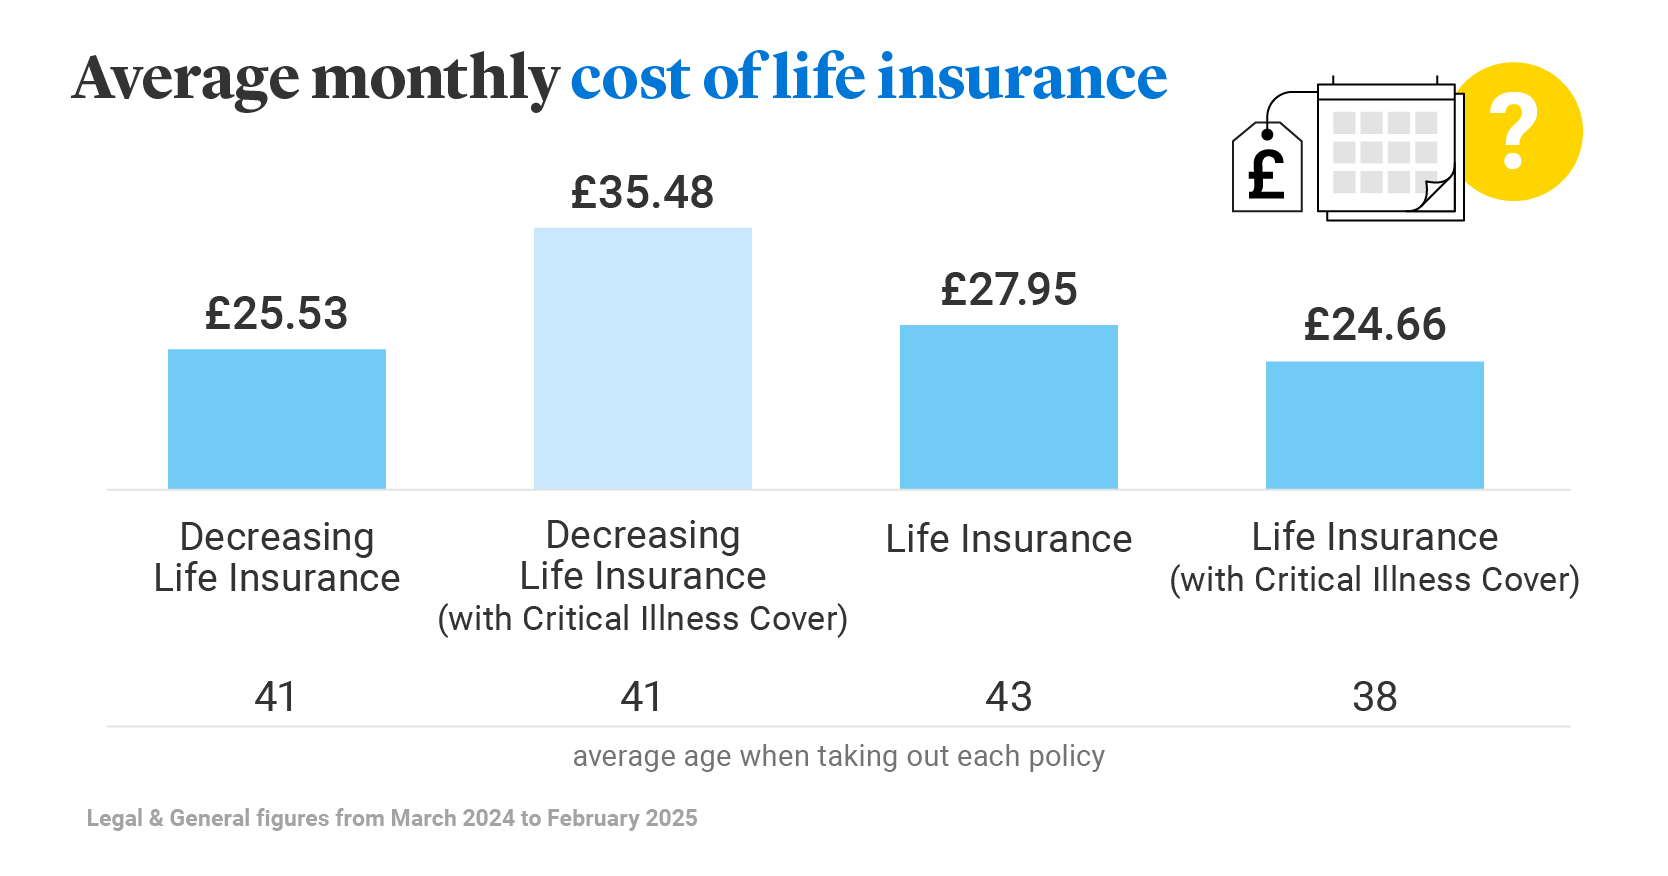
In 2026, the average cost of life insurance is primarily determined by your age at the time of application, with premiums for a healthy 30-year-old typically ranging from $20 to $35 per month for a $500,000 20-year term policy. As you age, these costs increase exponentially; by age 50, that same policy could cost $75 to $110 per month, reflecting the higher statistical risk of mortality.
Life insurance is a foundational component of a robust financial plan, yet many consumers struggle to estimate their potential costs before speaking with an agent. Utilizing an average cost of life insurance calculator with age as the primary variable allows you to benchmark quotes and determine how much coverage fits your budget. Because life insurance companies are in the business of assessing risk, age is the most significant factor they use to calculate your "mortality charge."
The Relationship Between Age and Actuarial Risk
To understand how an age-based life insurance calculator functions, one must first understand the concept of actuarial risk. Insurance companies employ actuaries to analyze massive datasets, including the Social Security Administration’s Period Life Table, to predict the likelihood of a policyholder passing away during the policy term.
As you get older, the statistical probability of death increases. Consequently, the insurance company must collect more premiums in a shorter amount of time to offset the eventual payout. In your 20s and early 30s, the "slope" of premium increases is relatively flat. However, once you cross the age of 45 or 50, the curve steepens significantly. In 2026, waiting just one year to purchase a policy in your 50s can result in a permanent premium increase of 8% to 12% for the life of the policy.
Age-Nearest vs. Age-Last Birthday
When using a calculator, it is vital to know which "age" the insurer uses.
- Age-Last Birthday: This is your actual chronological age.
- Age-Nearest Birthday: Many insurers use the age you are closest to. If you are 44 years and 7 months old, the "age-nearest" calculation treats you as a 45-year-old. This distinction can save or cost you hundreds of dollars over the life of a 30-year policy.
How a Life Insurance Calculator Uses Age to Determine Costs
An average cost of life insurance calculator with age doesn't just look at a single number; it processes a combination of data points to generate an estimate. In the 2026 insurance market, these algorithms have become more sophisticated, incorporating "accelerated underwriting" data to provide instant quotes.
Input Variables
- Current Age: The baseline for the mortality risk.
- Gender: Statistically, women have longer life expectancies than men. Therefore, a 40-year-old woman will almost always pay less than a 40-year-old man for the same coverage.
- Term Length: The duration of the coverage (e.g., 10, 20, or 30 years). The older you are, the more expensive long terms become.
- Coverage Amount (Death Benefit): The total sum paid to beneficiaries.
- Health Class: Most calculators ask for a self-assessment (Preferred Plus, Preferred, Standard, or Substandard).
By 2026, the delta between a "Preferred Plus" and "Standard" rating has widened. An individual who is 50 but in peak physical condition may pay less than a 40-year-old with chronic health issues like Type 2 diabetes or uncontrolled hypertension.

Average Monthly Cost Estimates by Age (2026 Data)
The following table provides estimated monthly premiums for a $500,000 20-year Term Life Insurance policy. These figures represent "Preferred" health status for non-smokers.
| Age | Estimated Monthly Cost (Male) | Estimated Monthly Cost (Female) | 10-Year Total Premium (Avg) |
|---|---|---|---|
| 25 | $18.50 | $15.75 | $2,055 |
| 30 | $21.25 | $18.90 | $2,409 |
| 35 | $26.80 | $22.40 | $2,952 |
| 40 | $38.15 | $32.60 | $4,245 |
| 45 | $59.40 | $48.20 | $6,456 |
| 50 | $92.75 | $74.50 | $10,035 |
| 55 | $154.30 | $118.90 | $16,392 |
| 60 | $265.00 | $195.40 | $27,624 |
Note: These are estimates for educational purposes. Actual rates are determined after a full medical underwriting process or a simplified issue review.
Beyond Age: Factors That Influence the Calculator's Output
While age is the primary lever, several secondary factors can cause the "average" cost to deviate significantly. If you are using a calculator to plan your 2026 finances, consider these variables:
The "Smoker's Multiplier"
Tobacco use remains the single most expensive lifestyle factor in life insurance. Regardless of age, a smoker will typically pay 200% to 400% more than a non-smoker. For a 40-year-old, this could mean the difference between a $40 monthly payment and a $160 monthly payment. Most calculators require you to disclose tobacco or nicotine use (including vaping) to provide an accurate estimate.
Policy Type: Term vs. Whole Life
The "average cost" for life insurance changes drastically if you switch from Term to Whole Life.
- Term Life: Covers you for a specific period. It is the most affordable because most policies expire before a claim is ever made.
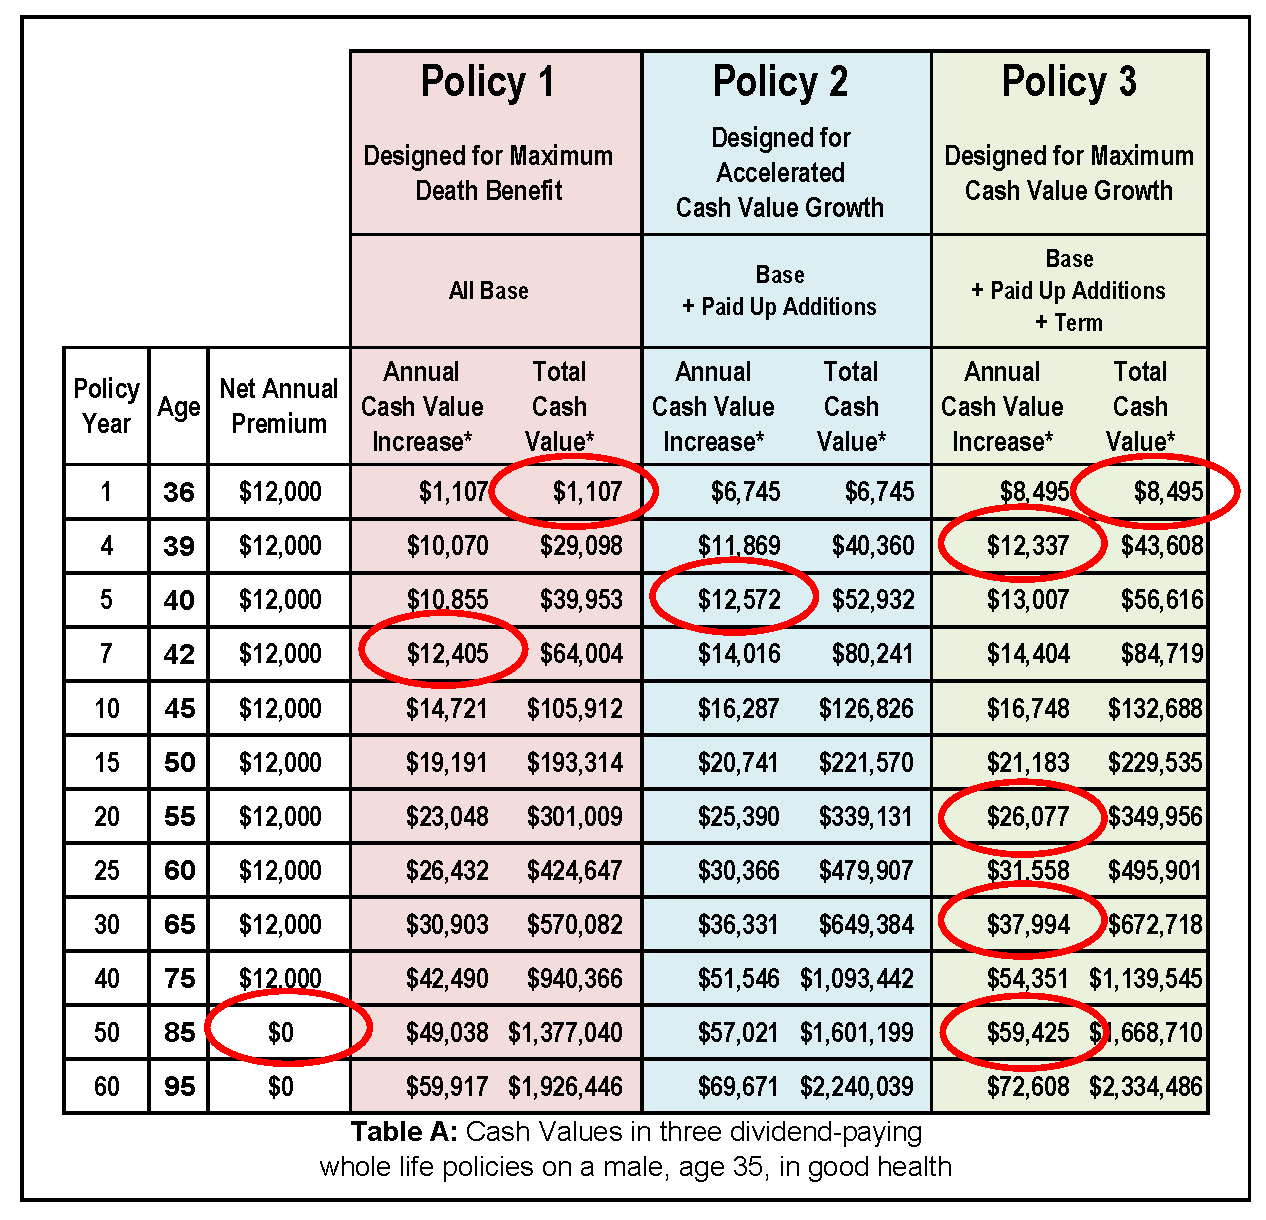
- Whole Life: Provides permanent coverage and includes a cash value component. Because a payout is guaranteed eventually (as long as premiums are paid), a 30-year-old might pay $300 a month for a Whole Life policy that would only cost $25 a month in Term coverage.
Health and Bio-Data
In 2026, many insurers utilize "Big Data" and clinical algorithms to assess risk. Calculators often ask for your Height and Weight (BMI). Being significantly outside the "Standard" BMI range can trigger a "table rating," which adds a percentage-based surcharge (e.g., Table 2 or Table B) to the base age-related premium.
Strategies to Manage Costs as You Age
If the results from an average cost of life insurance calculator with age are higher than you anticipated, there are several strategic ways to lower your premiums without sacrificing essential protection.
1. The "Ladder" Strategy
Instead of buying one large $1 million 30-year policy, you can "ladder" multiple policies. For example, a 35-year-old might buy:
- A $500,000 10-year term to cover the mortgage.
- A $500,000 20-year term to cover the children's education years. This approach ensures you have the most coverage when you need it most, while reducing the total premium load as you age and your liabilities decrease.
2. Buying While Young and Healthy
The most effective way to beat the age curve is to lock in a level-premium policy as early as possible. A Level-Premium Term policy guarantees that your monthly cost will remain the same for the duration of the term, regardless of how your health changes or how much older you get.
3. Improving Health Before Re-Applying
If you were quoted a high rate due to a specific health condition (like high cholesterol or BMI), many insurers allow you to request a "rate reduction" or "re-consideration" after one or two years if you can demonstrate improved health through medical records.
Common Mistakes When Using Online Age Calculators
Navigating life insurance pricing requires precision. Many consumers fall into traps that lead to "quote shock" once they actually apply.
- Underestimating Health Class: Most people believe they are "Preferred," but insurance companies have very strict criteria. Only about 10-15% of applicants qualify for "Preferred Plus" rates. If you have a family history of heart disease or take minor medications, it is safer to calculate costs based on "Standard" rates.
- Ignoring the Term Length Impact: A calculator might show a very low price for a 10-year term at age 50. However, if you still need coverage at age 60, buying a new policy then will be prohibitively expensive. It is often cheaper in the long run to buy a 20-year term at 50 than two consecutive 10-year terms.
- Overlooking "No-Exam" Options: In 2026, many calculators offer "No-Medical Exam" quotes. While convenient, these are sometimes slightly more expensive than fully underwritten policies because the insurer takes on more "unknown" risk.
The Role of Inflation in 2026 Premiums
While actuarial science is based on mortality, the administrative and "cost of doing business" for insurance companies is subject to inflation. By 2026, the nominal dollar amount of premiums has adjusted slightly upward compared to the early 2020s. However, the competitiveness of the digital insurance market has kept these increases in check. When using a calculator, ensure the tool is updated for the current year’s rate environment, as using data from 2020 or 2021 will likely result in an underestimate of current market prices.
Frequently Asked Questions
Does my premium increase every year as I get older?
With a Level-Premium Term or Whole Life policy, your premium stays exactly the same for the duration of the policy. The "cost with age" only applies to the age you are when you first purchase the policy. However, if you have an "Annually Renewable Term" (ART) policy, your premiums will indeed increase every year as you age.
Is there a maximum age where I can no longer use a calculator?
Most term life insurance calculators stop providing quotes after age 75 or 80. For seniors over 75, coverage options typically shift toward "Final Expense" or "Guaranteed Issue" whole life policies, which have much lower coverage limits (usually under $50,000) and higher relative costs.
Can gender-neutral pricing affect my age-based quote?
As of 2026, some jurisdictions have moved toward gender-neutral insurance pricing. However, in most of the United States, gender remains a legal and primary factor in life insurance underwriting. If you live in a region with gender-neutral mandates (like parts of the EU or specific U.S. states), your calculator results will likely reflect an average of the male and female rates.
Why did my calculator quote change after I entered my zip code?
Life insurance is regulated at the state level. Different states have different premium taxes, reserve requirements, and mortality expectations. While the "base" cost of life insurance is consistent, state-specific regulations can cause minor fluctuations in the final premium.
How much life insurance do I actually need at my age?
A common rule of thumb used in calculators is 10 to 15 times your annual income. However, your age plays a role here too; a 30-year-old with a young family and a 30-year mortgage needs significantly more coverage than a 60-year-old whose house is paid off and whose children are independent adults.
Practical Recommendation: Your Next Steps
To get the most accurate result from an average cost of life insurance calculator with age, follow these steps:
- Gather Your Health Data: Know your current height, weight, and any recent blood pressure or cholesterol readings.
- Determine Your "Insurance Age": Check if you are closer to your next birthday than your last.
- Run Multiple Scenarios: Calculate the cost for a 15, 20, and 30-year term to see where the price "breaks."
- Compare at Least Three Carriers: No two insurance companies weigh health risks the same way. One carrier may be "age-friendly" for smokers, while another offers better rates for those with a high BMI.
- Consult a Professional: Use the calculator as a baseline, but speak with an independent agent who can access the "internal" rate books of multiple companies to find the best fit for your specific profile.
By utilizing an average cost of life insurance calculator with age as a starting point, you can enter the application process with a realistic expectation of costs, ensuring your family is protected without overextending your monthly budget.
Image Gallery
Select an image to open it in a new tab.
Simon Caldwell
Enterprise Technology and Systems Editor
