
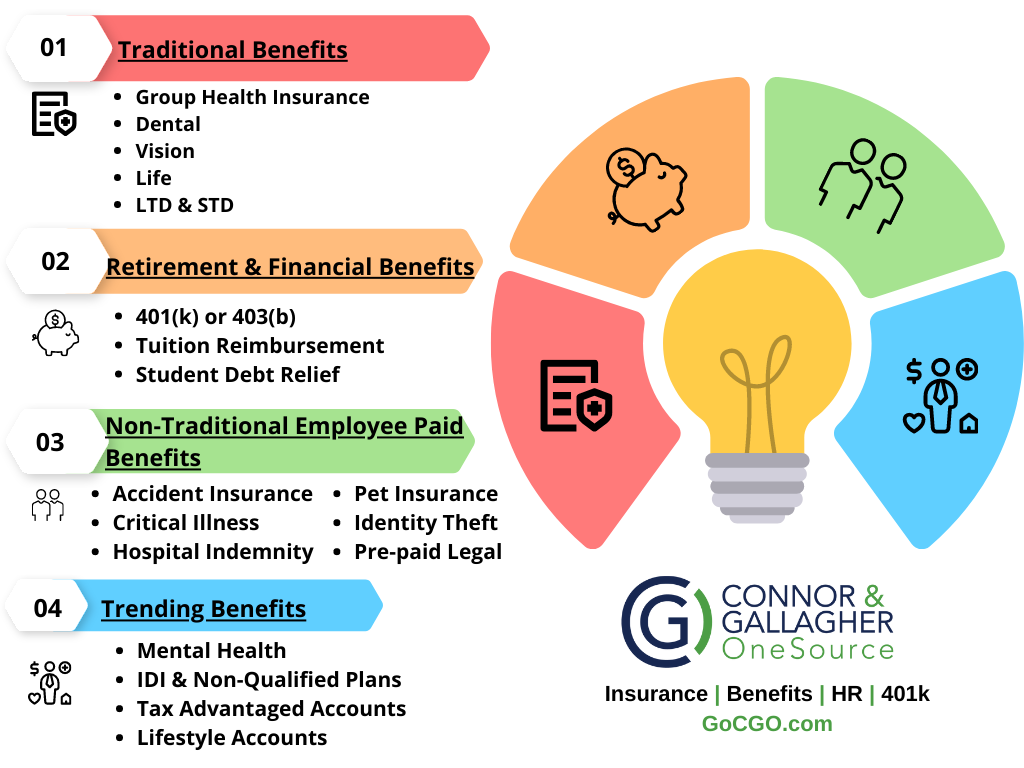
Auto insurance as an employee benefit is an employer-sponsored or endorsed arrangement that allows workers to purchase private passenger vehicle coverage, often at a discounted group rate, with the convenience of premium payments deducted directly from their payroll. While traditional group benefits typically include health insurance, dental plans, and retirement accounts, forward-thinking employers increasingly offer voluntary benefits like auto and home insurance to help employees reduce personal living expenses without adding to corporate overhead costs.
Understanding Voluntary Benefits and Auto Insurance
To fully grasp how auto insurance functions within an employment framework, it is necessary to examine the broader category of voluntary workplace benefits. Unlike core benefits—such as workers' compensation, which employers legally mandate to cover injuries sustained on the job—voluntary benefits are optional perks made available to staff. The employer acts as a facilitator rather than a direct purchaser or funder of the policy.
In a standard voluntary auto insurance arrangement, the employer partners with a commercial property and casualty insurance carrier or a specialized benefits broker. The insurance provider extends a group platform to the company's employees, featuring specialized terms, tailored customer service tiers, and, most importantly, cost-saving discounts that may not be available on the open consumer market.
Why Employers Sponsor Voluntary Auto Programs
Organizations adopt voluntary auto insurance programs to enhance their total rewards packages, aiding in employee recruitment and retention. Providing access to discounted personal lines of coverage costs the employer little to nothing in direct subsidies, yet it offers tangible financial value to the workforce. Human resources departments find that these programs support employee financial wellness, which in turn correlates with reduced workplace stress and improved productivity.
Furthermore, administering these programs has become streamlined through modern human resources information systems (HRIS) and automated payroll software. Once integrated, deductions occur automatically every pay cycle, minimizing administrative burdens for human resources personnel while establishing a seamless payment loop for the insurance carrier.
How Group Auto Insurance Differs from Individual Policies
Workers frequently wonder how an employer-sponsored auto policy differs from a standard policy purchased independently through an insurance agent or online aggregator. The underlying mechanics of the insurance contract remain largely identical: the policyholder pays a periodic premium in exchange for financial protection against vehicular collisions, liability claims, comprehensive losses (such as theft or weather damage), and uninsured motorists.
However, the administrative structure and pricing architecture differ significantly:
- Group Pricing Discounts: Insurance carriers calculate risk pools based on aggregate employer demographics, often passing down rate reductions of 5% to 15% compared to individual retail rates.
- Payroll Deduction Convenience: Rather than managing annual lump sums or monthly bills, policyholders authorize automatic deductions from each paycheck, helping them budget more effectively.
- Portability: In most cases, if an employee leaves the company, retires, or is terminated, the policy remains active. The billing mechanism simply transitions from payroll deduction to direct bill, where the individual pays the carrier directly.
- Dedicated Support Channels: Insurers offering group programs usually establish dedicated customer service hotlines and digital portals specifically for the partner company's workforce, resulting in expedited claims processing and policy adjustments.
Financial Mechanics: Pricing, Discounts, and Savings
The economic appeal of auto insurance as an employee benefit centers on potential cost savings. Insurance pricing is driven by actuarial risk assessment, which evaluates factors such as driving history, vehicle make and model, annual mileage, and garaging zip code. Group programs leverage economies of scale to alter the pricing equation.
Carriers often apply specific discount categories to employees who enroll through a corporate portal:
| Discount Type | Typical Savings Mechanism | Eligibility Requirement |
|---|---|---|
| Group Association Discount | 5% to 15% off standard rates | Being an active, W-2 employee of the participating partner organization. |
| Payroll Deduction Discount | Additional 2% to 5% reduction | Opting into automatic pre-tax or post-tax payroll deductions for premium payments. |
| Multi-Policy Bundling | Varies by carrier and location | Combining auto insurance with home, renters, or umbrella policies through the same provider. |
| Safe Driver / Telematics | Up to 30% based on driving habits | Participating in an app-based driving behavior monitoring program. |
Despite these reductions, employees should perform due diligence. A group rate does not automatically guarantee the absolute lowest price across the entire insurance marketplace. Independent comparison shopping remains essential, as specialized regional insurers or direct-to-consumer digital carriers may occasionally offer lower baseline quotes for specific demographic profiles.
Eligibility, Enrollment, and Administrative Requirements
Navigating an employer-sponsored auto insurance program involves distinct eligibility rules and enrollment periods. Unlike major medical insurance, which typically restricts enrollment to annual open enrollment windows or qualifying life events, voluntary auto insurance programs generally allow employees to enroll at any time during the calendar year.
Who is Eligible?
Typically, all active, permanent full-time and part-time employees meeting a minimum weekly hour threshold qualify to access the group insurance portal. Contractors and temporary workers may be excluded depending on the master services agreement established between the employer and the insurance carrier.
The Enrollment Process
- Accessing the Portal: Employees navigate to a dedicated landing page or intranet link provided by their human resources department, hosted securely by the insurance partner.
- Obtaining a Quote: The applicant inputs their driver's license details, vehicle identification number (VIN), current coverage declarations page, and driving history.
- Selecting Coverages: Users customize liability limits, comprehensive and collision deductibles, and optional endorsements such as roadside assistance or rental car reimbursement.
- Authorizing Deduction: The employee sets up the payment schedule by authorizing recurring payroll deductions.
- Policy Issuance: The carrier issues electronic proof of insurance cards and policy documentation directly to the employee.
Advantages and Limitations for Employees
Evaluating whether to utilize an employer-sponsored auto insurance benefit requires a balanced assessment of both operational benefits and potential drawbacks.
Advantages
- Simplified Budgeting: Spreading premium payments evenly across 24, 26, or 52 pay periods eliminates large, lump-sum cash flow disruptions.
- Exclusive Savings: Access to payroll deduction credits and group discounts that are unavailable to the general public.
- Simplified Claims and Service: Priority routing for customer inquiries through specialized corporate account teams.
- Continuous Coverage: Portability ensures that job transitions do not automatically result in a lapse of coverage.
Limitations and Risks
- Limited Carrier Choice: Employers typically partner with a single insurance carrier for the group program, restricting employees who prefer to compare quotes across multiple competing underwriters.
- Rate Fluctuations: Just like individual policies, group rates are subject to underwriting adjustments, inflation, and regional litigation trends, meaning premiums can still increase at renewal time.
- Administrative Dependency: While rare, processing errors between company payroll departments and insurance billing systems can occasionally cause temporary billing reconciliation issues.
Legal, Tax, and Regulatory Considerations
From a regulatory standpoint, employer-sponsored auto insurance is classified as a voluntary fringe benefit. Unlike employer-paid health insurance, which often enjoys favorable pre-tax treatment under Section 125 of the Internal Revenue Code, personal auto insurance premiums are almost universally paid using after-tax dollars through payroll deductions.
Employers do not assume liability for the driving habits of their staff merely by making a voluntary insurance program available. The contract is strictly between the employee and the insurance underwriting company. Employers must ensure that their benefits communications clearly disclose this distinction to avoid any misperception that the organization endorses, underwrites, or guarantees the financial solvency or claims-handling performance of the insurance provider.
Furthermore, human resources teams must comply with strict data privacy regulations, such as state-level consumer protection acts and federal standards, when transmitting employee identification and payroll deduction data to external insurance vendors.
Frequently Asked Questions
Can I keep my auto insurance policy if I leave my job?
Yes. Group auto insurance policies are fully portable. If you resign, retire, or transition to another employer, your policy remains active for the remainder of its term. The billing method will simply shift from automatic payroll deduction to direct billing between you and the insurance carrier, though you may lose any specific payroll-deduction discount associated with your former employer.
Do I have to drive for work to qualify for this benefit?
No. This benefit is designed for personal passenger vehicles used for commuting, running errands, and leisure driving. It is entirely separate from commercial auto insurance or business travel reimbursement policies, which apply when employees drive personal or company-owned vehicles specifically on company business.
Are my family members covered under the group auto policy?
Yes. Standard personal auto insurance policies extended through group programs cover eligible household drivers and licensed family members who reside in the same household and are listed on the policy declarations page, mirroring the coverage structure of individual retail policies.
Will using the employer group program affect my credit score?
Applying for a quote and enrolling in the program does not negatively impact your credit score. Insurance carriers may perform a soft credit-based insurance score inquiry during the underwriting and quoting process, which is explicitly designed not to alter or lower your credit rating.
Can employers see my driving record or claims history if I sign up?
No. Employers have zero visibility into individual driving records, accident claims, traffic violations, or policy selections. The transaction remains strictly confidential between the employee and the insurance underwriting company, ensuring complete personal privacy.
Conclusion and Next Actions
Auto insurance as an employee benefit serves as a valuable, cost-effective tool for workers seeking streamlined premium payments and potential group discounts without adding administrative burdens to their employers. To determine if this benefit is right for you, review your company’s internal benefits portal or speak with your human resources department to identify the partner insurance carrier. Obtain a comparative quote from the group portal and contrast it against independent insurance marketplaces to ensure you secure the most comprehensive coverage and competitive pricing for your driving profile.
Image Gallery
Select an image to open it in a new tab.
Akira Tanaka
International Academic Trends Correspondent
