Understanding the Prudential Life Insurance Living Needs Benefit: A Comprehensive Guide
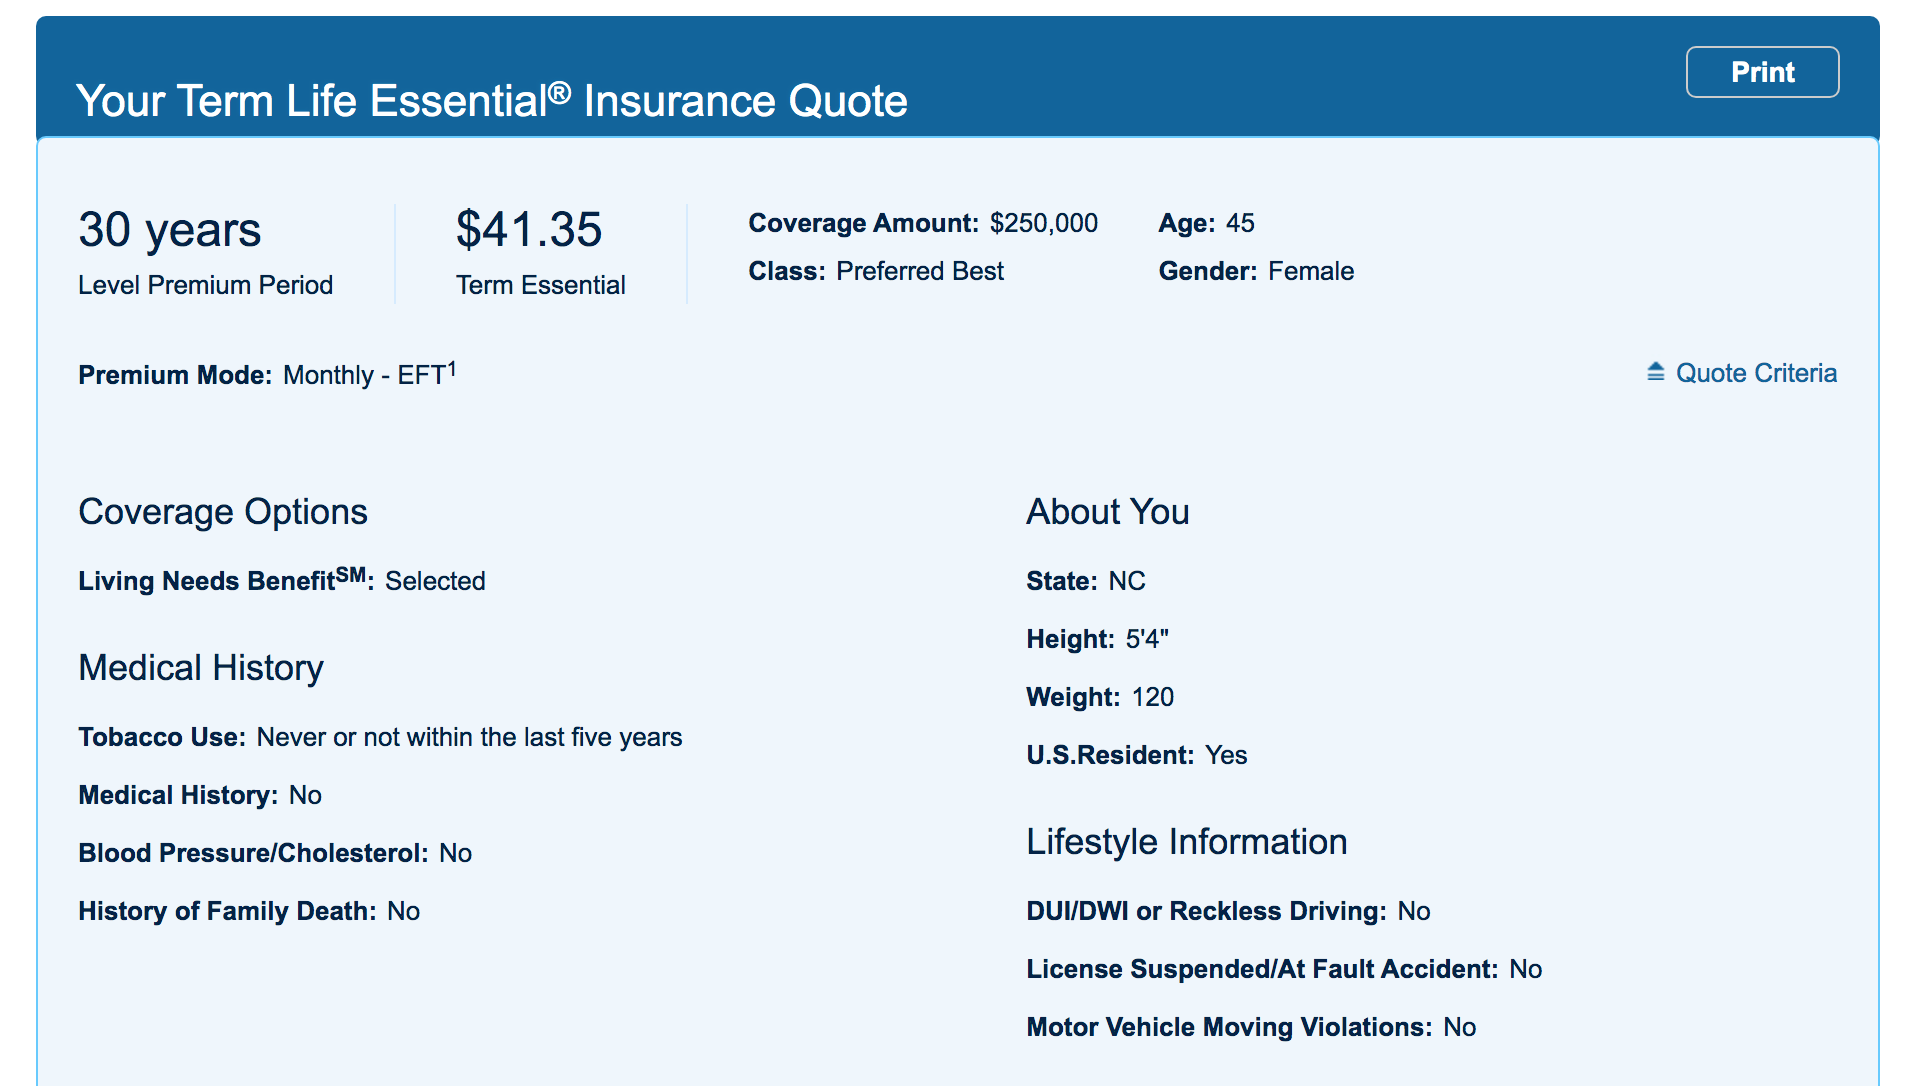
The Prudential Life Insurance Living Needs Benefit is a rider—an optional policy provision—that allows policyholders to access a portion of their life insurance death benefit early if they are diagnosed with a qualifying terminal illness. By accelerating a percentage of the policy’s face value, this benefit provides immediate liquidity to help manage medical expenses, end-of-life care, or other urgent financial obligations while the policyholder is still living.
What is the Living Needs Benefit?
At its core, the Living Needs Benefit is an accelerated death benefit (ADB). While standard life insurance policies are designed to pay a beneficiary upon the death of the insured, the Living Needs Benefit recognizes that the financial burden often peaks during the final stages of a terminal illness. By allowing the policyholder to receive these funds early, Prudential provides a financial tool to assist in coping with the costs associated with serious health conditions.
It is important to clarify that this is not a separate insurance policy but a feature typically attached to life insurance contracts. Whether this feature is included automatically or must be added as a rider depends on the specific policy issued by Prudential at the time of purchase.
Eligibility and Qualifying Conditions
Accessing the Living Needs Benefit is not automatic; it is governed by specific medical criteria established within the policy contract. To trigger a payout, the policyholder must generally meet the insurance company's strict definition of a "terminal illness."
Defining Terminal Illness
In most Prudential policies, a terminal illness is defined as a medical condition that is expected to result in death within a specified timeframe—often 6 months or 12 months, depending on the state of issue and the policy language.
Medical Documentation
The policyholder must provide satisfactory medical evidence. This involves submitting official documentation from a licensed physician confirming the diagnosis, the prognosis, and the expected timeframe of the condition. Prudential’s claims department reviews this documentation to ensure it aligns with the contractual definition of terminal illness. It is crucial to note that the benefit is strictly reserved for terminal conditions; chronic illnesses or temporary disabilities generally do not qualify unless the policy includes a separate, specific rider for those conditions.

How the Payout Mechanism Functions
When an application for the Living Needs Benefit is approved, the policyholder does not receive the full death benefit. Instead, the payout is calculated based on several factors, including the policy’s face amount, the maximum acceleration percentage allowed, and potential administrative fees.
Acceleration Percentages
Prudential policies generally set a maximum percentage of the total death benefit that can be accelerated. For example, if a policy has a $500,000 death benefit and a 50% acceleration limit, the maximum amount the policyholder could receive is $250,000.
The Impact on the Death Benefit
Because the Living Needs Benefit is an advance payment, it directly reduces the amount of money that will be paid to the beneficiary upon the policyholder’s death. If a policyholder chooses to accelerate $100,000 of a $300,000 policy, the remaining death benefit for their beneficiaries will be reduced, typically adjusted by the amount taken plus any applicable interest or administrative charges stipulated in the contract.
Administrative Costs
While some riders are included at no extra cost, there may be administrative fees or interest charges associated with the processing and discounting of the death benefit. These costs are usually deducted from the benefit payout before it reaches the policyholder.
Comparison of Accelerated Death Benefits
Understanding how the Living Needs Benefit compares to other types of policy riders is essential for effective financial planning.
| Feature | Living Needs Benefit | Long-Term Care (LTC) Rider | Critical Illness Rider |
|---|---|---|---|
| Primary Trigger | Terminal diagnosis (limited time) | Chronic illness/inability to perform ADLs | Specific covered illnesses (e.g., cancer) |
| Usage | General expenses | Skilled nursing/home care | Medical and related costs |
| Impact on Policy | Reduces death benefit | Reduces death benefit | Reduces death benefit |
| Prognosis Requirement | High (terminal) | Medium (chronic/long-term) | Low (diagnosis-based) |
Steps to Verify Coverage and Apply
If you are a policyholder or a representative, you must verify the existence of this benefit before initiating a claim.
- Review the Policy Document: Locate your original policy summary or "Schedule of Benefits." This document will state if a "Living Needs Benefit," "Accelerated Death Benefit," or similar provision is included.
- Contact Prudential Directly: Call the Prudential customer service line listed on your most recent billing statement or official correspondence. Verify the status of the rider and confirm whether it is active on your specific contract.
- Request Claim Forms: If you meet the medical criteria, request the specific "Living Needs Benefit" claim packet.
- Physician Certification: Your attending physician must complete the medical certification portion of the claim. Ensure they use the exact clinical terminology required by Prudential to prevent delays.
- Submission and Review: Submit all forms to the designated Prudential claims address. Expect a period of internal review where the company validates the diagnosis against their underwriting guidelines.
Financial and Tax Implications
The financial decision to accelerate a death benefit carries significant weight. Because this payout reduces the future death benefit, it should be considered a last-resort option.
Tax Treatment
Under current federal tax laws, the Living Needs Benefit payout for a terminally ill individual is generally received income-tax-free. However, tax laws can be complex and subject to state-level variations. It is highly recommended to consult with a tax professional or a certified financial planner (CFP) to understand how an accelerated payout might affect your specific tax bracket, eligibility for government assistance programs, or overall estate planning goals.
Impact on Medicaid and Public Assistance
Receiving a large lump-sum payment can affect an individual’s eligibility for needs-based government programs like Medicaid or Supplemental Security Income (SSI). Because these programs have strict asset and income limits, a significant payout from a life insurance policy might disqualify an individual from receiving essential benefits.
Common Pitfalls and Considerations
Navigating the Living Needs Benefit requires attention to detail. Many policyholders run into challenges by misunderstanding the scope of the coverage.
- Misinterpreting "Terminal": A common mistake is assuming that any serious illness, such as a debilitating heart condition or chronic autoimmune disorder, qualifies for the benefit. If the condition is not "terminal" as defined by the policy (usually involving a prognosis of impending death), the claim will be denied.
- Neglecting the Death Benefit Reduction: Policyholders sometimes fail to account for the impact on their primary beneficiaries. If the primary goal of the life insurance is to provide debt relief for family members after death, accelerating the benefit may leave those beneficiaries with insufficient funds to meet those obligations.
- Ignoring Administrative Fees: Always clarify if there is a flat fee or a discount rate applied to the accelerated amount. Knowing the exact net amount you will receive is vital for your financial planning.
Frequently Asked Questions
1. Is the Living Needs Benefit mandatory? No, it is an optional feature. Even if your policy includes the provision, you are not required to exercise it. It is entirely at the discretion of the policyholder to decide if and when to access these funds.
2. Can I use the money for anything I want? Yes. Unlike specific health insurance benefits that may only cover hospital bills, the payout from a Living Needs Benefit is generally provided as a lump sum with no restrictions on how the funds are used. Many people use the money for medical bills, hospice care, debt repayment, or to fulfill final life wishes.
3. Does exercising the benefit cancel my life insurance? No. Exercising the benefit does not cancel the entire policy. It only reduces the face amount of the death benefit by the amount you accelerate. Assuming premiums remain paid, the remainder of the policy stays in force.
4. What happens if my health improves after I receive the benefit? The benefit is a permanent adjustment to your policy. Once the funds are paid out, the death benefit remains at the reduced level. The payout does not need to be returned if the prognosis changes, though you should check your specific policy for any rare exceptions or contractual stipulations.
5. How long does the approval process take? The timeline varies based on the completeness of the medical documentation provided. Once the medical certification is received and verified by Prudential, the processing time typically takes several weeks. It is best to follow up periodically with the claims department.
Professional Guidance and Next Actions
The decision to exercise a Living Needs Benefit is often made during an emotionally and physically difficult time. To ensure you make the most informed choice:
- Consult Your Financial Advisor: A professional can perform a cash-flow analysis to determine if accelerating the benefit is the best way to handle your current expenses versus other available resources.
- Discuss with Family Members: Since this action reduces the death benefit your beneficiaries will eventually receive, maintain transparency with those who may be impacted.
- Verify Your Policy Documents: Do not rely on memory. Read the "Accelerated Death Benefit" section of your specific policy contract to understand your precise definitions, limitations, and potential fees.
If you believe you have an immediate need and meet the medical requirements, your first step should be to locate your Prudential policy documents and contact their customer service center to request the specific claim documentation for the Living Needs Benefit. This ensures that you have the most current and accurate forms specific to your contract version and state of residence.
Image Gallery
Select an image to open it in a new tab.

Vivian Cho
Executive IT and Emerging Technologies Reporter
