
Choosing the right credit card for cash rewards depends on aligning your unique spending habits with a card’s specific earning structure. The best options for 2026 prioritize high flat-rate earnings, rotating bonus categories, or specialized tiers for daily expenses like groceries and dining, ensuring that every dollar spent contributes directly to your bottom line.
Understanding Cash Rewards Structures
Before selecting a card, it is essential to distinguish between the three primary ways issuers structure cash rewards. Understanding these mechanics will prevent you from choosing a card that offers high potential earnings but fails to align with your actual monthly expenditure.
- Flat-Rate Rewards: These cards offer a consistent percentage back on every purchase regardless of the category. They are ideal for individuals who prefer simplicity and want to avoid tracking spending across multiple merchants.
- Tiered Bonus Categories: These cards provide elevated cash back (e.g., 3% or 5%) in specific categories, such as supermarkets, gas stations, or streaming services, while offering a lower base rate for "other" purchases. These are most effective for households with predictable, high-volume spending in specific areas.
- Rotating Categories: These rewards cards feature categories that change quarterly, often offering up to 5% cash back. These require active management, as cardholders usually must "activate" the category each quarter to earn the bonus rates.
Evaluating the Top 7 Credit Card Cash Rewards for 2026
While credit card offerings evolve, the following seven cards maintain consistent value for different consumer profiles as of 2026.
1. The All-Rounder: Citi Double Cash® Card
The Citi Double Cash is widely regarded as a staple for those who value a "set it and forget it" approach. It offers a flat rate on all purchases, split into two 1% increments: one when you buy and one when you pay your statement.
- Best for: Consumers who want maximum simplicity without sacrificing return.
- Why it works: You do not have to worry about merchant codes or quarterly activations.
2. The Grocery Powerhouse: Blue Cash Preferred® Card from American Express
If your household budget is heavily weighted toward groceries and streaming subscriptions, this card offers one of the most competitive percentage-based returns in the industry.
- Best for: Families with high monthly grocery bills.
- Consideration: This card carries an annual fee, so you must ensure your spending in bonus categories justifies the cost compared to a no-fee alternative.
3. The Quarterly Strategist: Chase Freedom Flex®
This card is designed for the proactive user. By rotating its 5% cash back categories every three months, it captures a broad range of seasonal spending, from warehouse clubs to home improvement stores.
- Best for: Organized individuals who don't mind spending a minute each quarter to activate their rewards.
4. The Dining and Drugstore Choice: Capital One SavorOne Cash Rewards
Focusing on the "fun" side of your budget, this card rewards dining, entertainment, popular streaming services, and grocery stores. It is a no-annual-fee card that provides high utility for younger professionals or those who frequent restaurants.
- Best for: Foodies and entertainment enthusiasts.
5. The Flat-Rate No-Fee Alternative: Wells Fargo Active Cash® Card
Similar to the Citi Double Cash, the Active Cash provides a flat 2% cash rewards rate. It distinguishes itself by offering an intuitive redemption process and often includes a robust initial sign-up bonus, which can be a deciding factor for new applicants.
- Best for: Those who want a straightforward, high-rate card without an annual fee.
6. The Business Essential: Ink Business Cash® Credit Card
Small business owners have unique spending needs, often centered on office supplies and telecommunications. This card offers tiered rewards that can significantly lower the overhead costs of running a business.
- Best for: Small business owners with significant expenses in office-specific categories.
7. The Hybrid Travel-Cash Card: Discover it® Cash Back
The Discover it card is famous for its 5% rotating categories and its unique "Cashback Match" program. At the end of the first year, Discover matches all the cash back you have earned, effectively doubling your first-year return.
- Best for: New credit card users and those who value the "match" incentive at the end of their first year.
Comparison Table: 2026 Cash Rewards Overview
| Card Name | Primary Reward Structure | Best For | Annual Fee |
|---|---|---|---|
| Citi Double Cash | 2% Flat Rate | Simplicity | $0 |
| Blue Cash Preferred | 6% Groceries | High-spend families | $95* |
| Chase Freedom Flex | 5% Rotating | Strategic spenders | $0 |
| Capital One SavorOne | 3% Dining/Ent. | Social spenders | $0 |
| Wells Fargo Active Cash | 2% Flat Rate | Everyday earners | $0 |
| Ink Business Cash | Tiered Business | Business owners | $0 |
| Discover it Cash Back | 5% Rotating | First-year value | $0 |
*Annual fee subject to issuer terms.
Eligibility and Prerequisites
Before applying for any of the cards listed, you must assess your financial profile. Most, if not all, of these top-tier rewards cards require a "Good" to "Excellent" credit score.
- Credit Utilization: Issuers look at how much of your current credit line you are using. Aim to keep this below 30% before applying.
- Application Velocity: Applying for multiple credit cards in a short period can trigger "hard inquiries," which may temporarily lower your score and signal financial distress to issuers.
- Verification: Be prepared to provide proof of income and identity. Business cards may require an Employer Identification Number (EIN) or documentation of your business structure.
How to Maximize Your Rewards
Having the right card is only half the battle. To extract the maximum value, you must treat your credit card as a financial tool rather than an extension of your income.
1. Pay in Full Every Month The interest rates on rewards cards are often high. If you carry a balance, the interest you pay will quickly negate any cash back you earn. If you cannot pay the full balance, you are losing money regardless of the reward rate.
2. Audit Your Spending Look at your bank statements from the previous twelve months. Are you spending $800 a month on groceries, or is your budget dominated by gas and commuting? Match your card to your actual spending, not to what you think you might spend.
3. Optimize Redemption Some cards allow for instant statement credits, while others require a minimum threshold to be met before you can claim your cash. Understand your issuer’s portal—some offer more value if you redeem for gift cards or travel, though for the purpose of this analysis, we are focusing on pure cash back.
Common Mistakes to Avoid
- Ignoring the Annual Fee: An annual fee is only worth it if your increased earnings in bonus categories exceed the cost of the fee. Do the math annually.
- Failing to Activate: For cards like the Chase Freedom Flex or Discover it, failing to click "activate" on the quarterly categories will leave you earning only the base 1% rate, significantly lowering your annual return.
- Redeeming for Non-Cash Items: If your goal is cash rewards, avoid redeeming points for merchandise or store-specific items unless the exchange rate is clearly favorable.
Frequently Asked Questions
Does a 2% flat-rate card always beat a 5% rotating card? Not necessarily. If your spending is highly concentrated in the bonus categories (e.g., you spend heavily on gas when it is a 5% category), you will likely earn more with a rotating card. However, if your spending is fragmented and inconsistent, a flat-rate card is usually more lucrative and requires less effort.
What happens to my cash rewards if I close my credit card? In most cases, if you close your credit card account, you forfeit any unredeemed cash rewards. Always redeem your full balance of rewards before initiating a product change or closing an account to avoid losing accumulated value.
Are there limits to how much cash back I can earn? Some cards have "caps" on the bonus categories. For example, a card might offer 5% back on the first $1,500 of combined purchases in bonus categories per quarter. Once you exceed that limit, the rate drops to 1%. Always read the "Terms and Conditions" regarding category caps.
Can I have more than one cash rewards card? Yes. In fact, many people use a "multi-card strategy." They might use one card specifically for groceries, another for gas, and a flat-rate card for everything else. This maximizes the rewards potential but requires disciplined tracking.
Do cash rewards count as taxable income? Generally, no. The IRS views credit card cash rewards as a "rebate" on purchases rather than income, provided you have to spend money to earn them. However, if you receive a sign-up bonus or referral bonus, you should consult with a tax professional regarding your specific situation, as interpretations can vary based on the nature of the reward.
Final Recommendation
To begin, identify your largest recurring expense category. If your spending is dominated by one category—such as groceries or dining—prioritize a card like the Blue Cash Preferred or SavorOne. If you prefer simplicity or have varied, unpredictable expenses, the Citi Double Cash or Wells Fargo Active Cash provides the most reliable return. Ensure your credit score meets the requirements for your target card, and always set up autopay for the full statement balance to ensure your rewards are never eroded by interest charges.
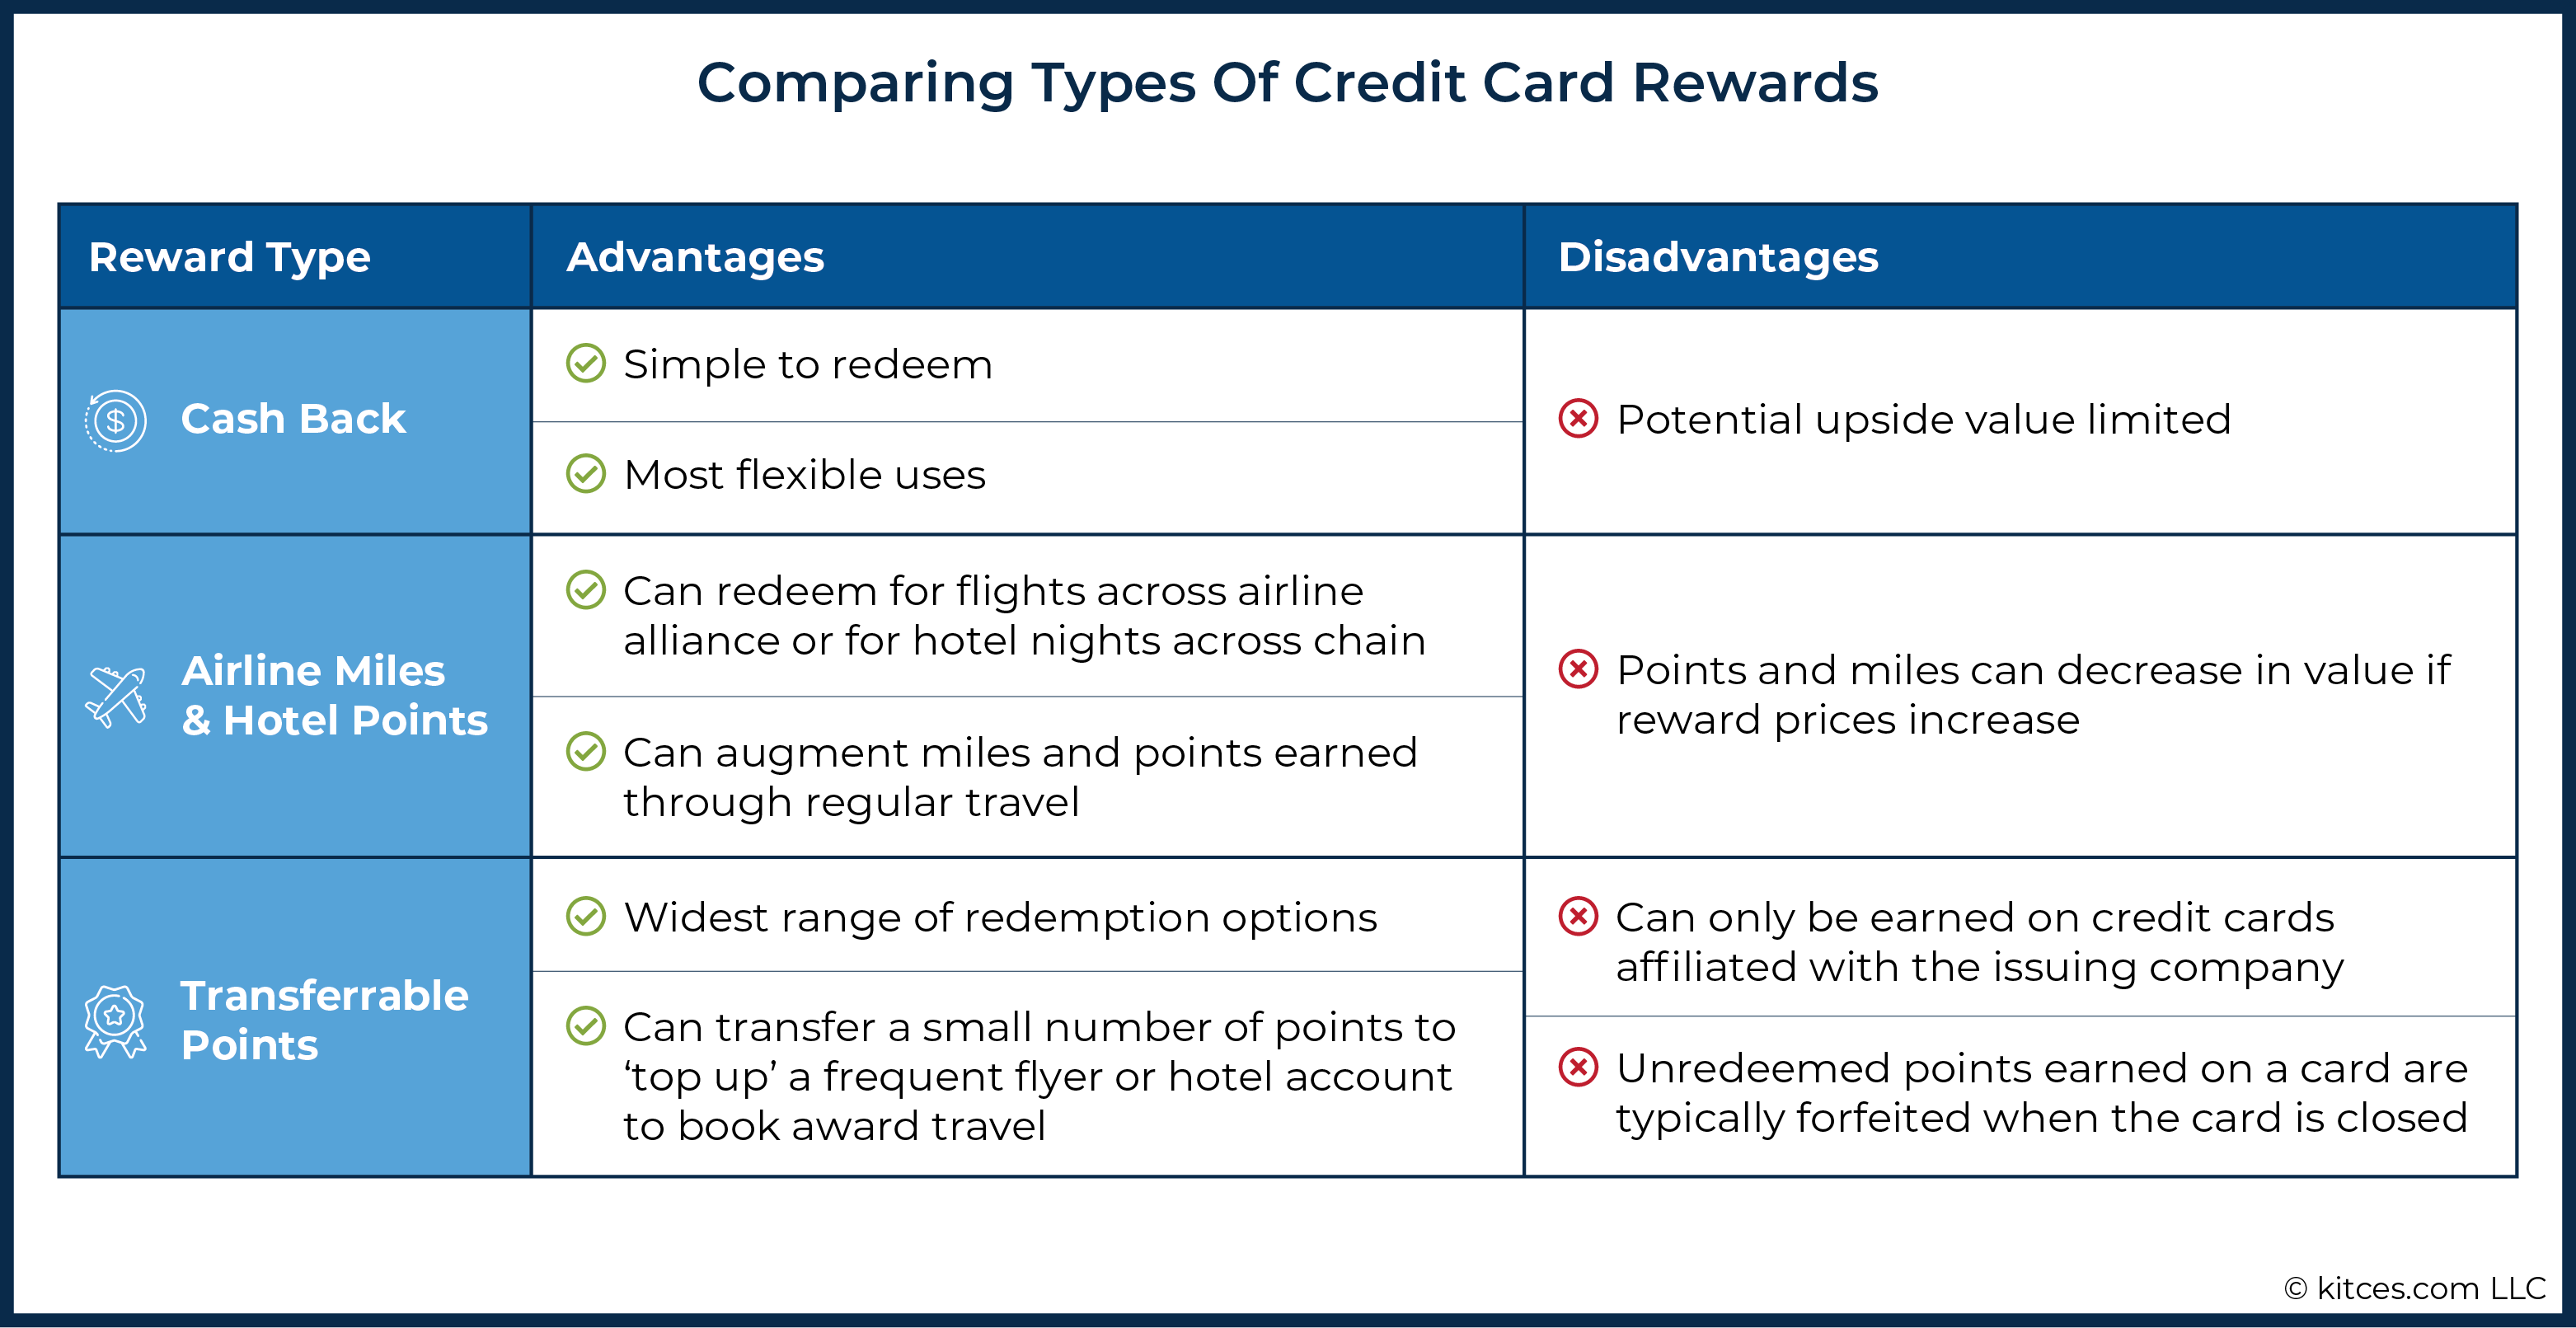
Image Gallery
Select an image to open it in a new tab.


Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
