
Choosing life insurance after turning fifty involves balancing immediate budget realities with long-term legacy planning, final expense management, and evolving health profiles. Unlike term policies purchased in early adulthood, over-50s cover options require a strategic shift toward guaranteed acceptance, whole life structures, and policies designed to protect loved ones from funeral costs or inheritance taxes without requiring extensive medical underwriting.
Understanding Life Insurance for the Over 50s Demographic
As individuals cross the age of 50, the financial landscape shifts dramatically. Mortgages may be paid off, children might be financially independent, and retirement planning takes center stage. Consequently, the purpose of life insurance changes. Rather than replacing a lost primary income for decades of child-rearing, life insurance for over-50s typically addresses distinct, near-term financial obligations.
Understanding these options requires examining how insurers calculate risk and price policies for older applicants. Age is a primary rating factor; as you age, the statistical likelihood of an insurance claim increases, which naturally raises monthly premiums for traditional underwritten products. To accommodate this, the insurance market provides specialized products designed specifically for this demographic. These products often bypass traditional medical examinations, replacing them with simplified questionnaires or guaranteed acceptance frameworks.
Navigating these choices successfully means evaluating your health status, your financial goals, and your budget consistency. A policy that makes sense at age 51 might carry very different long-term cost implications by age 70. Therefore, analyzing cover options requires a clear-eyed look at how policy types function over time.
Core Types of Life Insurance Cover Options for Over 50s
The market generally divides over-50s coverage into three primary structures: over-50s plans (often called guaranteed acceptance life insurance), term life insurance, and whole life (or permanent) insurance with medical underwriting. Each option serves a unique purpose and comes with distinct structural trade-offs.
Over-50s Guaranteed Acceptance Plans
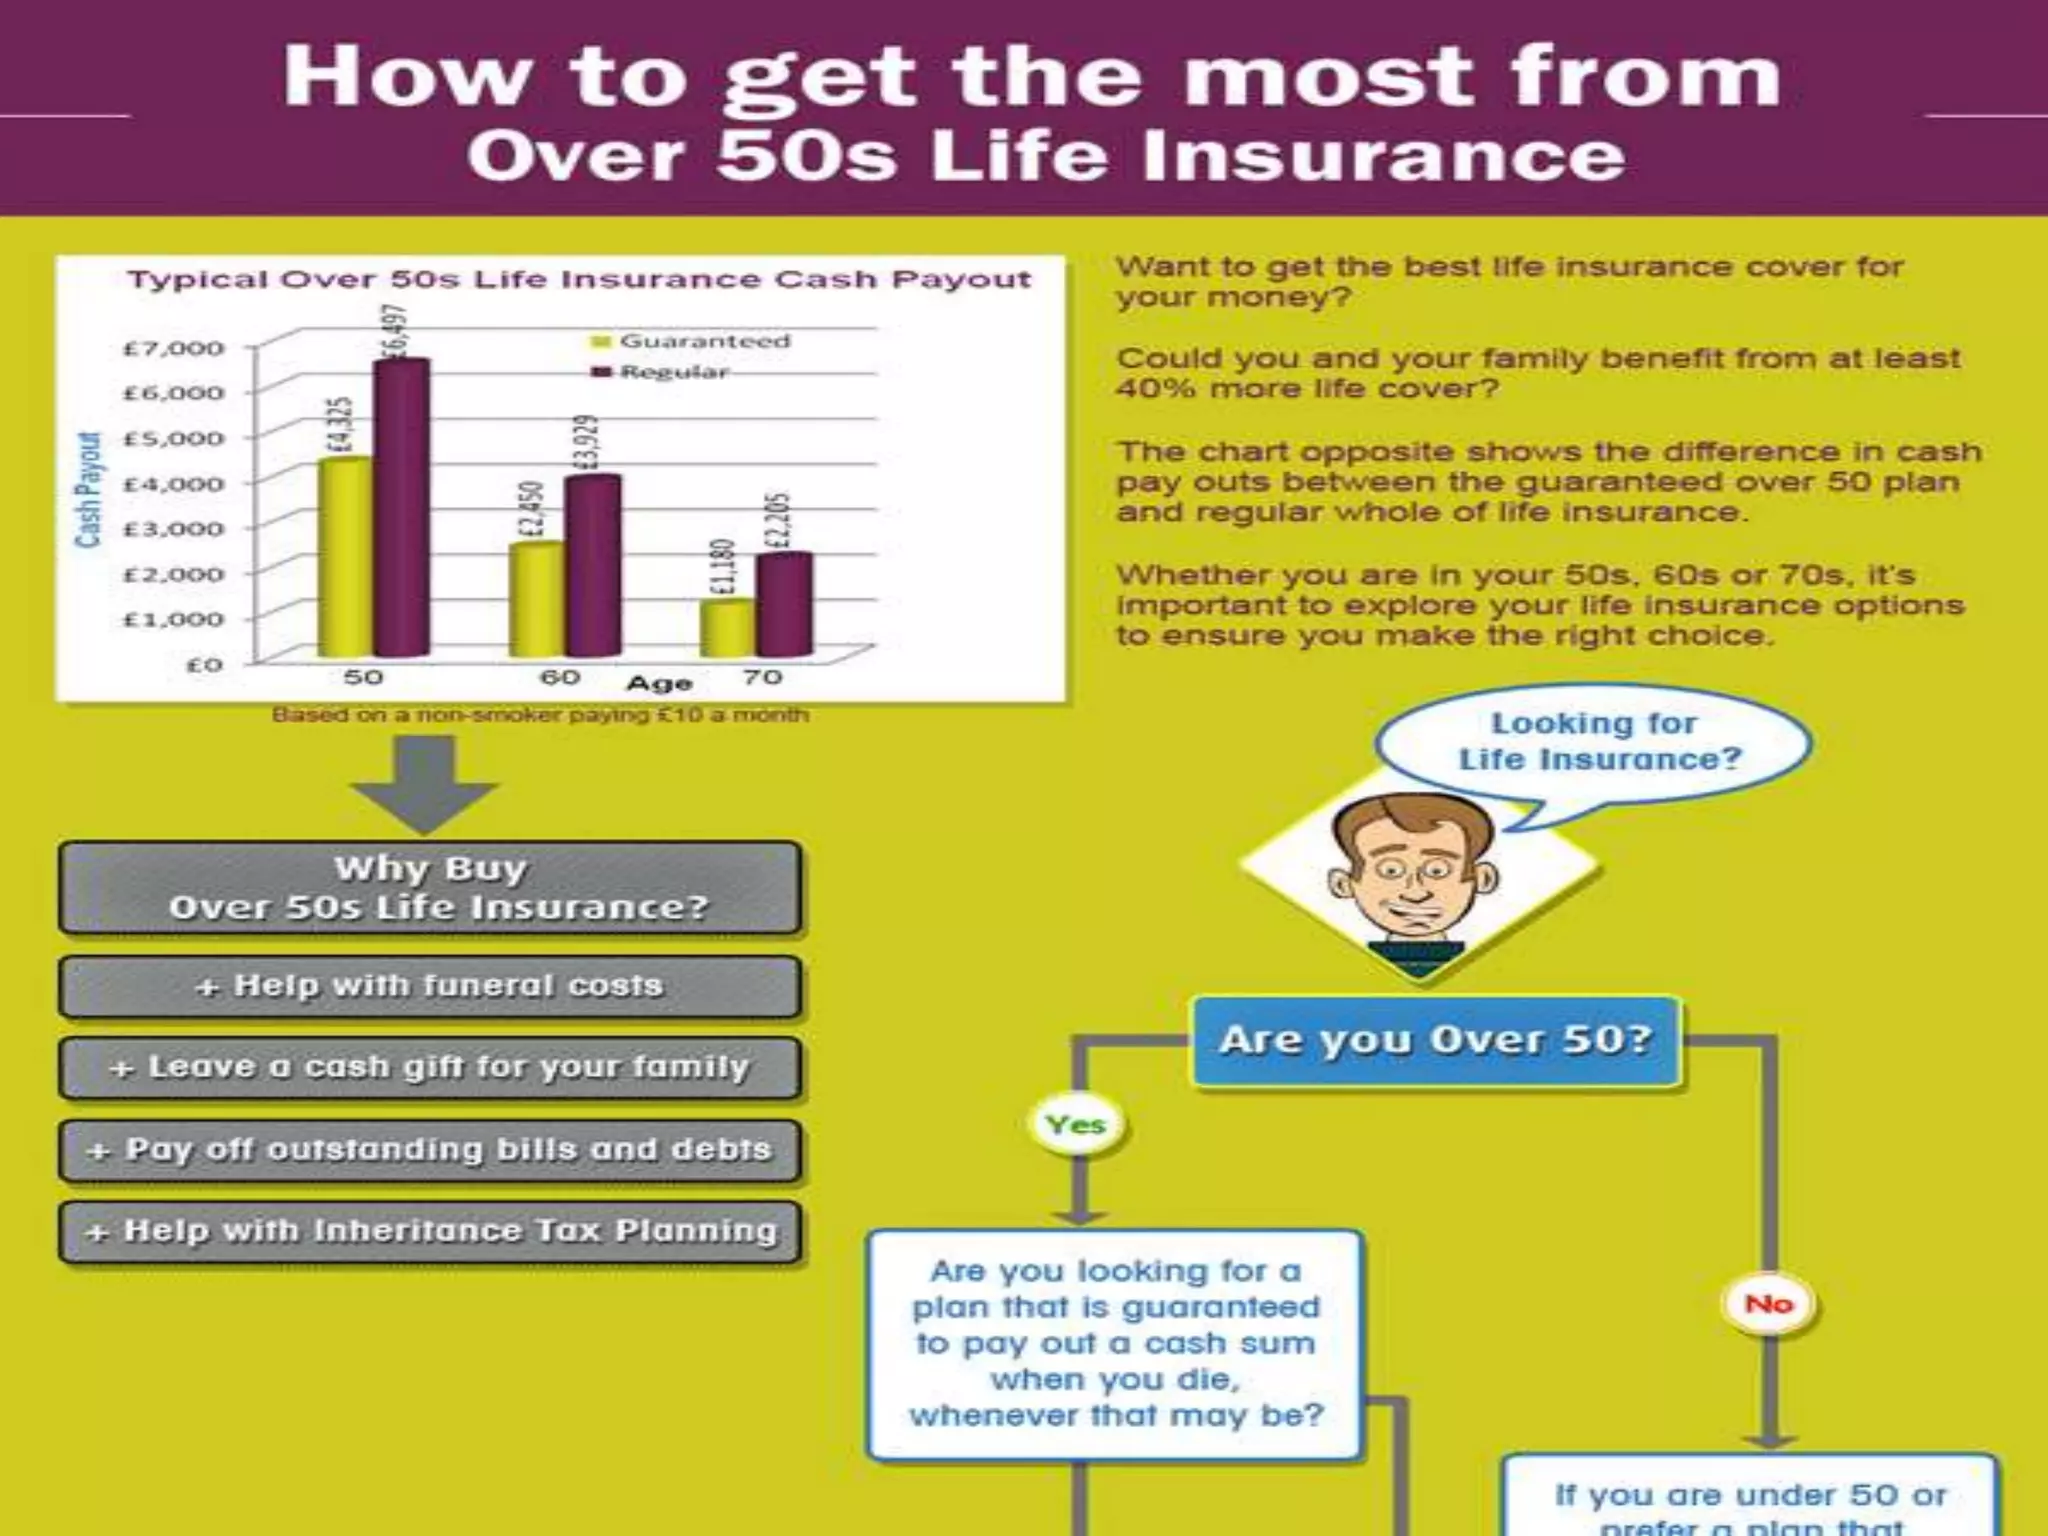
Guaranteed acceptance plans are specifically marketed to older adults, often promising that no medical exams or health questions are required.
- Core Mechanism: Acceptance is legally guaranteed for any resident within the eligible age bracket (typically ages 50 to 80).
- Premiums: Premiums are usually fixed for life, meaning what you pay on day one is what you pay indefinitely.
- The Catch (Qualifying Periods): Most policies feature a "deferred period"—usually 1 to 2 years. If the policyholder dies from natural causes during this initial window, the beneficiaries do not receive the full payout. Instead, they typically receive a refund of all premiums paid, sometimes with a small amount of interest. Death by accidental injury is usually covered immediately.
Level Term Life Insurance
Level term insurance provides cover for a fixed, predetermined period (e.g., 10, 15, or 20 years).
- Core Mechanism: If you pass away within the term, the policy pays out a tax-free lump sum. If you outlive the term, the policy expires with no payout and premiums are lost.
- Underwriting: These policies require medical underwriting. Insurers will ask detailed health and lifestyle questions, and may require a nurse visit or a medical records review.
- Cost Efficiency: Because underwriting filters out higher-risk applicants, healthy 50-year-olds can often secure substantial coverage amounts for relatively low, fixed monthly premiums compared to guaranteed plans.
Whole Life Insurance (Underwritten)
Whole life insurance covers the policyholder for the remainder of their life, provided premiums are maintained.
- Core Mechanism: Guaranteed payout upon death whenever it occurs, combined with a potential cash-value accumulation component depending on the specific product structure.
- Underwriting: Requires full medical underwriting. Premiums are generally higher than term insurance but offer lifelong security without expiration dates.
| Cover Option | Medical Exam Required? | Payout Guarantee | Premium Structure | Primary Use Case |
|---|---|---|---|---|
| Over-50s Guaranteed | No | Yes (After deferred period) | Fixed for life | Covering funeral costs with health issues |
| Level Term Life | Usually No (Health questions yes) | Only if death occurs within term | Fixed for the term duration | Covering temporary debts, mortgage, dependents |
| Whole Life (Underwritten) | Yes (Detailed medical history) | Guaranteed lifelong payout | Fixed or adjustable | Leaving a guaranteed legacy or inheritance |

Evaluating Your Financial Goals and Cover Requirements
Before selecting a policy, you must define the exact financial objective you want the insurance to achieve. Purchasing insurance without a specific target often leads to over-insuring or buying a product that fails to meet your family's needs when it matters most.
Final Expense and Funeral Planning
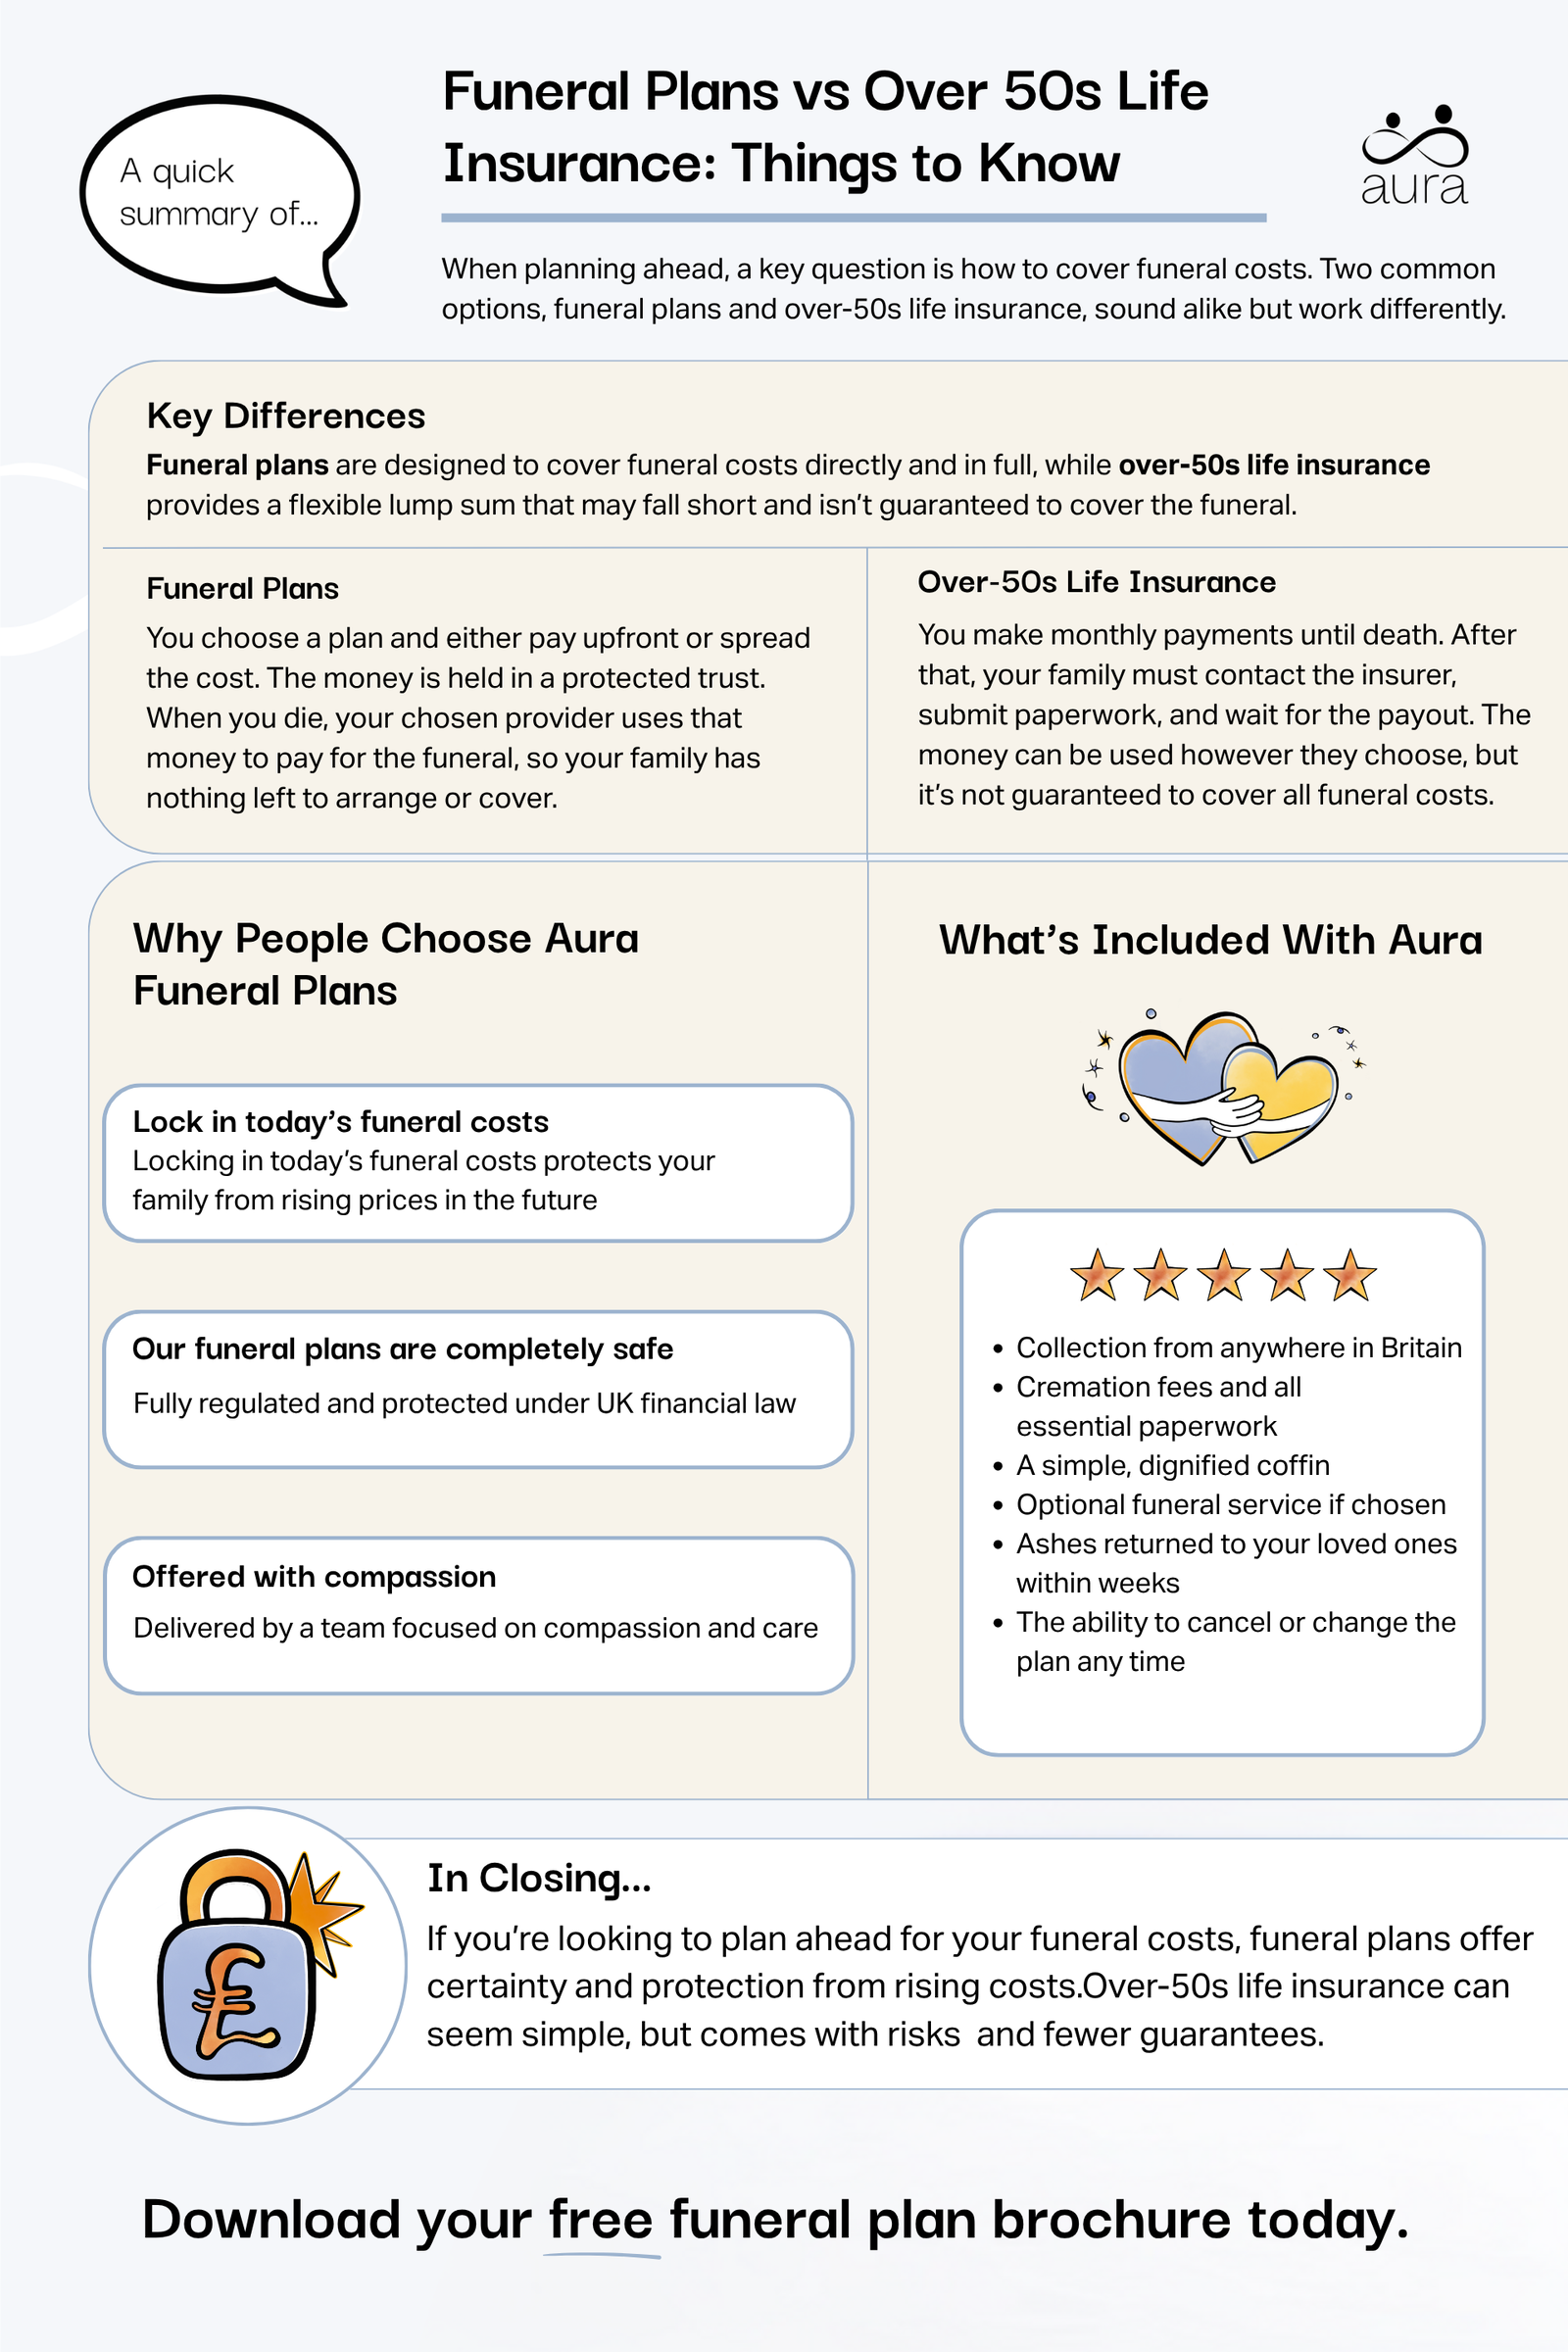
The most common reason individuals over 50 purchase life insurance is to cover funeral and end-of-life expenses. Average funeral costs continue to rise, and leaving this financial burden to grieving family members can cause significant stress. A smaller policy (ranging from modest fixed payouts) is usually sufficient for this purpose.
Inheritance Tax (IHT) Mitigation
For individuals with substantial estates, life insurance can be an effective tool to manage potential inheritance tax liabilities. By placing a life insurance policy in an appropriate trust, the payout can be directed straight to beneficiaries outside of the taxable estate, providing liquidity to pay tax bills without forcing the sale of family property or investments.
Clearing Outstanding Debts
While many people aim to be debt-free by age 50, some retain mortgages, car loans, or credit lines. If your passing would leave a surviving partner struggling to service these debts on a single income, a term life insurance policy matching the remaining amortization schedule is worth considering.
Key Factors Impacting Cost and Eligibility
When shopping for over-50s cover options, several variables dictate how much you will pay and whether you qualify. Insurance providers evaluate these metrics meticulously to price risk.
Age and Gender
Age is the single most significant factor in life insurance pricing. A policy purchased at age 50 will be considerably cheaper per month than the exact same policy purchased at age 65. Furthermore, actuarial tables show that women statistically outlive men, meaning female applicants often secure lower monthly premiums for identical coverage levels.
Health and Lifestyle Habits
For underwritten policies, current health status, medical history, and family medical background dictate pricing. Smoking or vaping drastically increases premiums across almost all insurance categories due to the associated health risks. Similarly, body mass index (BMI), blood pressure readings, and cholesterol levels are heavily scrutinized.
Inflation Risk and Fixed Payouts
One critical limitation of many over-50s guaranteed plans is that the payout is fixed. Due to inflation, the purchasing power of that lump sum decreases over time. For example, a fixed payout that covers a standard funeral today may fall short of covering the same funeral fifteen years later. Some modern policies offer an index-linked option where premiums and payouts increase annually in line with inflation, though this causes monthly costs to rise over time.
Common Mistakes to Avoid When Buying Cover After 50
Navigating the life insurance market requires vigilance. Avoiding common pitfalls ensures your investment genuinely protects your beneficiaries.
- Failing to Read the Deferred Period Clause: Many buyers purchase guaranteed acceptance plans assuming immediate full coverage, only to discover their beneficiaries are unprotected for natural death during the first 24 months.
- Canceling Existing Policies Prematurely: Never cancel an older, active policy until you have successfully secured and verified a new policy. Doing so can result in losing favorable rates locked in years prior.
- Under-Insuring Due to Cost: Selecting the cheapest possible monthly premium often results in a payout too small to cover modern funeral expenses or targeted financial goals.
- Neglecting to Use Trusts: Failing to write your policy into a trust can mean the payout becomes part of your legal estate, subjecting it to probate delays and potential inheritance taxes.
Frequently Asked Questions
Can I get life insurance over 50 if I have pre-existing medical conditions?
Yes. While underwritten term or whole life policies may reject applicants with severe medical histories or charge higher premiums, over-50s guaranteed acceptance plans do not ask any medical questions. As long as you fall within the age limits, acceptance is guaranteed regardless of your health status.
What happens if I stop paying my life insurance premiums?
If you stop paying premiums on a standard term or over-50s guaranteed plan, the policy will lapse after a short grace period. Once lapsed, the coverage ceases entirely, and you will lose all the money you previously paid into the plan, as these policies typically hold no cash-in value.
Are life insurance payouts subject to income tax?
In most jurisdictions, including the United Kingdom and the United States, life insurance payouts distributed directly to beneficiaries are generally exempt from income tax. However, the total value of the payout may be subject to inheritance tax unless the policy is written into an appropriate trust.
Is it better to choose a whole life policy or a term policy at age 50?
The choice depends entirely on your objectives. If you need coverage only until your mortgage is paid off or your children finish university, a term policy is usually more cost-effective. If your goal is to cover lifelong final expenses or leave a guaranteed inheritance, a whole life or over-50s guaranteed plan is more appropriate.
Do over-50s life insurance policies ever expire?
Guaranteed over-50s plans and traditional whole life policies run for the rest of your life, provided you maintain your premium payments. Level term policies, conversely, have a fixed expiration date and will terminate once that term concludes.
Next Actions and Recommendations
To secure the right over-50s cover option, start by calculating your precise financial obligations—such as estimated funeral expenses or outstanding debts—rather than guessing an arbitrary coverage amount. Request quotes from multiple reputable insurers, paying close attention to whether the plan requires medical underwriting or enforces a deferred payout period. Finally, consult with an independent financial advisor or estate planner to discuss placing your chosen policy into a trust, ensuring your beneficiaries receive their funds efficiently and without unnecessary tax complications.
Image Gallery
Select an image to open it in a new tab.


Lars Thomsen
Global Labor Markets and Economic Strategy Editor
