
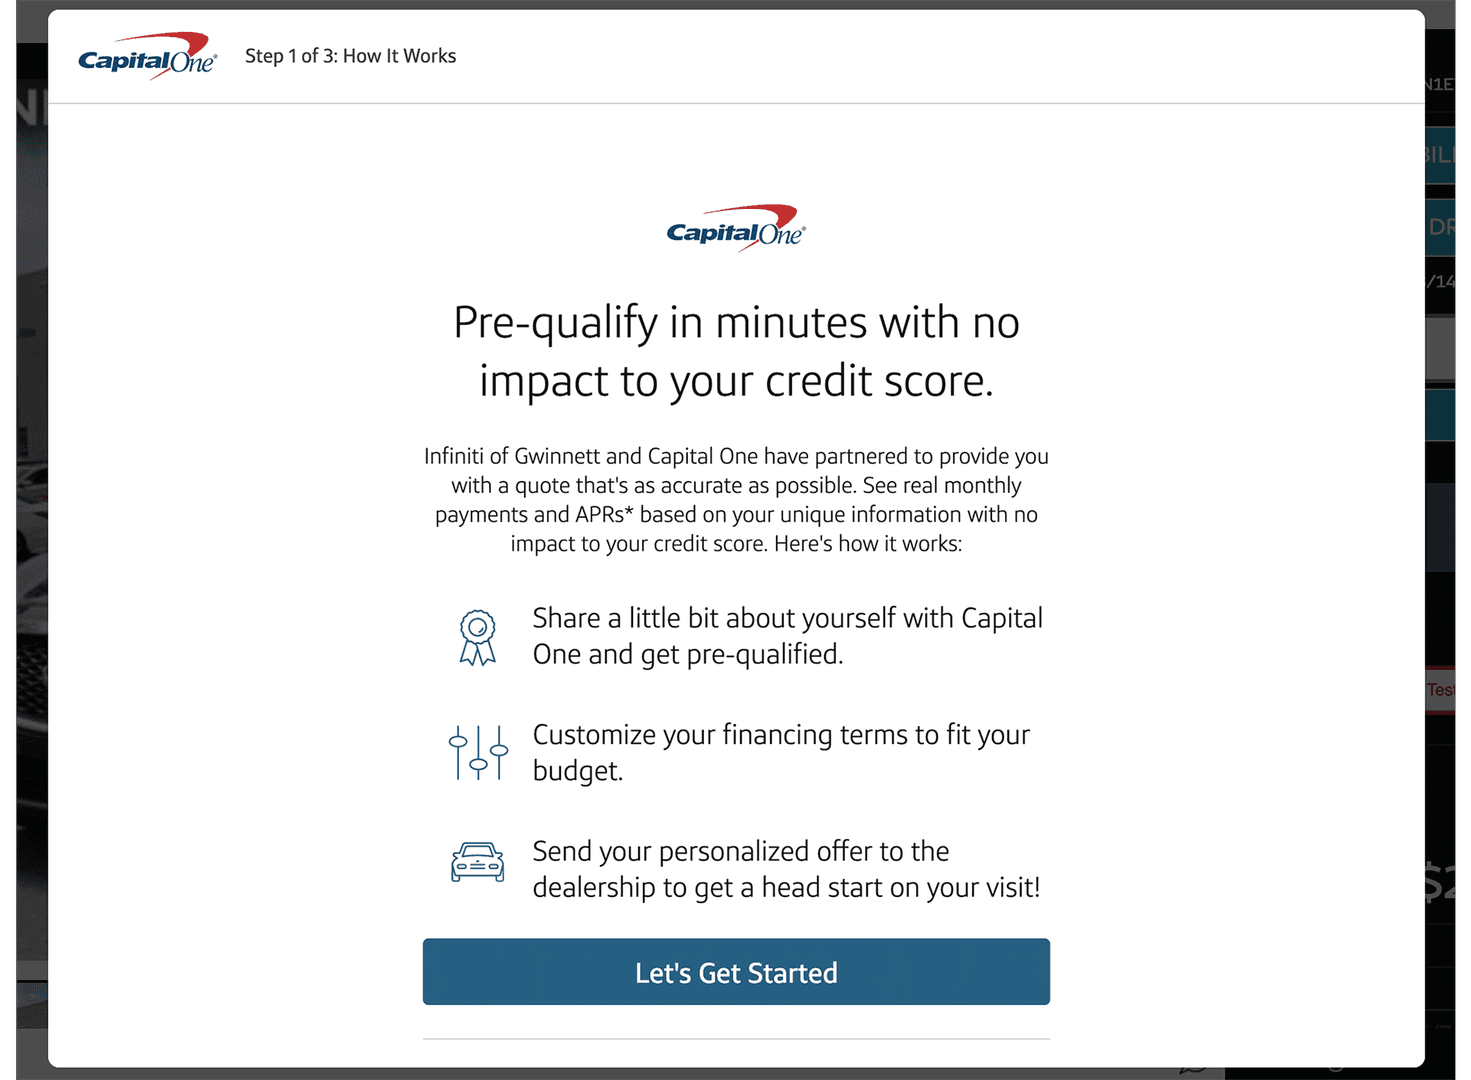
To get pre-qualified for a Capital One credit card, visit the official Capital One website and navigate to the "Pre-Approval" page. You will need to provide personal details, including your name, address, income, and Social Security number. Capital One performs a soft credit pull to determine your eligibility without impacting your credit score.
Getting a new credit card is often a stressful experience because of the uncertainty involved. Traditionally, the only way to know if you would be accepted for a specific card was to submit a formal application, which triggers a "hard inquiry" on your credit report. These inquiries can temporarily lower your credit score by several points. In 2026, Capital One continues to lead the industry with a robust pre-qualification tool that removes this guesswork. This process allows you to see which cards you are likely to be approved for before you take any risk to your credit profile.
Understanding how to navigate this process efficiently requires a grasp of how credit reporting works, what specific information Capital One looks for, and how to interpret the offers you receive. This guide provides a comprehensive breakdown of the steps, requirements, and technical nuances of the Capital One pre-qualification system.
The Technical Difference Between Pre-Qualification and Pre-Approval
In the financial industry, the terms "pre-qualified" and "pre-approved" are often used interchangeably by consumers, but they have technical distinctions. At Capital One, the pre-qualification tool is a proactive way for you to check your eligibility.
When you use the pre-qualification tool, the bank uses a soft credit pull. Unlike a hard pull, a soft pull is not visible to other lenders and does not affect your FICO or VantageScore. It is essentially a "peek" at your credit file to see if you meet the baseline criteria for specific products.
A formal pre-approval, on the other hand, often refers to "firm offers of credit" that you might receive in the mail or via email. These are generated when a lender buys a list of names from credit bureaus that meet specific criteria. However, even with a pre-approved firm offer, you still have to go through the final application process, where a hard inquiry will eventually occur.
Disclaimer: This article is for informational purposes only and does not constitute formal financial, legal, or tax advice. Credit card terms, interest rates, and eligibility requirements are subject to change based on lender policies and federal regulations.
Prerequisites for Capital One Pre-Qualification
Before sitting down to fill out the digital form, ensure you have the necessary information and meet the basic eligibility criteria. Capital One’s algorithms are precise; missing or inaccurate data can lead to an "unable to match" result.
1. Personal Identification Information
You must be at least 18 years old and a legal resident of the United States. You will need:
- Full Legal Name: As it appears on your government-issued ID.
- Social Security Number (SSN): Required to match your identity with records at the major credit bureaus (Equifax, Experian, and TransUnion).
- Date of Birth: To verify age and identity.
2. Residential Information
Capital One requires a physical U.S. address. They generally cannot process pre-qualifications for P.O. Boxes without a linked physical residence. If you have moved within the last two years, having your previous address ready is helpful in case the system cannot find your current record.
3. Financial Data (Income and Expenses)
This is where many applicants hesitate. Capital One needs to calculate your Debt-to-Income (DTI) ratio.
- Total Annual Income: You should include your personal salary, but under the Credit CARD Act of 2009, if you are over 21, you can also include income to which you have a "reasonable expectation of access." This includes a spouse's income, shared household funds, or allowances.
- Employment Status: You will select from options such as employed, self-employed, retired, or student.
- Monthly Rent or Mortgage Payment: This helps the bank determine how much of your monthly income is already committed to housing.

Step-by-Step Guide to the Pre-Qualification Process
The process is designed to be completed in under five minutes. Follow these steps to ensure accuracy.
Step 1: Access the Official Tool
Navigate to the Capital One homepage and look for the "Credit Cards" tab. Select "See if You're Pre-Approved" or "Check for Offers." Ensure you are on the capitalone.com domain to protect your sensitive information from phishing attempts.
Step 2: Enter Your Identity Details
Input your name, date of birth, and SSN. Capital One uses encryption to protect this data. The SSN is the most critical component because it allows the system to pull your "soft" file from the credit bureaus instantly.
Step 3: Provide Financial and Contact Details
Enter your residential address, email, and phone number. When prompted for income, provide a gross annual figure (before taxes). Accuracy here is vital; if you are eventually approved, Capital One may request pay stubs or tax returns to verify these numbers during a "manual review" process.
Step 4: Specify Your Goal (Optional but Helpful)
The tool often asks what you are looking for in a card: "Cash Back," "Travel Rewards," or "Building Credit." Selecting an option helps the algorithm prioritize which cards to show you if you qualify for multiple products.
Step 5: Review and Submit
Double-check all entries. A simple typo in your SSN or address will result in a failure to find your credit file. Once you click "See My Offers," the system will communicate with the credit bureaus and return a result, usually within 30 to 60 seconds.
Interpreting Your Results
Once the search is complete, you will see one of three outcomes:
- Matched Offers: You will see a list of specific cards (e.g., Venture, Quicksilver, SavorOne). These are the cards Capital One believes you have a high probability of being approved for.
- No Offers Available: This does not necessarily mean you have "bad" credit. It may mean your credit file is "thin" (not enough history) or that you have recently opened too many accounts.
- Specific "For Good Credit" Versions: Capital One often offers different versions of the same card. For example, the "VentureOne for Excellent Credit" might have a sign-up bonus, while the "VentureOne for Good Credit" does not. Pay close attention to these distinctions.
Capital One Credit Tiers and Card Mapping
Capital One categorizes applicants into specific tiers. Understanding where you fall can help you predict which cards you will see during pre-qualification.
| Credit Tier | Characteristics | Likely Card Matches |
|---|---|---|
| Excellent | Never missed a payment; 5+ years of credit history; high limits on other cards. | Venture X, Venture, Savor |
| Good | No late payments in the last year; 3+ years of history; responsible use. | Quicksilver, SavorOne, VentureOne |
| Fair | Limited credit history (under 3 years) or a few past mistakes. | Platinum, QuicksilverOne |
| Rebuilding | Significant past credit issues or brand new to credit. | Platinum Secured, Quicksilver Secured |
Factors That Influence Pre-Qualification Success
While the software does the heavy lifting, several underlying factors determine whether you see the "Venture X" or a "Platinum Secured" card.
The "One-in-Six" Rule and Velocity
Capital One generally limits consumers to one new card every six months. If you have recently opened a Capital One account, the pre-qualification tool may not show you any new offers until that six-month window has passed. This is part of their "velocity" check to prevent credit "churning."
Card Limits
Historically, Capital One had a "two-card limit" for its core branded cards (excluding co-branded store cards like the Union Privilege or various retail cards). While this rule has become more flexible in 2026, if you already hold multiple Capital One products, you may find fewer options available in the pre-qualification tool.
Credit Utilization
If your current credit cards are maxed out (high utilization), the tool may decline to show offers even if your payment history is perfect. Aim to keep your utilization below 30% across all cards before checking for pre-qualification to maximize the quality of the offers you receive.
What Happens After Pre-Qualification?
If you see an offer you like, the next step is the formal application. It is important to remember that pre-qualification is not a guaranteed approval.
When you click "Apply Now" from the pre-qualification screen, you are consenting to a hard credit inquiry. At this stage, Capital One will perform a deep dive into your credit reports from all three major bureaus (Equifax, Experian, and TransUnion). This "triple-pull" is unique to Capital One and provides them with a very comprehensive view of your financial health.
The final approval depends on:
- Verification of Income: Ensuring the numbers you typed match reality.
- Recent Credit Activity: Ensuring you didn't open three other cards in the five minutes between pre-qualification and application.
- Identification Verification: Occasionally, you may be asked to upload a photo of your Driver’s License or a utility bill.
Troubleshooting Common Issues
If you receive a message saying "We cannot match your information," or if you are declined for pre-qualification, consider these common culprits:
- Credit Freeze: If you have frozen your credit files at Equifax, Experian, or TransUnion to prevent identity theft, the pre-qualification tool cannot work. You must temporarily lift (thaw) the freeze before using the tool.
- Recent Name Change: If you recently married or changed your name and haven't updated it with the Social Security Administration or your existing creditors, the "match" might fail.
- Errors on Credit Report: An incorrect SSN or a collection account you weren't aware of could be tanking your eligibility. Check your reports for free at
annualcreditreport.com.
Frequently Asked Questions
Does checking for pre-qualification hurt my credit score?
No. Checking for pre-qualification uses a soft inquiry, which has zero impact on your credit score. Only the formal application that follows a pre-qualification results in a hard inquiry.
How accurate is the Capital One pre-qualification tool?
It is highly accurate, but not 100%. Because a soft pull doesn't provide the lender with every single detail of your report, a "hidden" issue—such as a specific type of public record or a very recent late payment not yet updated—could lead to a denial during the full application.
Why was I pre-qualified for a card but then denied the application?
This usually happens for three reasons: your credit file was frozen during the hard pull, Capital One could not verify your income, or there was a significant change in your credit report between the time of pre-qualification and the final application.
Can I get pre-qualified if I am not a U.S. citizen?
You must be a permanent resident or have a valid Social Security Number/ITIN and a U.S. physical address. Capital One typically requires an SSN for the online pre-qualification tool to function correctly.
How often should I check for pre-qualification?
You can check as often as you like since it doesn't hurt your score. However, Capital One’s offers typically don't change daily. Checking once every 30 days is a reasonable cadence if you are waiting for your credit score to improve.
Practical Recommendation
If you are looking to add a Capital One card to your wallet in 2026, always use the pre-qualification tool first. There is no tactical advantage to skipping this step and going straight to a cold application. By using the tool, you can see which specific version of a card you are eligible for—such as the version with a $200 sign-up bonus versus the version with no bonus.
Once you receive your matches, compare the annual fees and rewards structures carefully. If you are matched for a "Secured" card, it indicates that your credit needs more work before you can access the "Unsecured" premium travel rewards cards. In that case, accepting the secured offer and using it responsibly for six to twelve months is the fastest path to eventually qualifying for the Venture or Savor lines.
Image Gallery
Select an image to open it in a new tab.



Celine Dubois
Contemporary Living and Global Arts Columnist
