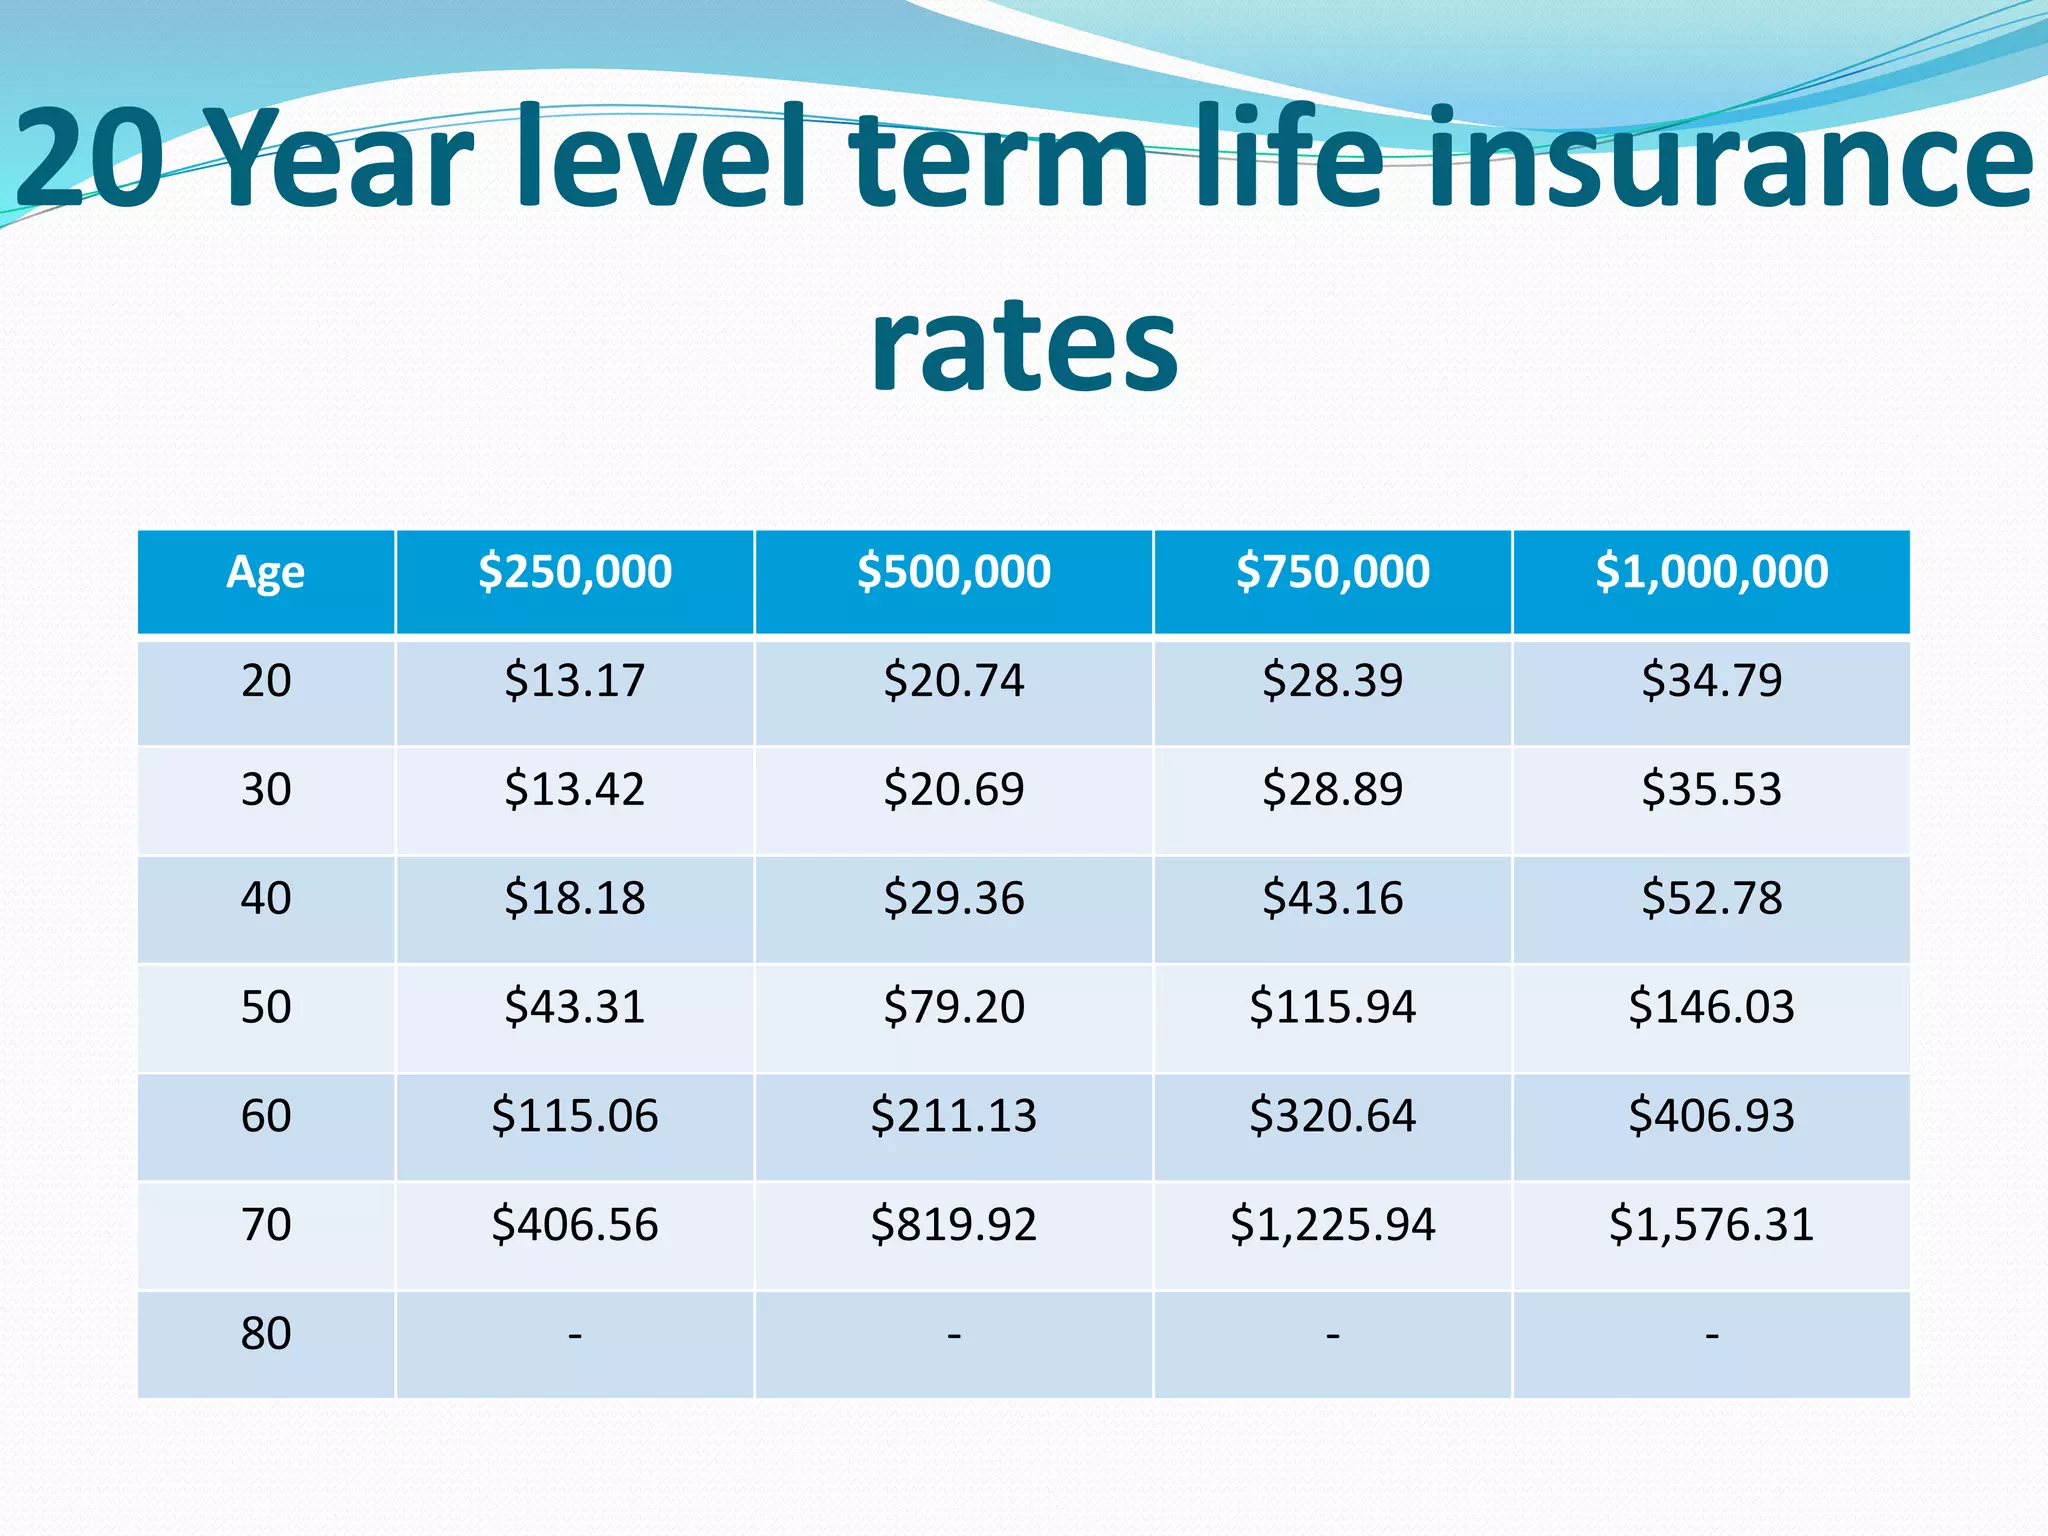
A term life insurance rate chart by age provides a snapshot of the premiums typically charged by insurance carriers for a set death benefit over a fixed period. These charts serve as a reference tool for consumers to estimate their potential costs based on their age at the time of application, illustrating how mortality risk increases as an individual grows older and, consequently, how premium expenses trend upward.
Understanding these charts requires looking beyond the raw numbers to identify the variables that determine your final premium. While age is the primary factor, insurance underwriters rely on medical history, lifestyle habits, and occupation to adjust these baseline rates. Because term life insurance is a temporary product—usually lasting 10, 15, 20, or 30 years—the price you lock in today remains constant for the duration of the term, regardless of how your health changes later.
The Mechanics of Mortality Risk and Premium Pricing
Life insurance companies operate on the principle of pooling risk. Actuaries analyze historical mortality data to predict the likelihood of a payout within a specific demographic group. When you look at a low term life insurance rate chart, you are seeing the results of these actuarial calculations.
As you age, your statistical probability of death within the term period increases. For an insurer, this translates to a higher risk of having to pay out the death benefit. To offset this, companies raise the premium requirements for older applicants. This is why a 25-year-old generally receives much lower quotes than a 55-year-old for the exact same coverage amount. The chart is essentially a reflection of this mathematical curve: the closer you are to a higher risk age bracket, the more the cost of "buying" a guaranteed death benefit rises.
It is important to note that these charts are typically categorized by "health classes." A standard chart may show rates for "Preferred Plus" (excellent health), "Standard" (average health), and "Substandard" (elevated risk due to health or lifestyle). If you are looking at a chart, ensure you identify which health class applies to you, as the price disparity between a "Preferred" and a "Standard" rating can be significant.
How to Interpret the Rate Chart Variables
When reviewing a rate chart for 2026, you will likely encounter several columns that define the policy. Understanding these is essential for accurate cost estimation.
- Term Length: This is the duration of the policy. A 10-year term is often the cheapest because the window of risk for the insurer is shorter. A 30-year term is more expensive because the insurer must cover you through older ages, where the risk of mortality is higher.
- Death Benefit Amount: This is the face value of the policy. Charts are usually broken down by coverage tiers, such as $250,000, $500,000, or $1,000,000.
- Age at Issue: This is your age at your last birthday (or nearest birthday, depending on the carrier). Insurers use this age to lock in your rate for the entire term.
- Tobacco Status: Almost every chart will separate "Tobacco" from "Non-Tobacco" rates. Because tobacco usage is a primary indicator of health decline, premiums for smokers are significantly higher than for non-smokers across all age groups.
Comparative Factors in Life Insurance Costs
While the chart provides a baseline, it rarely reflects the final amount you will pay. Most rate charts are based on "preferred" or "standard" risk profiles. Your actual application process may result in a different premium based on the following:
- Medical Underwriting: You may be required to undergo a paramedical exam. If results show high blood pressure, elevated cholesterol, or other markers, the insurer may classify you into a higher-priced tier.
- Lifestyle Risks: Factors like extreme sports, high-risk occupations (e.g., commercial diving or private aviation), and even international travel habits can influence the final rating.
- Family History: A history of hereditary diseases, such as early-onset heart disease or certain cancers in immediate family members, can occasionally lead to an increased premium or a decline in coverage.
- Policy Fees: Most companies charge a "policy fee" or "modal factor," which is a flat fee added to the premium to cover administrative costs. This fee is often not reflected in base rate charts but is included in your actual bill.
Common Misconceptions About Rate Charts
Many consumers assume that a rate chart is a definitive price list. In reality, it is a guideline for what a "perfectly healthy" person might pay. A common mistake is selecting a policy based on the lowest price on a chart without understanding that the underwriting process might reclassify you to a more expensive tier.
Another frequent error is failing to account for the "conversion privilege." Many term policies allow you to convert to permanent insurance later without another medical exam. While this isn't on the rate chart, it is a critical component of the policy's value. If you only look at the lowest price on the chart, you might purchase a policy that lacks the specific conversion rights you might need in the future.
Summary of Term Life Insurance Cost Factors
| Factor | Impact on Premium | Note |
|---|---|---|
| Age | High | Premiums rise significantly with every year of age. |
| Health Class | High | Preferred/Elite status offers the lowest rates. |
| Tobacco Use | Very High | Smokers pay 2–3 times more on average. |
| Term Duration | Medium | Longer terms have higher premiums due to locked-in risk. |
| Policy Fee | Low | Usually a flat fee added by the insurance company. |
Frequently Asked Questions
Why do premiums increase as I get older? Premiums increase because the statistical likelihood of mortality increases with age. Insurance companies must collect enough premium dollars to cover the eventual payout, and since an older person is closer to the end of the term period, the insurer has fewer years to collect premiums before the payout risk peaks.
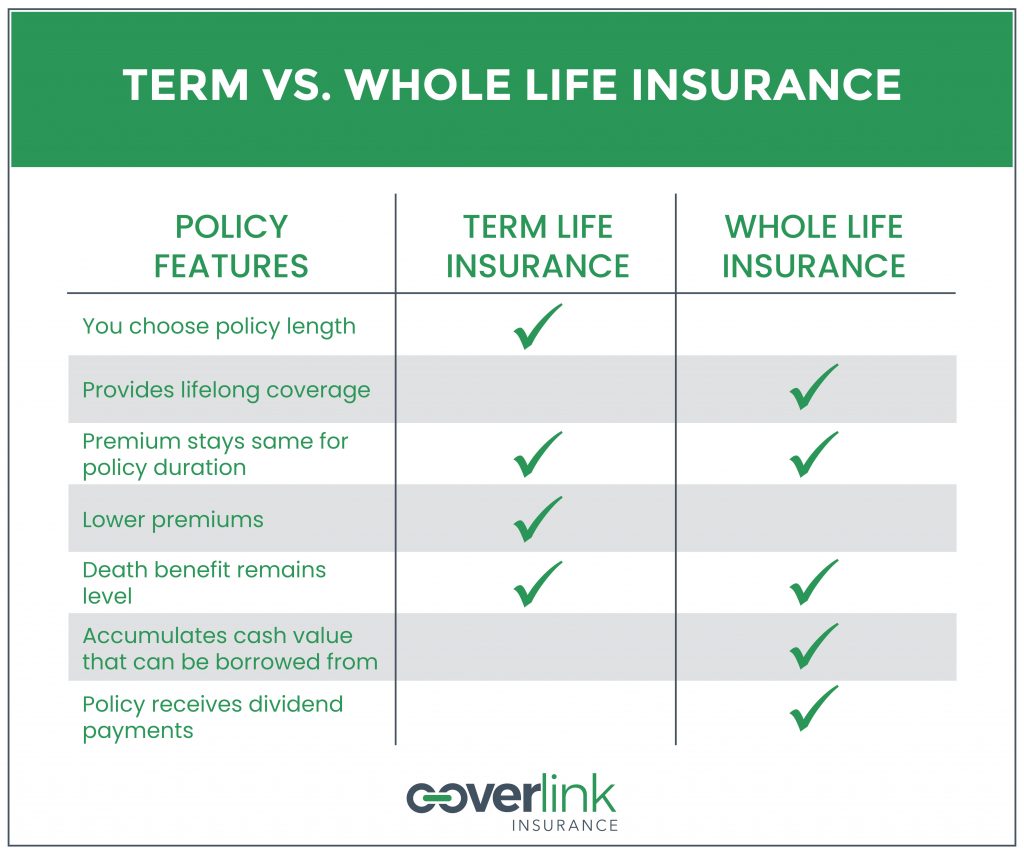
Can I lock in a low rate for my entire life? Term life insurance only locks in your rate for the specific term length (e.g., 20 years). Once that term ends, the policy expires or becomes prohibitively expensive if renewed annually. For coverage that lasts your entire life, you would need to look at permanent life insurance options like Whole Life or Universal Life, which operate under different pricing structures.
Does my gender affect the rate chart? Yes. Statistically, women tend to have higher life expectancies than men. Because the mortality risk is lower, females generally see lower rates on a term life insurance rate chart than males of the same age and health profile.
What happens if my health changes after I buy the policy? One of the primary benefits of term life insurance is that your premium is guaranteed to remain level for the duration of the term. If you develop a health condition three years into a 20-year term, your premiums will not increase, provided you keep the policy active.
How do I know if I qualify for the "Preferred" rates on a chart? "Preferred" or "Preferred Plus" ratings typically require not just the absence of major health conditions, but also specific biometric measurements like ideal blood pressure, cholesterol levels, and a body mass index (BMI) within a specific range. Your insurance agent or the company’s underwriting guidelines will provide the exact thresholds.
Are online rate charts accurate? Online rate charts are useful for estimation but are rarely 100% accurate for your specific situation. They provide a "starting price." Always request a personalized illustration from a licensed broker once you have provided preliminary health and lifestyle information to get a more accurate expectation of your actual premium.
Next Steps for Evaluating Coverage
If you are currently reviewing rate charts, your next step should be to move from general research to specific evaluation. Obtain a quote from a licensed insurance professional who has access to multiple carriers. Because every insurance company uses a slightly different "mortality table"—the technical document that informs their rate charts—one company might view your specific health profile as "Standard," while another might view it as "Preferred."
Comparing these differences can save you thousands of dollars over the life of a 20- or 30-year policy. Always prioritize the financial strength of the insurance carrier (often denoted by A.M. Best ratings) alongside the premium cost. A lower rate is only valuable if the company has the financial stability to honor the death benefit decades in the future.

Image Gallery
Select an image to open it in a new tab.


Celine Dubois
Contemporary Living and Global Arts Columnist
