
Minnesota life insurance premiums are increasing in 2026 due to a confluence of persistent inflationary pressures on carrier operations, updated actuarial tables reflecting recent shifts in mortality data, and increased costs in the global reinsurance market. Additionally, evolving state regulatory requirements and a "higher-for-longer" interest rate environment have fundamentally altered how insurers price long-term risk.
The Macroeconomic Landscape: Inflation and Interest Rates in 2026
To understand why life insurance costs are rising in Minnesota, one must first look at the broader economic environment. While life insurance is often viewed as a static product, it is deeply sensitive to the same inflationary forces that affect healthcare and general consumer goods. In 2026, the cumulative impact of inflation over the past several years has significantly increased the operational costs for insurance carriers. These costs include everything from the salaries of specialized medical underwriters to the technological infrastructure required to manage policyholder data securely.
Furthermore, the interest rate environment plays a paradoxical role in premium pricing. Historically, higher interest rates are beneficial for life insurance companies because they can earn more on the "float"—the premiums they collect and invest before paying out claims. However, in the 2026 economy, the benefit of higher yields on corporate bonds and Treasuries has been partially offset by the increased cost of capital and the need for insurers to maintain higher cash reserves to combat market volatility.
For consumers in the North Star State, this means that even if a carrier's investment portfolio is performing well, the underlying cost of "doing business" has risen so sharply that those gains are not always passed down in the form of lower premiums. Instead, carriers are adjusting their pricing models to ensure they remain solvent for the 30 to 50 years a policy might remain in force.
Actuarial Shifts: Modern Mortality Trends
Life insurance is fundamentally a game of mathematical probability. Actuaries—the professionals who calculate risk—rely on mortality tables to determine how much to charge for a specific death benefit. In recent years, and leading into 2026, these tables have undergone significant revisions.
The "long-tail" effects of the early 2020s health crises are now fully integrated into actuarial models. While the immediate spikes in mortality have leveled off, insurers are observing trends in chronic conditions, such as late-stage cancer diagnoses and cardiovascular issues, which some experts attribute to delayed screenings during previous years. Additionally, "deaths of despair"—including substance abuse and mental health-related incidents—have remained stubbornly high across the Midwest, including Minnesota.
When mortality expectations rise even slightly, the "cost of insurance" (COI) within a policy must increase. For term life insurance, this results in higher quotes for new applicants. For permanent life insurance policies, such as Universal Life (UL), it can lead to higher internal charges that may require policyholders to increase their out-of-pocket payments to prevent the policy from lapsing.
Minnesota-Specific Regulatory and Legal Factors
The Minnesota Department of Commerce oversees the state's insurance industry, ensuring that companies remain solvent and treat consumers fairly. While Minnesota remains a robust market for insurance, state-specific mandates and regulatory updates in 2026 have influenced pricing.
Minnesota has long-standing protections for policyholders, including specific requirements for "non-forfeiture" values and grace periods. In 2026, new data privacy regulations and cybersecurity requirements have been implemented to protect Minnesotans' sensitive medical and financial information. While these laws are beneficial for consumer protection, the compliance costs for insurers are often reflected in the premium.
Furthermore, Minnesota's unique demographic profile—an aging population that is generally healthier than the national average but faces specific regional health challenges—means that carriers must tailor their risk pools specifically to the state. As the population of the Twin Cities and greater Minnesota ages, the concentration of risk in certain age brackets can lead to localized premium adjustments that differ from national averages.
The Impact of Global Reinsurance Markets
Most people are unaware that their life insurance company also buys insurance. This is known as reinsurance. Reinsurance companies take on a portion of the risk from primary insurers in exchange for a share of the premium. In 2026, the global reinsurance market has tightened significantly.
Reinsurers have faced massive payouts due to climate-related disasters and global health trends over the last decade. Consequently, they have raised their rates for primary carriers. When a carrier in Minnesota sees its reinsurance costs go up by 10% or 15%, it is almost inevitable that some of that cost will be passed down to the consumer. This is especially true for "jumbo" policies—those with death benefits exceeding $5 million—where the primary insurer almost always relies on reinsurance to manage the risk.
Technological Underwriting and "Big Data"
In 2026, the way life insurance is priced has changed. We have moved away from simple blood draws and towards "accelerated underwriting." This process uses algorithms to analyze a wide array of data points, including prescription drug histories, motor vehicle records, and even credit scores.
While accelerated underwriting is faster, it isn't always cheaper. The technology required to run these predictive models is expensive. Moreover, as these models become more precise, they are better at identifying "micro-risks" that might have been missed in the past. If the data suggests that a specific demographic in Minnesota has a slightly higher risk of a particular health outcome, the premium will reflect that precision.
Conversely, individuals who are unwilling to share their digital health data or who do not have a robust "data footprint" may find themselves placed in higher-priced "simplified issue" categories, which assume a higher baseline risk.
Comparing Premium Drivers by Policy Type
The reason your premiums are increasing may depend heavily on the type of life insurance you hold. The following table illustrates how various factors impact different policy structures in the 2026 Minnesota market.
| Factor | Term Life Insurance | Whole Life Insurance | Universal Life (UL) |
|---|---|---|---|
| Inflation Impact | High (Pricing for new policies) | Moderate (Fixed premiums) | High (Internal cost of insurance) |
| Interest Rate Sensitivity | Low | High (Affects dividends) | Very High (Affects cash value growth) |
| Mortality Table Updates | Immediate (For new applicants) | Staggered (Long-term projections) | Immediate (Internal charges) |
| Reinsurance Costs | Moderate | Low | High (For large death benefits) |
| Regulatory Compliance | Low | Moderate | High (Due to complexity) |
The Rising Cost of "Riders" and Add-Ons
Many Minnesotans customize their policies with "riders"—extra benefits such as Long-Term Care (LTC) riders, Waiver of Premium, or Chronic Illness accelerators. In 2026, the cost of these riders is increasing faster than the base death benefit cost.
The cost of long-term care in Minnesota—specifically in high-demand areas like Rochester or the Minneapolis-St. Paul metro—has skyrocketed due to labor shortages in the healthcare sector. Because LTC riders are linked to these costs, insurers have had to adjust the premiums for these specific features. If you are looking at a "hybrid" policy that combines life insurance with long-term care, you will likely see a significantly higher premium today than you would have five years ago.
Why Age Is the "Hidden" Multiplier
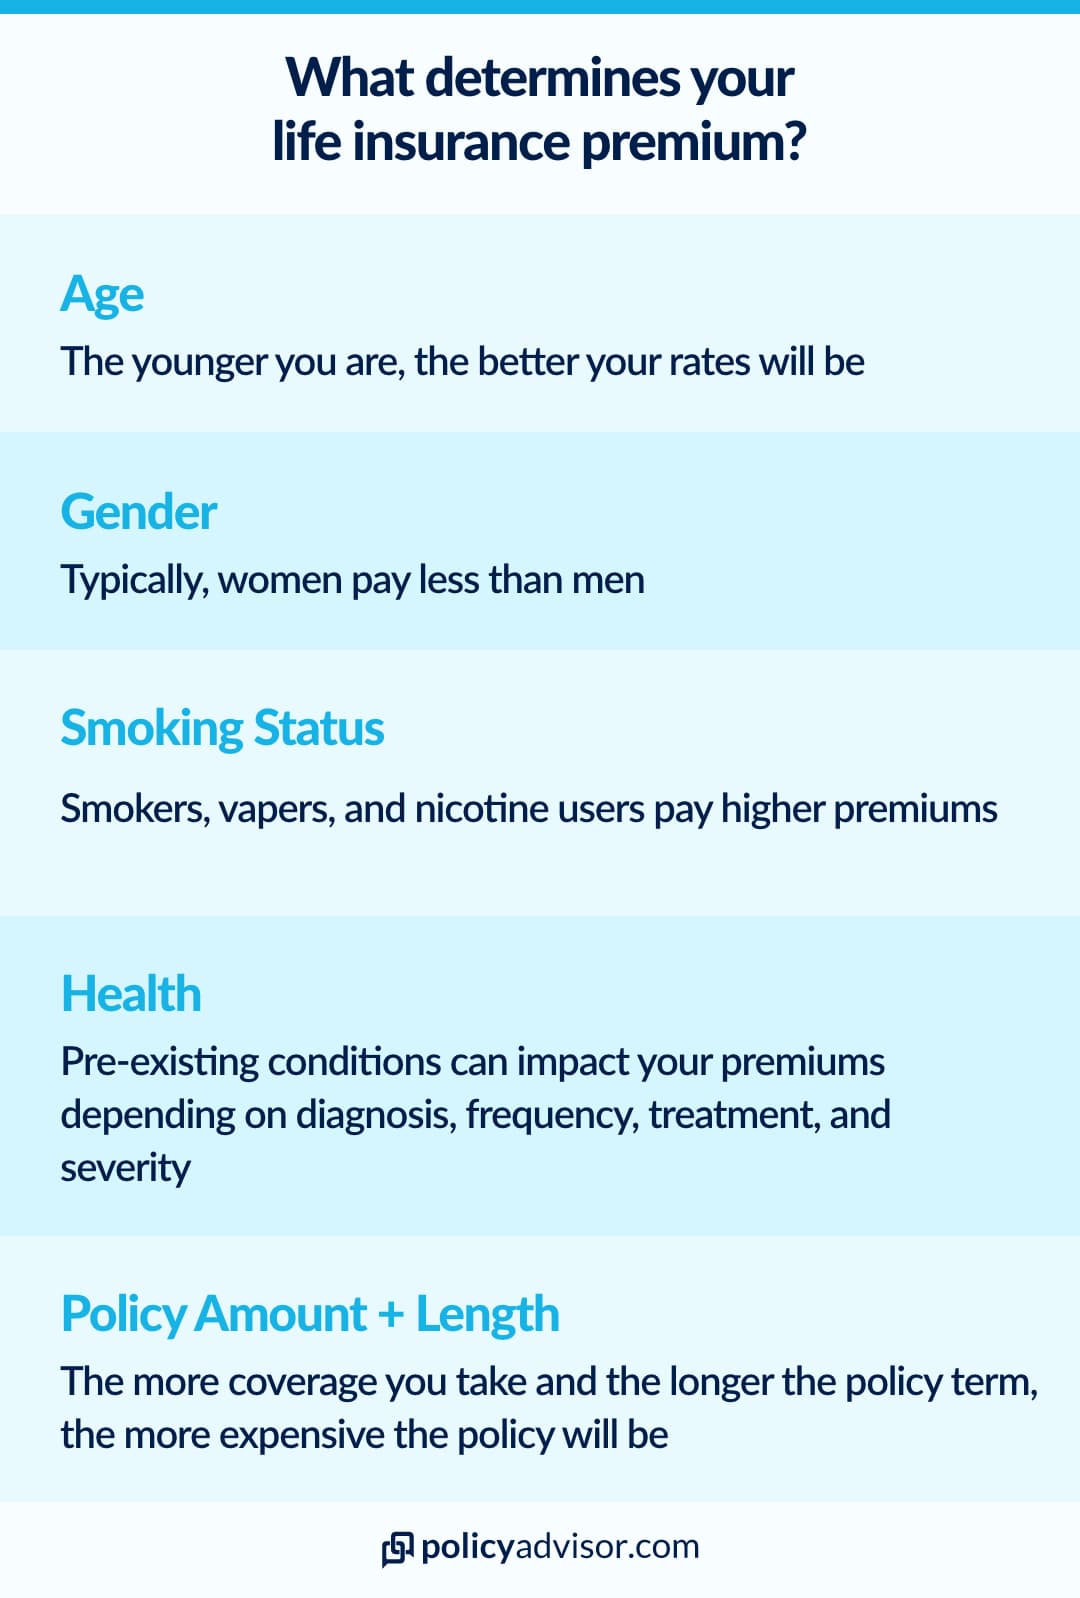
While the factors above explain the systemic reasons for increases, the individual reason for many Minnesotans is simply the "age-up" factor. Life insurance is priced based on your "attained age." For those with renewable term policies, the jump in premium between ages 45 and 55, or 55 and 65, is exponential.
In 2026, because the baseline cost (the "floor") of insurance has risen due to inflation and mortality shifts, the jump between age brackets is more pronounced. A 5% increase in the baseline cost might result in a 20% total increase when combined with the natural age-related risk progression.
How to Mitigate Rising Life Insurance Costs in Minnesota
Despite the upward pressure on premiums, there are several strategies residents can use to keep their coverage affordable:
- Lock in Rates Early: Since premiums for new policies are based on age and health, waiting until next year will almost certainly result in a higher cost.
- Opt for "Laddering": Instead of one large 30-year policy, some Minnesotans are using a "ladder" of shorter-term policies (e.g., a 10-year, a 20-year, and a 30-year) to ensure they have the most coverage when they need it most (while the mortgage is high and kids are home) and less as they get older.
- Review "Artificially High" Coverage: If your children are grown and your house is paid off, you may no longer need a $1 million death benefit. Reducing the face amount can lower the premium significantly.
- Health Improvements: Many carriers in 2026 offer "re-entry" or "re-rating" options. If you have lost weight, quit smoking, or managed your blood pressure effectively for several years, you can request a new medical review to potentially lower your rate.
- Shop the "Minnesota-Heavy" Carriers: Some insurance companies have a larger presence and more historical data in the Midwest. Working with an independent agent who understands the regional landscape can help you find carriers that view Minnesota's demographic risks more favorably.
Frequently Asked Questions
Can a life insurance company raise my premium on a policy I already own?
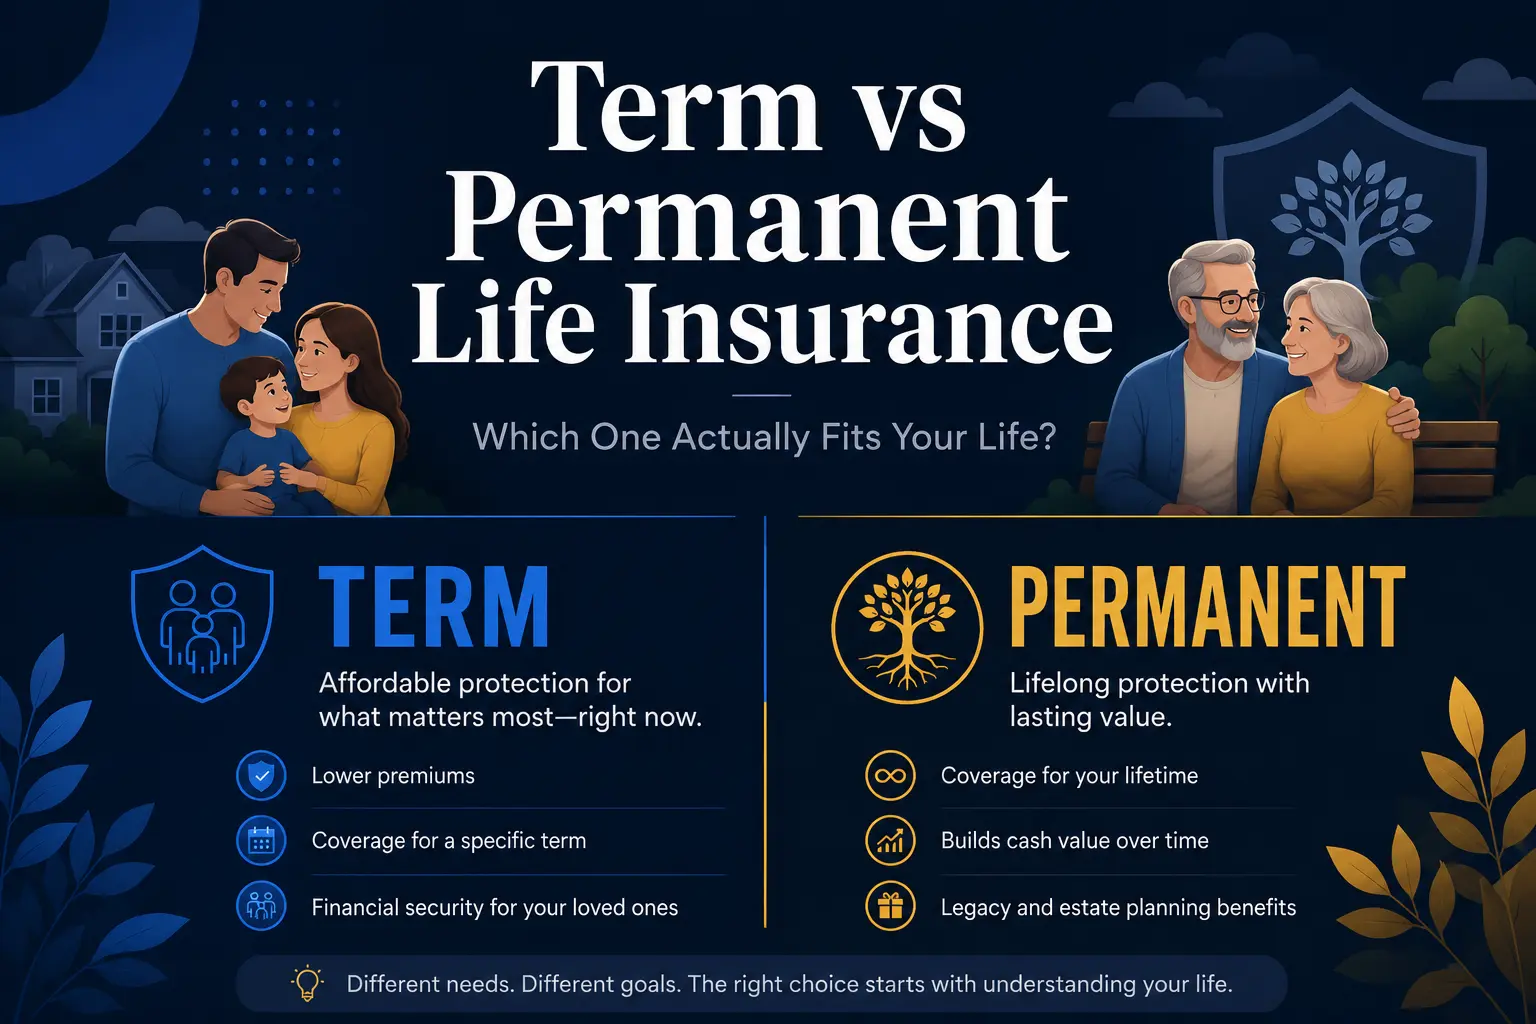
It depends on the policy type. If you have a Level Term or Whole Life policy, your premiums are generally guaranteed and cannot be raised during the term or life of the policy. However, if you have Renewable Term or Universal Life, the company can increase the "Cost of Insurance" (COI) charges or the renewal rate up to a maximum limit specified in your contract.
Why does Minnesota's climate affect my life insurance rates?
While climate doesn't directly set your rate, it affects the "social determinants of health" and the cost of living. In 2026, insurers look at regional data. Minnesota's extreme temperature swings can lead to higher incidences of respiratory or cardiovascular stress in certain populations, which is factored into the aggregate data used by actuaries.
Are premiums higher in Minneapolis than in rural Minnesota?
Generally, no. Life insurance rates are typically set at the state level. However, your access to healthcare and your "lifestyle" (hobbies, occupation) can influence your individual rating. A resident in a rural area with limited access to emergency cardiac care might, in some advanced underwriting models, be viewed differently than someone living blocks away from a major hospital.
Does the Minnesota Life & Health Insurance Guaranty Association protect me?
Yes. The Minnesota Life & Health Insurance Guaranty Association provides a safety net for Minnesotans if their insurance company becomes insolvent. While this doesn't prevent premium increases, it ensures that your benefits are protected up to certain statutory limits, which provides peace of mind in a volatile economic environment.
Will premiums go down if interest rates drop?
Not necessarily. While lower interest rates make it harder for insurers to earn money on investments, they often correlate with lower inflation. However, premiums are "sticky"—once they rise due to mortality table updates or operational costs, they rarely decrease for new applicants unless there is a significant breakthrough in medical technology or longevity.
Final Recommendation: Conduct an Annual Coverage Audit
The landscape of life insurance in 2026 is complex. With the Minnesota Department of Commerce reporting steady shifts in the insurance sector, the best action for any policyholder is to conduct an Annual Coverage Audit.
Compare your current policy's performance against new products entering the market. With the rise of AI-driven underwriting, you may find that your "health profile" is more attractive to a new carrier than it was five years ago, potentially offsetting the systemic price increases. Always consult with a licensed Minnesota insurance professional to ensure that any changes you make do not leave you with a gap in coverage or unexpected tax liabilities.
Image Gallery
Select an image to open it in a new tab.

Vivian Cho
Executive IT and Emerging Technologies Reporter
