To get a Citi card credit limit increase, log in to your account on the Citi website or mobile app, navigate to "Services," and select "Credit Card Services" followed by "Request a Credit Limit Increase." You can also call the number on the back of your card to speak with a representative.
Obtaining a higher credit limit on your Citi credit card is a strategic financial move that can lower your credit utilization ratio and provide greater purchasing power. Whether you are looking to fund a significant upcoming expense or simply want to strengthen your credit profile, understanding the specific mechanisms Citi uses to evaluate these requests is essential. As of 2026, Citi has streamlined its digital interface, making it easier than ever to submit requests, though the underlying criteria for approval remain rooted in your creditworthiness and financial stability.
Why You Should Consider a Credit Limit Increase
Before diving into the "how," it is important to understand the "why." A credit limit increase is not just about having more money to spend; it is a tool for credit score optimization. One of the most significant factors in your FICO score is your credit utilization ratio—the amount of debt you owe divided by your total available credit.
If you have a $5,000 limit and a $2,500 balance, your utilization is 50%, which can negatively impact your score. If Citi increases your limit to $10,000 while your balance remains $2,500, your utilization drops to 25%. This reduction can lead to a prompt increase in your credit score, provided you do not increase your spending proportionally. Furthermore, a higher limit provides a larger safety net for emergencies, allowing you to manage unexpected costs without immediately hitting your credit ceiling.
Prerequisites for a Successful Request
Citi does not grant credit limit increases to every cardmember who asks. To improve your chances of approval in 2026, you should meet several informal and formal prerequisites before submitting your application.
Account Age and History
Generally, Citi prefers that an account be open for at least six months before a credit limit increase is requested. If you have a brand-new card, the bank wants to see a consistent pattern of responsible use and on-time payments before extending further credit. If you have recently received a limit increase, you should typically wait at least six to twelve months before asking for another one.
Credit Score and Payment Record
Your internal standing with Citibank is just as important as your external credit score. Ensure that you have no late payments on any Citi accounts within the last 12 months. Ideally, your overall credit score should be in the "Good" to "Excellent" range (typically 670 or higher). If your score has recently dipped due to high balances or new inquiries, it is wise to wait until it recovers before making a request.
Updated Income Information
Citi’s automated systems often pull from the income data they have on file. If you have not updated your income in the Citi portal for over a year, do so before requesting an increase. Under the Credit Card Accountability Responsibility and Disclosure (CARD) Act, issuers must consider a borrower's ability to pay. If your salary has increased since you first applied for the card, this is a primary lever for securing a higher limit.

Step-by-Step Methods to Request an Increase
Citi provides three primary channels for requesting a credit limit increase. Each has its own workflow, but they all require the same core information: your total annual income and your monthly housing payment.
Method 1: The Citi Mobile App
In 2026, the mobile app is the most common way users interact with their accounts. It is designed for speed and often provides an instant decision.
- Log in to the Citi Mobile App using your biometric data or credentials.
- Select the specific credit card account you wish to manage.
- Tap on the "Services" icon at the bottom of the screen.
- Navigate to "Credit Card Services."
- Select "Request a Credit Limit Increase."
- Input your Total Annual Income and Monthly Housing Payment.
- Review the terms. Citi will usually notify you if the request will result in a "hard pull" (an inquiry that affects your credit score) before you finalize the submission.
- Submit and wait for the instant decision.
Method 2: Citi Online Portal (Desktop)
The desktop experience is similar to the app but offers a more detailed view of your account standing.
- Go to Citibank.com and log in.
- In the top navigation menu, hover over "Services" and select "Credit Card Services."
- Click on the link for "Request a Credit Limit Increase."
- Choose the card you want to update from the dropdown menu.
- Enter your updated financial details.
- Follow the prompts to see if you are eligible for an immediate increase.
Method 3: Calling Customer Service
If the online tool tells you that you aren't eligible to request an increase online, or if you prefer a human touch, you can call the number on the back of your card.
When speaking with a representative, be prepared to explain why you want the increase. Mentioning that you plan to use the card for a large, one-time purchase (like home renovations or a major trip) can sometimes help, provided your income supports it. The representative may also be able to clarify whether the request will require a hard credit inquiry.
The "Hard Pull" vs. "Soft Pull" Distinction
One of the biggest concerns for cardholders is whether a request will damage their credit score. In 2026, Citi’s policy typically follows these guidelines:
- Soft Pull: Most automated requests made through the app or website result in a "soft pull," which does not affect your credit score. Citi uses the information they already have or performs a soft inquiry to check your current standing. If they can approve you based on this, the process is seamless.
- Hard Pull: If you request a significantly higher amount than the system automatically suggests, or if your account requires a manual review by an underwriter, Citi may request a "hard pull" from one of the major credit bureaus (Equifax, Experian, or TransUnion).
Important Tip: Always read the fine print on the submission screen. If Citi intends to perform a hard inquiry, they are legally required to notify you and obtain your consent. If you see a warning about a credit bureau report being pulled, and you don't want your score to take a temporary 5-10 point hit, you should decline the request.
Factors Influencing Citi’s Decision
Citi utilizes sophisticated algorithms to determine creditworthiness. Beyond your income, several "invisible" factors play a role:
| Factor | Description | Impact on Request |
|---|---|---|
| Payment History | Consistency of on-time payments over the life of the account. | High - Must be perfect for at least 6 months. |
| Credit Utilization | How much of your current Citi limit you use each month. | Moderate - Using 10-30% is ideal; using 0% may signal you don't need an increase. |
| Total Exposure | The total amount of credit Citi has extended to you across all their cards. | High - Citi has internal limits on how much total credit they will give one individual. |
| External Debt | Your debt-to-income ratio based on your credit report (mortgages, auto loans, other cards). | Moderate - High external debt can lead to a denial. |
| Inquiry Frequency | How many new credit accounts you have applied for recently. | Moderate - Too many recent "hard pulls" suggest credit seeking behavior. |
How to Handle a Denial
If Citi denies your request, they are required by the Fair Credit Reporting Act (FCRA) to provide an "Adverse Action Notice." This letter, sent via mail or electronic document center, will detail the specific reasons for the denial.
Common reasons include:
- Income is too low for the requested limit.
- Too many recent inquiries on your credit report.
- Low usage of your current credit line (Citi may feel you don't need more credit).
- Delinquency on a current or past account.
If you are denied, do not immediately apply again. Wait at least six months. During this time, focus on paying down existing balances and ensuring every payment is made on time. You might also consider the "Reconsideration Line." While not guaranteed, calling Citi’s reconsideration department allows you to speak with an analyst who can manually review your file and potentially overturn an automated denial if you can provide context for any negative marks.
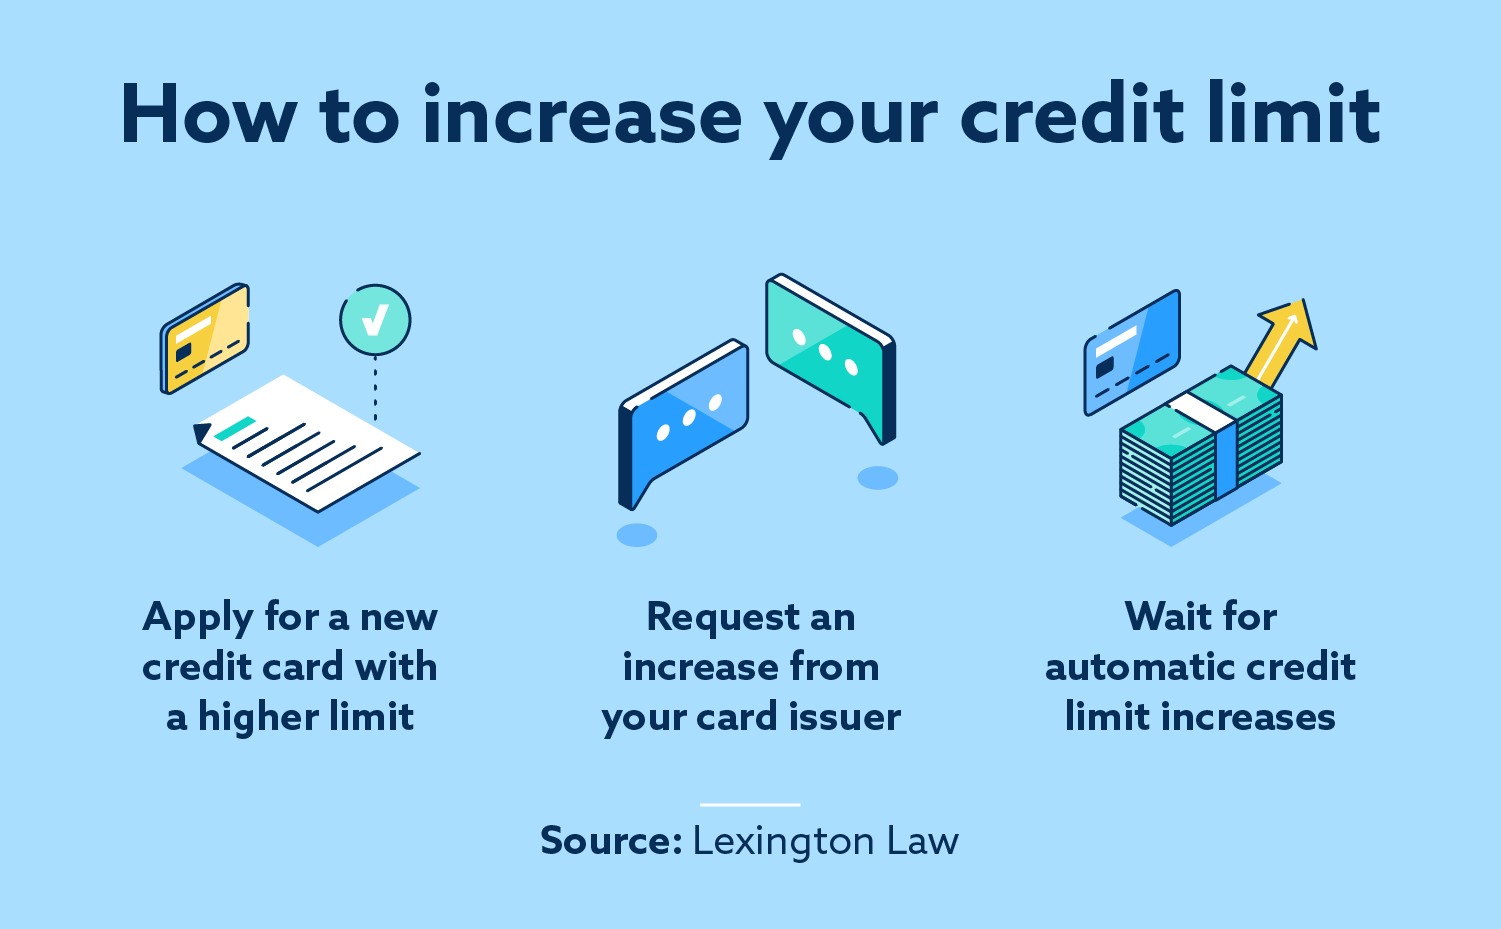
Automatic Credit Limit Increases
Sometimes, you don't have to ask. Citi frequently reviews accounts for automatic limit increases. To position yourself for an "auto-CLI," you should:
- Use the card regularly: Put small to medium purchases on the card and pay them off in full.
- Keep your profile updated: Ensure your income and employment status are current in the app.
- Avoid carrying a maxed-out balance: Showing that you can handle a balance without hitting your limit demonstrates responsibility.
Strategic Timing for Your Request
Timing is everything when it comes to financial applications. The best times to request a Citi credit limit increase include:
- After a Salary Increase: As soon as your new income is reflected in your pay stubs, update your Citi profile and wait one billing cycle before requesting an increase.
- After Paying Off a Large Debt: If you recently finished paying off a car loan or a different credit card, your debt-to-income ratio will improve, making you a more attractive candidate for a higher limit.
- When Your Credit Score Hits a Milestone: Moving from "Fair" to "Good" or "Good" to "Excellent" (e.g., crossing the 740 or 800 mark) is an ideal time to ask.
Frequently Asked Questions
Does requesting a credit limit increase with Citi always result in a hard pull?
No. In 2026, most initial requests via the Citi app or website result in a soft pull. Citi will typically notify you if a hard pull is required to process a higher amount, allowing you to opt out before your credit score is affected.
How much of an increase should I ask for?
If the online tool allows you to input a specific amount, a standard recommendation is to ask for a 10% to 25% increase. Asking for a 100% increase (doubling your limit) is more likely to trigger a manual review and a hard credit inquiry.
How often can I request a limit increase from Citi?
While there is no hard rule, it is best to wait at least six months between successful requests. Frequent requests can be flagged as "credit-seeking behavior," which may lead to denials or even account reviews.
Can I shift credit limits between different Citi cards?
Yes, Citi often allows you to reallocate credit lines between cards you already own. For example, if you have a Citi Premier® with a $10,000 limit and a Citi® Double Cash with a $2,000 limit, you may be able to move $3,000 from the Premier to the Double Cash. This usually requires calling customer service.
Will a credit limit increase lower my interest rate?
Generally, no. A credit limit increase affects your spending power and utilization, but it does not automatically change your APR. If you want a lower interest rate, you must specifically request a "rate reduction" or a promotional APR offer from the customer service department.
Final Recommendations
To successfully get a Citi card credit limit increase in 2026, prioritize the digital channels first. Start by updating your income in the Citi Mobile App and checking the "Services" menu for a pre-approved offer. If no offer is available, proceed with a manual request but remain vigilant for any notifications regarding a hard credit pull. If you are denied, treat the Adverse Action Notice as a roadmap for improvement, focusing on debt reduction and credit score health for the next six months before attempting again.
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
