
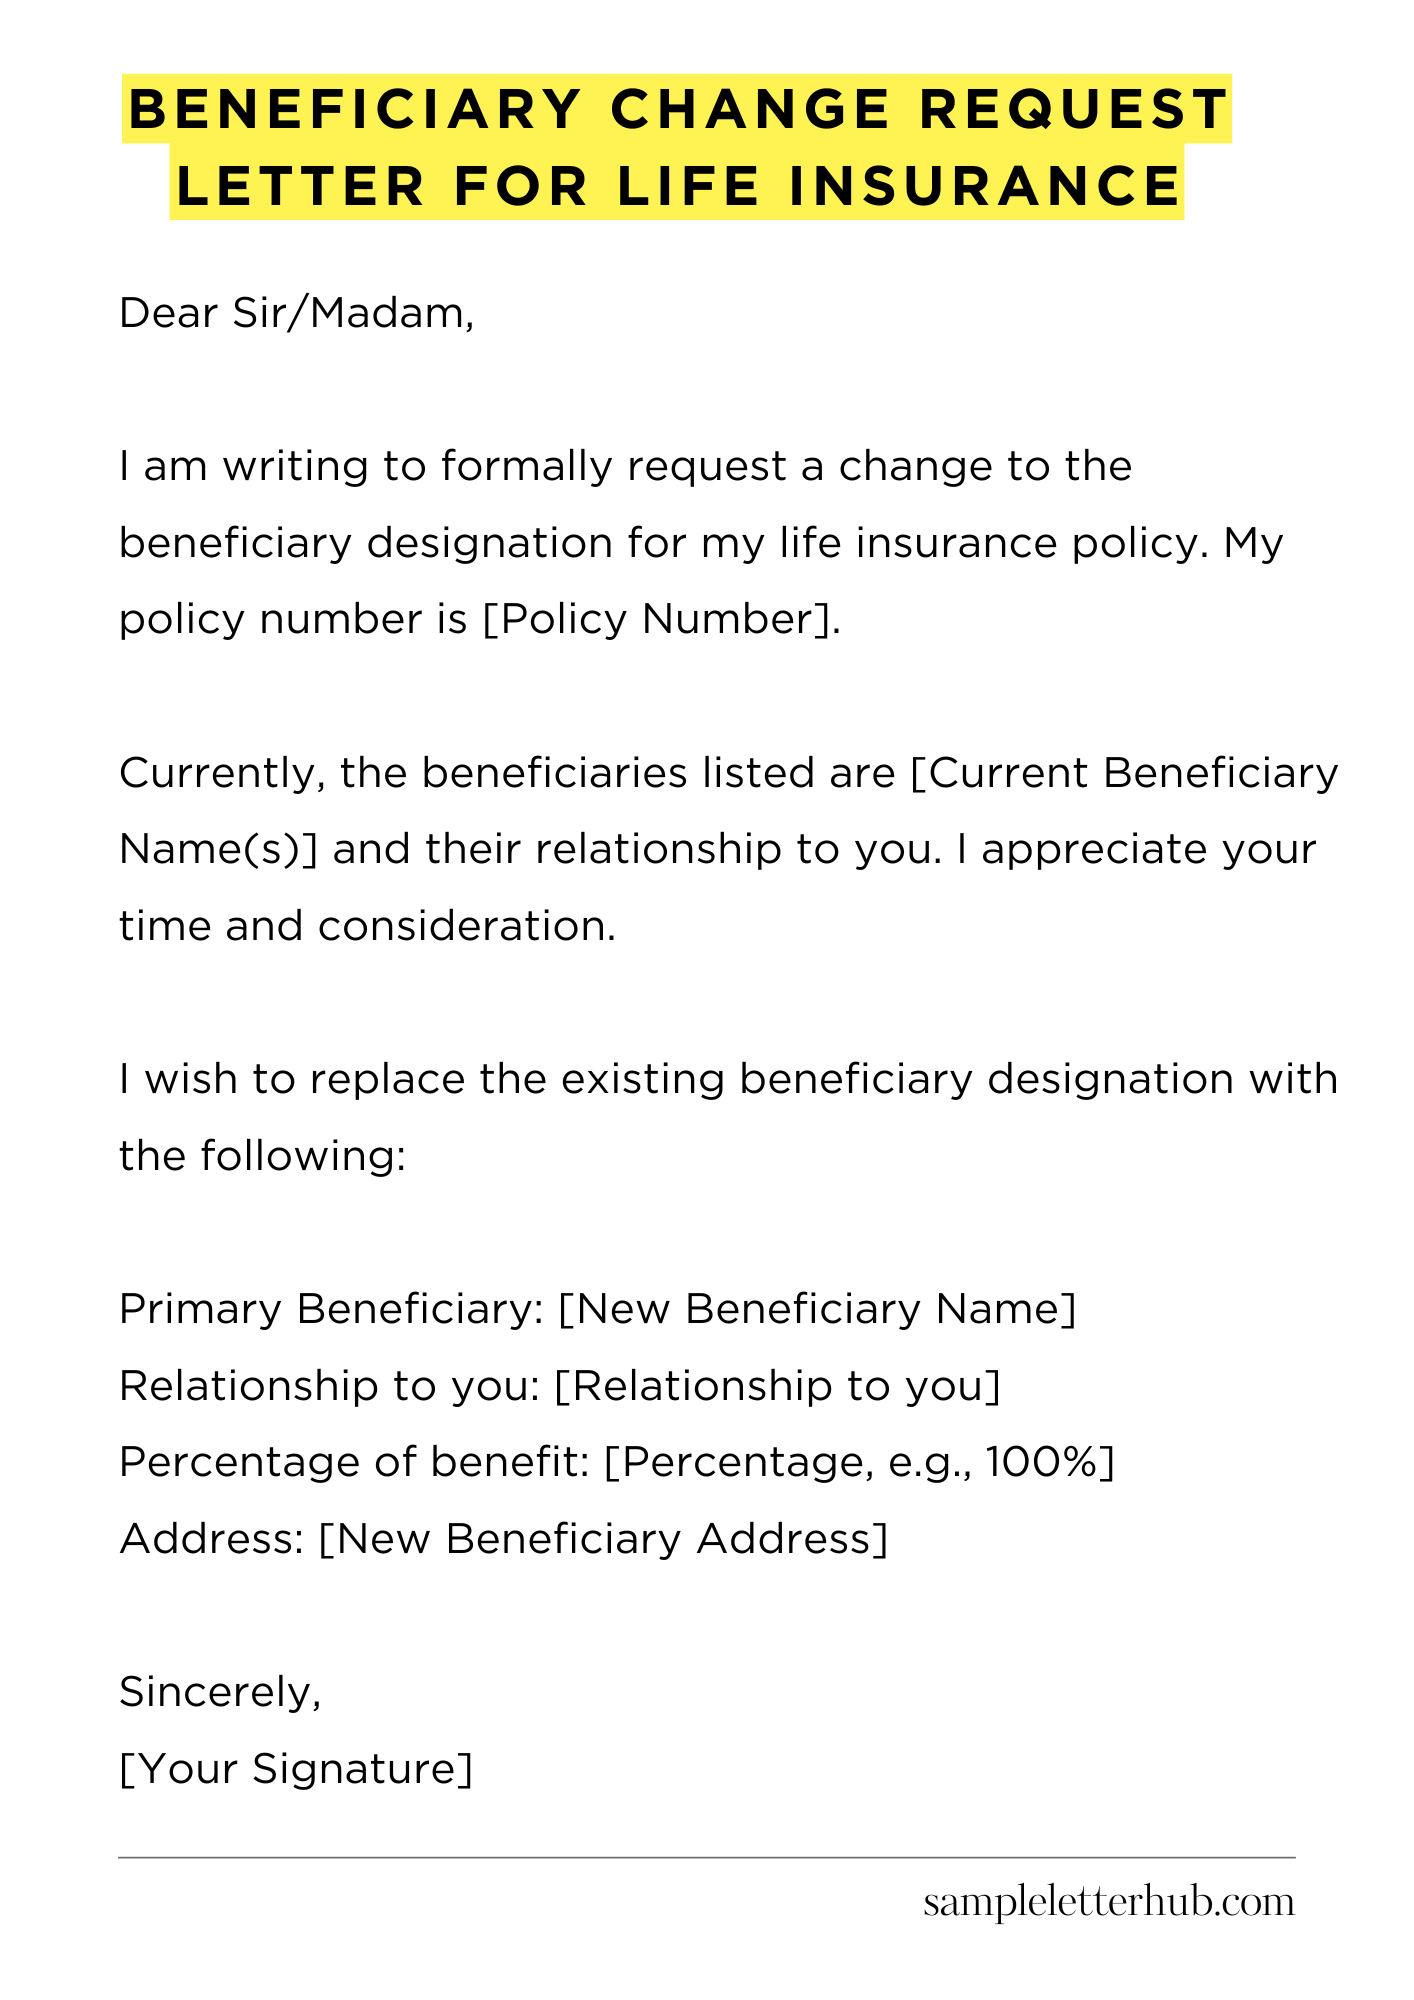
To change your beneficiary on an AIG life insurance policy—now managed under the Corebridge Financial brand—you must log into the Corebridge online owner portal or submit a "Request for Change of Beneficiary" form. This process requires the policy number, the new beneficiary’s Social Security number, and specific allocation percentages totaling 100% for each beneficiary class.
Updating a life insurance beneficiary is one of the most critical aspects of policy maintenance. As of 2026, many policyholders still refer to their coverage as "AIG Life Insurance," though the company’s Life and Retirement division completed its separation and rebranding to Corebridge Financial. Whether you hold a term life, universal life, or whole life policy, the legal requirements for shifting death benefit proceeds remain stringent to ensure the right assets reach the intended hands without unnecessary legal delays.
Understanding the Transition from AIG to Corebridge Financial
Before initiating a change, it is essential to understand the current corporate landscape. In recent years, AIG (American International Group, Inc.) rebranded its life insurance and retirement business as Corebridge Financial.
If your original policy documents bear the AIG logo, your contract remains valid and its terms are legally binding. However, the administrative systems, customer service portals, and physical mailing addresses for beneficiary updates are now branded under Corebridge. When you search for "AIG beneficiary change forms," you will be redirected to the Corebridge Financial service center. This transition does not change your coverage, but it does change where and how you submit your documentation.
Types of Beneficiary Designations
When preparing to update your policy, you must choose how you want the death benefit distributed. Misunderstanding these categories can lead to unintended consequences during the claims process.
Primary vs. Contingent Beneficiaries
A primary beneficiary is the first individual or entity in line to receive the insurance proceeds. You can name one person or multiple people to share the benefit. A contingent (or secondary) beneficiary acts as a backup. They receive the proceeds only if all primary beneficiaries have passed away before the insured or are otherwise ineligible to collect.
Revocable vs. Irrevocable Beneficiaries
Most AIG/Corebridge policies default to revocable beneficiary designations. This means the policy owner can change the beneficiary at any time without the current beneficiary's consent.
However, if a beneficiary is designated as irrevocable, the policy owner cannot change them, cancel the policy, or borrow against the cash value without the written consent of that irrevocable beneficiary. Irrevocable designations are common in divorce settlements or specific trust arrangements.
Per Stirpes vs. Per Capita
These legal terms dictate how money flows if a beneficiary dies before you.
- Per Stirpes: If a named beneficiary dies before you, their share passes down to their children (your grandchildren).
- Per Capita: If a named beneficiary dies before you, their share is redistributed among the remaining surviving beneficiaries at that same level.
Prerequisites for Changing Your Beneficiary
Changing a legal contract requires precision. Before you begin the online or paper application process, gather the following information to avoid "In Good Order" (IGO) rejections from the Corebridge administrative team.
- Policy Number: Found on your annual statement or original policy jacket.
- Full Legal Name: The name of the beneficiary as it appears on their government-issued ID.
- Social Security Number (SSN) or Tax ID: Necessary for tax reporting and identity verification during the claims process.
- Date of Birth: To confirm the identity and age of the beneficiary.
- Current Address and Phone Number: Enables the insurance company to locate the beneficiary quickly upon the death of the insured.
- Relationship to the Insured: (e.g., Spouse, Child, Domestic Partner, Trust).
Step-by-Step Guide to Changing Beneficiaries Online
The digital method is the most efficient way to update your policy in 2026. Electronic updates typically reflect on the account within 24 to 48 hours.
- Access the Portal: Visit the official Corebridge Financial owner portal. If you have not registered your AIG policy yet, you will need your policy number and the last four digits of your SSN to create a login.
- Navigate to Policy Details: Once logged in, select the specific life insurance policy you wish to update.
- Locate "Beneficiary Management": This is usually found under the "Account Services" or "Profile" tab.
- Enter New Details: Click "Edit" or "Add New Beneficiary." Input the names, SSNs, and contact information.
- Set Percentages: Assign a percentage to each beneficiary. For example, if you have two children, you might assign 50% to each. Ensure the total for "Primary" equals 100% and the total for "Contingent" equals 100%.
- E-Signature and Submission: Review the entries for typos. Submit the change using a digital signature.
- Download Confirmation: Always save a PDF copy of the confirmation screen for your records.
How to Change Beneficiaries via Paper Form
If you prefer the traditional method or if your policy requires a physical signature (common with older whole life policies or those involving irrevocable beneficiaries), you must use the standard form.
- Download the Form: Search the Corebridge Financial Forms Library for the "Request for Change of Beneficiary" or "Form 7002."
- Complete the Identification Section: Enter the policy owner's name and the insured's name (often the same person).
- Specify the Change: Clearly print the names of the new primary and contingent beneficiaries. If you are replacing everyone, check the box that indicates "This change supersedes all prior designations."
- Notarization Requirements: Check the form instructions carefully. In some cases, such as policies with very high face values or those in specific jurisdictions, a notary public’s seal may be required.
- Spousal Consent in Community Property States: If you live in a community property state (Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, or Wisconsin) and are naming someone other than your spouse as a beneficiary, your spouse may need to sign a waiver on the form.
- Submission: Mail the completed, signed form to the address listed on the document. In 2026, Corebridge also allows these forms to be uploaded through a secure document upload link on their website or sent via verified fax.
Comparison of Beneficiary Update Methods
| Feature | Online Portal | Paper Form (Mail/Fax) | Agent-Assisted |
|---|---|---|---|
| Processing Speed | 1–3 Business Days | 7–14 Business Days | Varies by Agent |
| Accuracy Check | Real-time validation | Manual review | Manual review |
| Complexity | Best for simple updates | Best for complex/trusts | Best for estate planning |
| Legal Proof | Digital timestamp | Physical copy/Postal receipt | Agent's record |
| Availability | 24/7 | Business hours | Business hours |
Special Considerations for Non-Individual Beneficiaries
Sometimes, naming a specific person is not the most effective way to manage an estate. AIG/Corebridge policies allow for various legal entities to be named.
Naming a Trust
If you name a trust, you must provide the full legal name of the trust, the date the trust was created, and the names of the trustees. Using a trust is often recommended if you have minor children, as life insurance companies cannot pay death benefits directly to minors. The trust manages the funds according to your specific instructions.
Naming an Estate
While you can name "My Estate" as the beneficiary, this is generally discouraged. Proceeds paid to an estate usually have to go through probate, a court-supervised process that can be expensive and time-consuming. Furthermore, assets in an estate are subject to the deceased’s creditors, whereas life insurance paid directly to a named beneficiary is often protected from creditors.
Naming a Charity
Naming a 501(c)(3) non-profit organization is a common strategy for charitable giving. You will need the charity's full legal name and its Federal Employer Identification Number (EIN).
Legal and State-Specific Constraints
Life insurance is regulated at the state level, and certain laws may impact your ability to change your AIG beneficiary.
- Divorce Decrees: In many states, a divorce automatically revokes a spouse’s designation as a beneficiary. However, some court orders (Qualified Domestic Relations Orders) may require you to keep an ex-spouse as a beneficiary to secure alimony or child support.
- Community Property Laws: As mentioned earlier, if the premiums were paid with community funds (income earned during the marriage), the spouse may have a legal claim to a portion of the death benefit regardless of who is named.
- Minor Beneficiaries: If a minor is named without a guardian or trust, the court will likely appoint a "guardian ad litem" to manage the funds until the child reaches the age of majority (18 or 21, depending on the state). This can lead to significant legal fees.
Common Mistakes to Avoid
The consequences of an improperly executed beneficiary change often don't appear until it is too late to fix them. Avoid these common pitfalls:
- Vague Descriptions: Never use phrases like "my children" or "my spouse." Always use legal names. If you have a child after the policy is issued, they may be excluded if you didn't use a "Per Stirpes" designation or update the policy to include their name.
- The 100% Rule: Many forms are rejected because the percentages for the primary beneficiaries add up to 99% or 101%. Double-check your math.
- Forgetting Contingents: If your primary beneficiary dies with you in a common accident and you have no contingent beneficiary, the money goes to your estate, triggering probate.
- Inconsistent Documents: Ensure the beneficiary on your AIG/Corebridge policy aligns with your will or trust. While a life insurance beneficiary designation typically overrides a will, inconsistencies can lead to estate litigation among heirs.
When Should You Review Your Beneficiaries?
A life insurance policy is not a "set it and forget it" document. Financial experts recommend reviewing your AIG/Corebridge beneficiary designations during the following life events:
- Marriage or Remarriage: To include a new spouse.
- Birth or Adoption: To provide for new dependents.
- Divorce: To remove an ex-spouse or comply with a court order.
- Death of a Beneficiary: To reallocate their share to surviving beneficiaries.
- Buying a Home: If the policy is intended to cover a mortgage.
- Change in Tax Laws: Significant updates to estate tax limits (relevant in 2026) may necessitate moving policy ownership to an Irrevocable Life Insurance Trust (ILIT).
Frequently Asked Questions
How long does it take for AIG (Corebridge) to process a beneficiary change?
If submitted through the online portal, changes are typically processed within 24 to 48 hours. Paper forms submitted via mail may take 7 to 10 business days once received at the processing center. You will usually receive a written confirmation via mail or an email notification once the update is complete.
Can I change my beneficiary if the policy is collateral for a loan?
If you have assigned your life insurance policy as collateral for a bank loan (collateral assignment), you may be restricted from changing the beneficiary without the lender's consent. The lender's interest must be satisfied or released before the policy owner regains full control over beneficiary designations.
What happens if I name a minor as a beneficiary on my AIG policy?
Corebridge Financial cannot legally pay a death benefit directly to a minor. If no trust is established, the company will hold the funds in an interest-bearing account until a court-appointed guardian is named, or until the child reaches legal age. This can delay the payout by months or even years.
Can a Power of Attorney (POA) change a beneficiary?
Generally, a person holding Power of Attorney can only change a beneficiary if the POA document specifically grants the authority to "create or change beneficiary designations." Insurance companies scrutinize these requests closely to prevent elder abuse or fraud. You will need to submit a copy of the POA document to Corebridge for legal review.
Does the beneficiary need to sign the change form?
In most cases, no. As the policy owner, you have the unilateral right to change revocable beneficiaries. However, if the current beneficiary is "irrevocable," their signature is mandatory for any changes to take effect.
Final Recommendation
To ensure your life insurance proceeds are distributed according to your current wishes, log into the Corebridge Financial portal today to verify your existing designations. If an update is required, use the digital submission tool for the fastest and most secure processing. After making any change, notify your beneficiaries and provide them with the policy number and the company's contact information to simplify the future claims process.
Image Gallery
Select an image to open it in a new tab.




Declan O'Connor
Higher Education and Campus Culture Reporter
