Long Term Care Pekin Insurance Life Coverage Overview: Hybrid Solutions for 2026
Pekin Insurance provides long-term care coverage primarily through an Accelerated Death Benefit rider attached to its permanent life insurance policies. This "hybrid" approach allows policyholders to access a portion of their life insurance death benefit while still living to pay for qualifying long-term care expenses, such as nursing home stays, assisted living, or home health care.
The Evolution of Pekin Insurance Life Coverage with LTC Benefits
As we navigate 2026, the landscape of elder care has shifted significantly. The traditional model of standalone long-term care (LTC) insurance has become increasingly rare due to rising premiums and unpredictable underwriting. Pekin Insurance has addressed this market gap by focusing on asset-based or "hybrid" life insurance solutions. These products combine the guarantees of life insurance with the living benefits of LTC coverage, solving the "use it or lose it" dilemma that historically discouraged consumers from purchasing standalone LTC policies.
Pekin’s approach centers on the philosophy that life insurance should be a flexible financial tool. For many families, the greatest threat to a retirement nest egg is the astronomical cost of chronic care. By integrating LTC benefits into their LifePro and universal life portfolios, Pekin allows policyholders to leverage their death benefit to offset these costs. If the policyholder never requires care, the full death benefit passes to their beneficiaries, ensuring that the premiums paid always provide a return of value.
Understanding the Accelerated Death Benefit for Long-Term Care
The core mechanism of Pekin’s long-term care coverage is the Accelerated Death Benefit (ADB) rider. Unlike a separate insurance policy, this rider is an endorsement that modifies how the life insurance payout can be distributed. It is essential to understand that using these funds for long-term care reduces the eventual death benefit dollar-for-dollar.
How the Benefit Triggers
To activate the long-term care benefits under a Pekin life policy in 2026, the insured must be certified as "chronically ill" by a licensed health care practitioner. This certification generally requires the policyholder to meet one of two primary criteria:
- Activities of Daily Living (ADLs): The inability to perform at least two of the six standard ADLs without substantial assistance. These include bathing, continence, dressing, eating, toileting, and transferring (moving in or out of a bed or chair).
- Cognitive Impairment: Requiring substantial supervision to protect the individual from threats to health and safety due to severe cognitive impairment, such as Alzheimer’s disease or other forms of dementia.
The Elimination Period
Most Pekin life/LTC hybrid arrangements include an elimination period, which functions like a deductible measured in time rather than dollars. Typically, this period is 90 days. During these 90 days, the policyholder must receive qualified long-term care services and pay for them out-of-pocket before the insurance company begins accelerating the death benefit payments. In 2026, Pekin’s policies often allow these days to be non-consecutive, depending on the specific policy language at the time of issuance, which provides greater flexibility for those transitioning in and out of home care.
Comparing Pekin’s Life Insurance Vehicles for LTC
Pekin Insurance offers different permanent life insurance products that can be equipped with LTC riders. Choosing the right vehicle depends on the policyholder’s premium budget and their need for cash value accumulation.
Whole Life Insurance
Pekin’s Whole Life products provide the most stability. The premiums are guaranteed never to increase, and the death benefit is fixed. When the LTC rider is attached to a Whole Life policy, the policyholder knows exactly how much money is available for care from day one. This is often the preferred choice for individuals in 2026 who are risk-averse and want a "set it and forget it" solution for both legacy planning and potential healthcare needs.
Universal Life Insurance
For those seeking more flexibility, Pekin’s Universal Life (UL) options allow for adjustable premiums and death benefits. In a UL policy, the LTC rider's capacity can scale with the policy’s face amount. However, UL policies require more active management to ensure the cash value remains sufficient to cover the cost of insurance as the policyholder ages. In the current 2026 economic environment, UL policies are often used by younger professionals who want to start their LTC planning early while maintaining the ability to adjust their contributions.
| Feature | Whole Life with LTC Rider | Universal Life with LTC Rider |
|---|---|---|
| Premium Structure | Fixed and Guaranteed | Flexible/Adjustable |
| Cash Value Growth | Guaranteed Minimum | Market-Linked or Declared Rate |
| LTC Benefit Amount | Percentage of Fixed Death Benefit | Percentage of Current Death Benefit |
| Complexity | Low - Easy to manage | Moderate - Requires monitoring |
| Best For | Seniors and Conservative Planners | Wealth Management and Flexible Budgets |
Coverage Scope: Where Can Benefits Be Used?
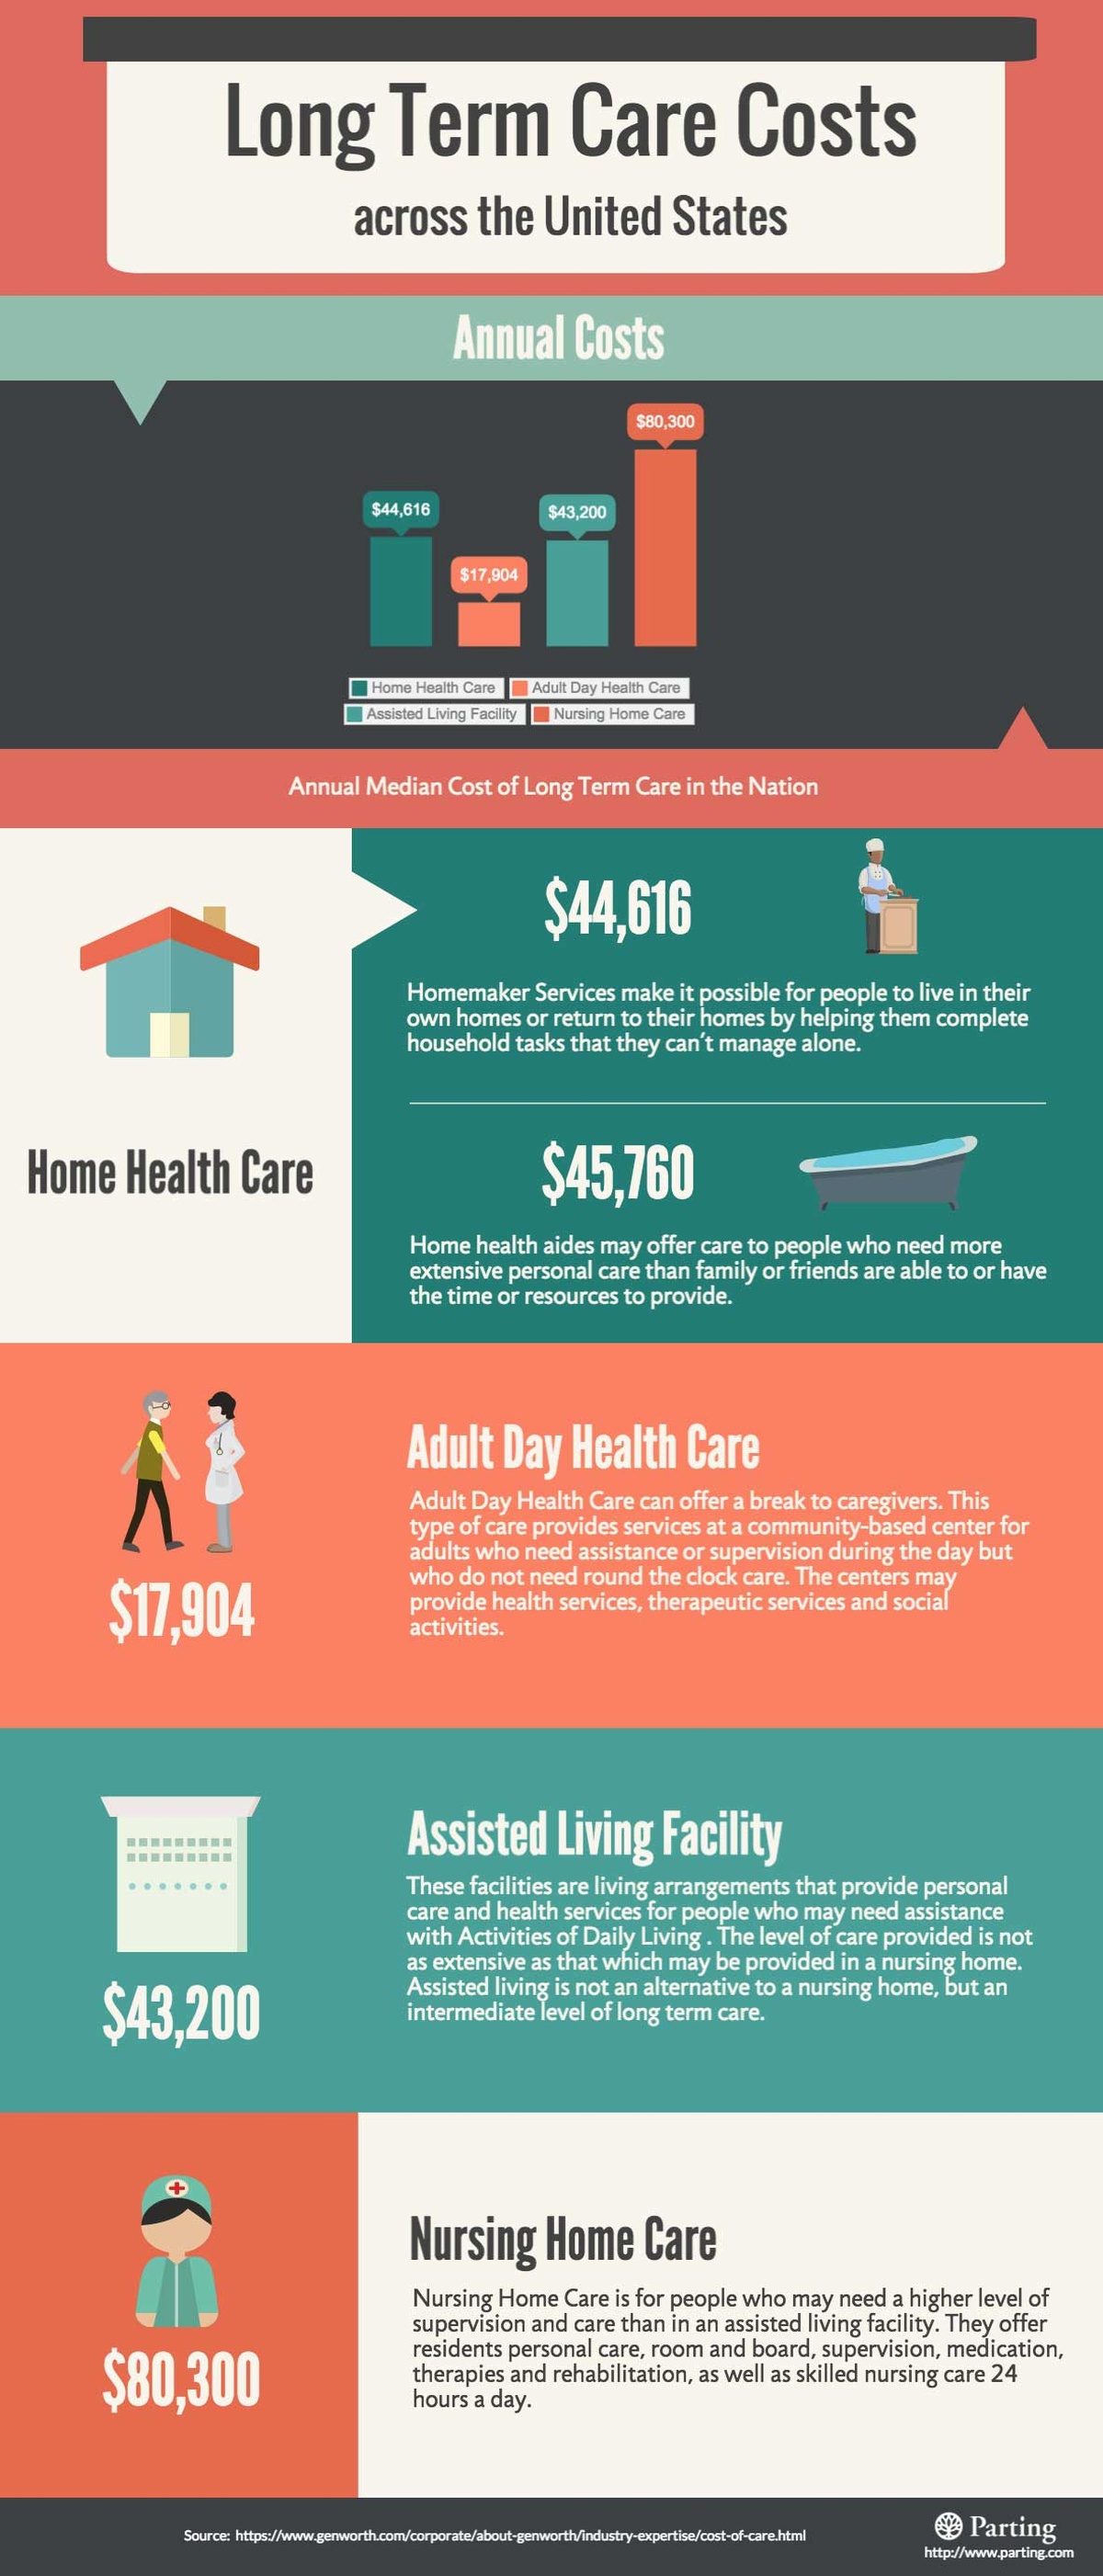
A common misconception is that long-term care insurance only pays for nursing homes. In 2026, Pekin’s LTC riders are designed to be comprehensive, reflecting the modern preference for "aging in place." The accelerated benefits can typically be used for a wide variety of services, provided they are part of a prescribed plan of care.
- Home Health Care: This includes skilled nursing care in the home, as well as assistance with ADLs provided by a home health aide.
- Assisted Living Facilities: For individuals who do not need the full medical apparatus of a nursing home but can no longer live independently.
- Adult Day Care: Community-based programs designed to provide social and health-related services to adults who need supervision during the day.
- Nursing Home Care: Full-scale 24-hour medical and personal care in a licensed facility.
- Hospice Services: End-of-life care that focuses on comfort and support rather than curative treatment.
It is important to note that Pekin typically requires these services to be provided by "qualified" providers. This usually means the facility must be licensed by the state, or the home health aide must be part of a licensed agency. Payments made to family members for informal care are generally not covered under these standard life insurance riders unless specifically stated in a specialized contract.
Costs and Premium Considerations in 2026
The cost of adding a long-term care rider to a Pekin life insurance policy is influenced by several factors. Because the rider allows for the acceleration of the death benefit, the "cost" is often built into the policy’s mortality charges or added as a flat monthly rider fee.
Age and Health at Issue
As with all life insurance products, your age and health at the time of application are the primary drivers of cost. In 2026, underwriting for hybrid policies remains rigorous. Pekin will evaluate your medical history, specifically looking for indicators of future cognitive decline or mobility issues. Obtaining coverage in your 40s or 50s is significantly more cost-effective than waiting until your 60s, as the "cost of insurance" (COI) charges within the policy increase as you age.
Inflation Protection
One of the most critical decisions a policyholder faces in 2026 is whether to add inflation protection to their LTC rider. While the death benefit of a Whole Life policy may be fixed, the cost of a nursing home is certainly not. Pekin offers options to increase the available LTC benefit over time, either through a simple or compound inflation percentage. While this increases the premium, it prevents the benefit from being eroded by the rising costs of healthcare services.
The Claims Process: Accessing Your Benefits
When the need for care arises, the process of "opening a claim" with Pekin Insurance involves several administrative steps. Accuracy during this phase is vital to ensure timely payments.
- Notification: The policyholder or their legal representative (Power of Attorney) must notify Pekin that a chronic illness has been diagnosed.
- Proof of Loss: Pekin will provide claim forms that must be completed by the attending physician. This documentation must clearly state the clinical diagnosis and the specific ADL deficiencies or cognitive impairments.
- Plan of Care: A licensed health care practitioner must submit a written plan of care. This plan outlines the specific services required and the frequency of those services.
- Verification: Pekin’s claims department will review the medical records. In some cases, they may request an independent functional assessment to verify the extent of the impairment.
- Benefit Payouts: Once the elimination period is satisfied, Pekin begins the acceleration of the death benefit. These payments are typically made on a monthly basis, up to a maximum monthly limit specified in the policy (e.g., 2% or 4% of the total death benefit per month).
Financial Strength and Reliability
Choosing an insurance provider for a long-term commitment requires evaluating the company’s financial solvency. Pekin Insurance, founded in 1921, has a long-standing reputation for stability in the Midwest and beyond.
As of 2026, Pekin maintains a strong rating from A.M. Best, a leading credit rating agency focused on the insurance industry. A high rating indicates the company’s ability to meet its ongoing policy and contract obligations. Since LTC claims may not occur for 20 or 30 years after a policy is purchased, the financial "staying power" of the carrier is arguably more important than the initial premium cost.
Common Pitfalls to Avoid
When evaluating Pekin’s life/LTC coverage, many consumers make mistakes that can lead to gaps in protection or unexpected financial strain.
- Underestimating the Monthly Limit: If you have a $500,000 death benefit but your rider only allows you to accelerate 2% per month, your maximum monthly payout is $10,000. In some high-cost urban areas in 2026, a private room in a nursing home may exceed this amount. Always align the monthly acceleration percentage with the projected costs in your geographic area.
- Ignoring the Impact on Beneficiaries: Because this is a hybrid policy, every dollar you spend on your care is a dollar that will not go to your heirs. It is vital to have a family discussion about this trade-off.
- Relying on "Cash Value" for Premiums: In Universal Life policies, owners sometimes stop paying out-of-pocket premiums, assuming the cash value will carry the policy. If the LTC rider charges are high, this can deplete the cash value quickly, causing the policy—and the LTC coverage—to lapse just when it is needed most.
FAQ
Can I add an LTC rider to an existing Pekin Life policy?
In most cases, an LTC rider must be added at the time of the policy's original application. Adding it later usually requires "attained age" underwriting, which means you must pass a new medical exam, and the cost will be based on your current age. Some older policy forms may not support the addition of modern LTC riders at all.
Is the LTC benefit received tax-free?
Under current 2026 federal tax laws (Internal Revenue Code Section 101(g)), benefits received from a "qualified" long-term care rider on a life insurance policy are generally received tax-free, up to certain per-diem limits set by the IRS. However, it is always recommended to consult with a tax advisor regarding your specific situation.
What happens if I use up the entire death benefit on long-term care?
If the entire death benefit is accelerated to pay for care, the life insurance policy typically terminates. However, some Pekin policies may have a "residual death benefit" clause, which guarantees a small payout (e.g., $5,000 or $10,000) to beneficiaries for funeral expenses, even if the primary benefit was exhausted by LTC claims.
Does Pekin cover care provided by family members?
Standard Pekin LTC riders generally require care to be provided by licensed professionals or agencies. Informal care provided by a spouse or child living in the same household is typically not a reimbursable expense under the terms of these life insurance riders.
Can I cancel the LTC rider but keep the life insurance?
Yes, in most instances, you can request to drop the rider to reduce your premium costs while maintaining the base life insurance coverage. However, once dropped, you cannot usually re-add the rider without full medical underwriting.
Recommendation for Next Actions
If you are considering Pekin Insurance for long-term care protection in 2026, your first step should be to request a Life Insurance Illustration that specifically includes the Accelerated Death Benefit for Long-Term Care. Review the "Supplemental Illustration" pages, which show how the death benefit and cash value are impacted if you begin taking LTC payments at various ages (e.g., 75, 80, or 85).
Secondly, compare the hybrid approach with your overall retirement strategy. If your primary goal is to protect your assets for your children while having a "safety net" for healthcare, a Pekin Whole Life policy with an LTC rider is a robust solution. If you are more concerned with maximum LTC coverage and have no heirs to leave a death benefit to, you might investigate the few remaining standalone LTC options or a dedicated LTC annuity.
Image Gallery
Select an image to open it in a new tab.





Vivian Cho
Executive IT and Emerging Technologies Reporter
