A Comprehensive Guide to Compare Fees for Indexed Universal Life Insurance Policies
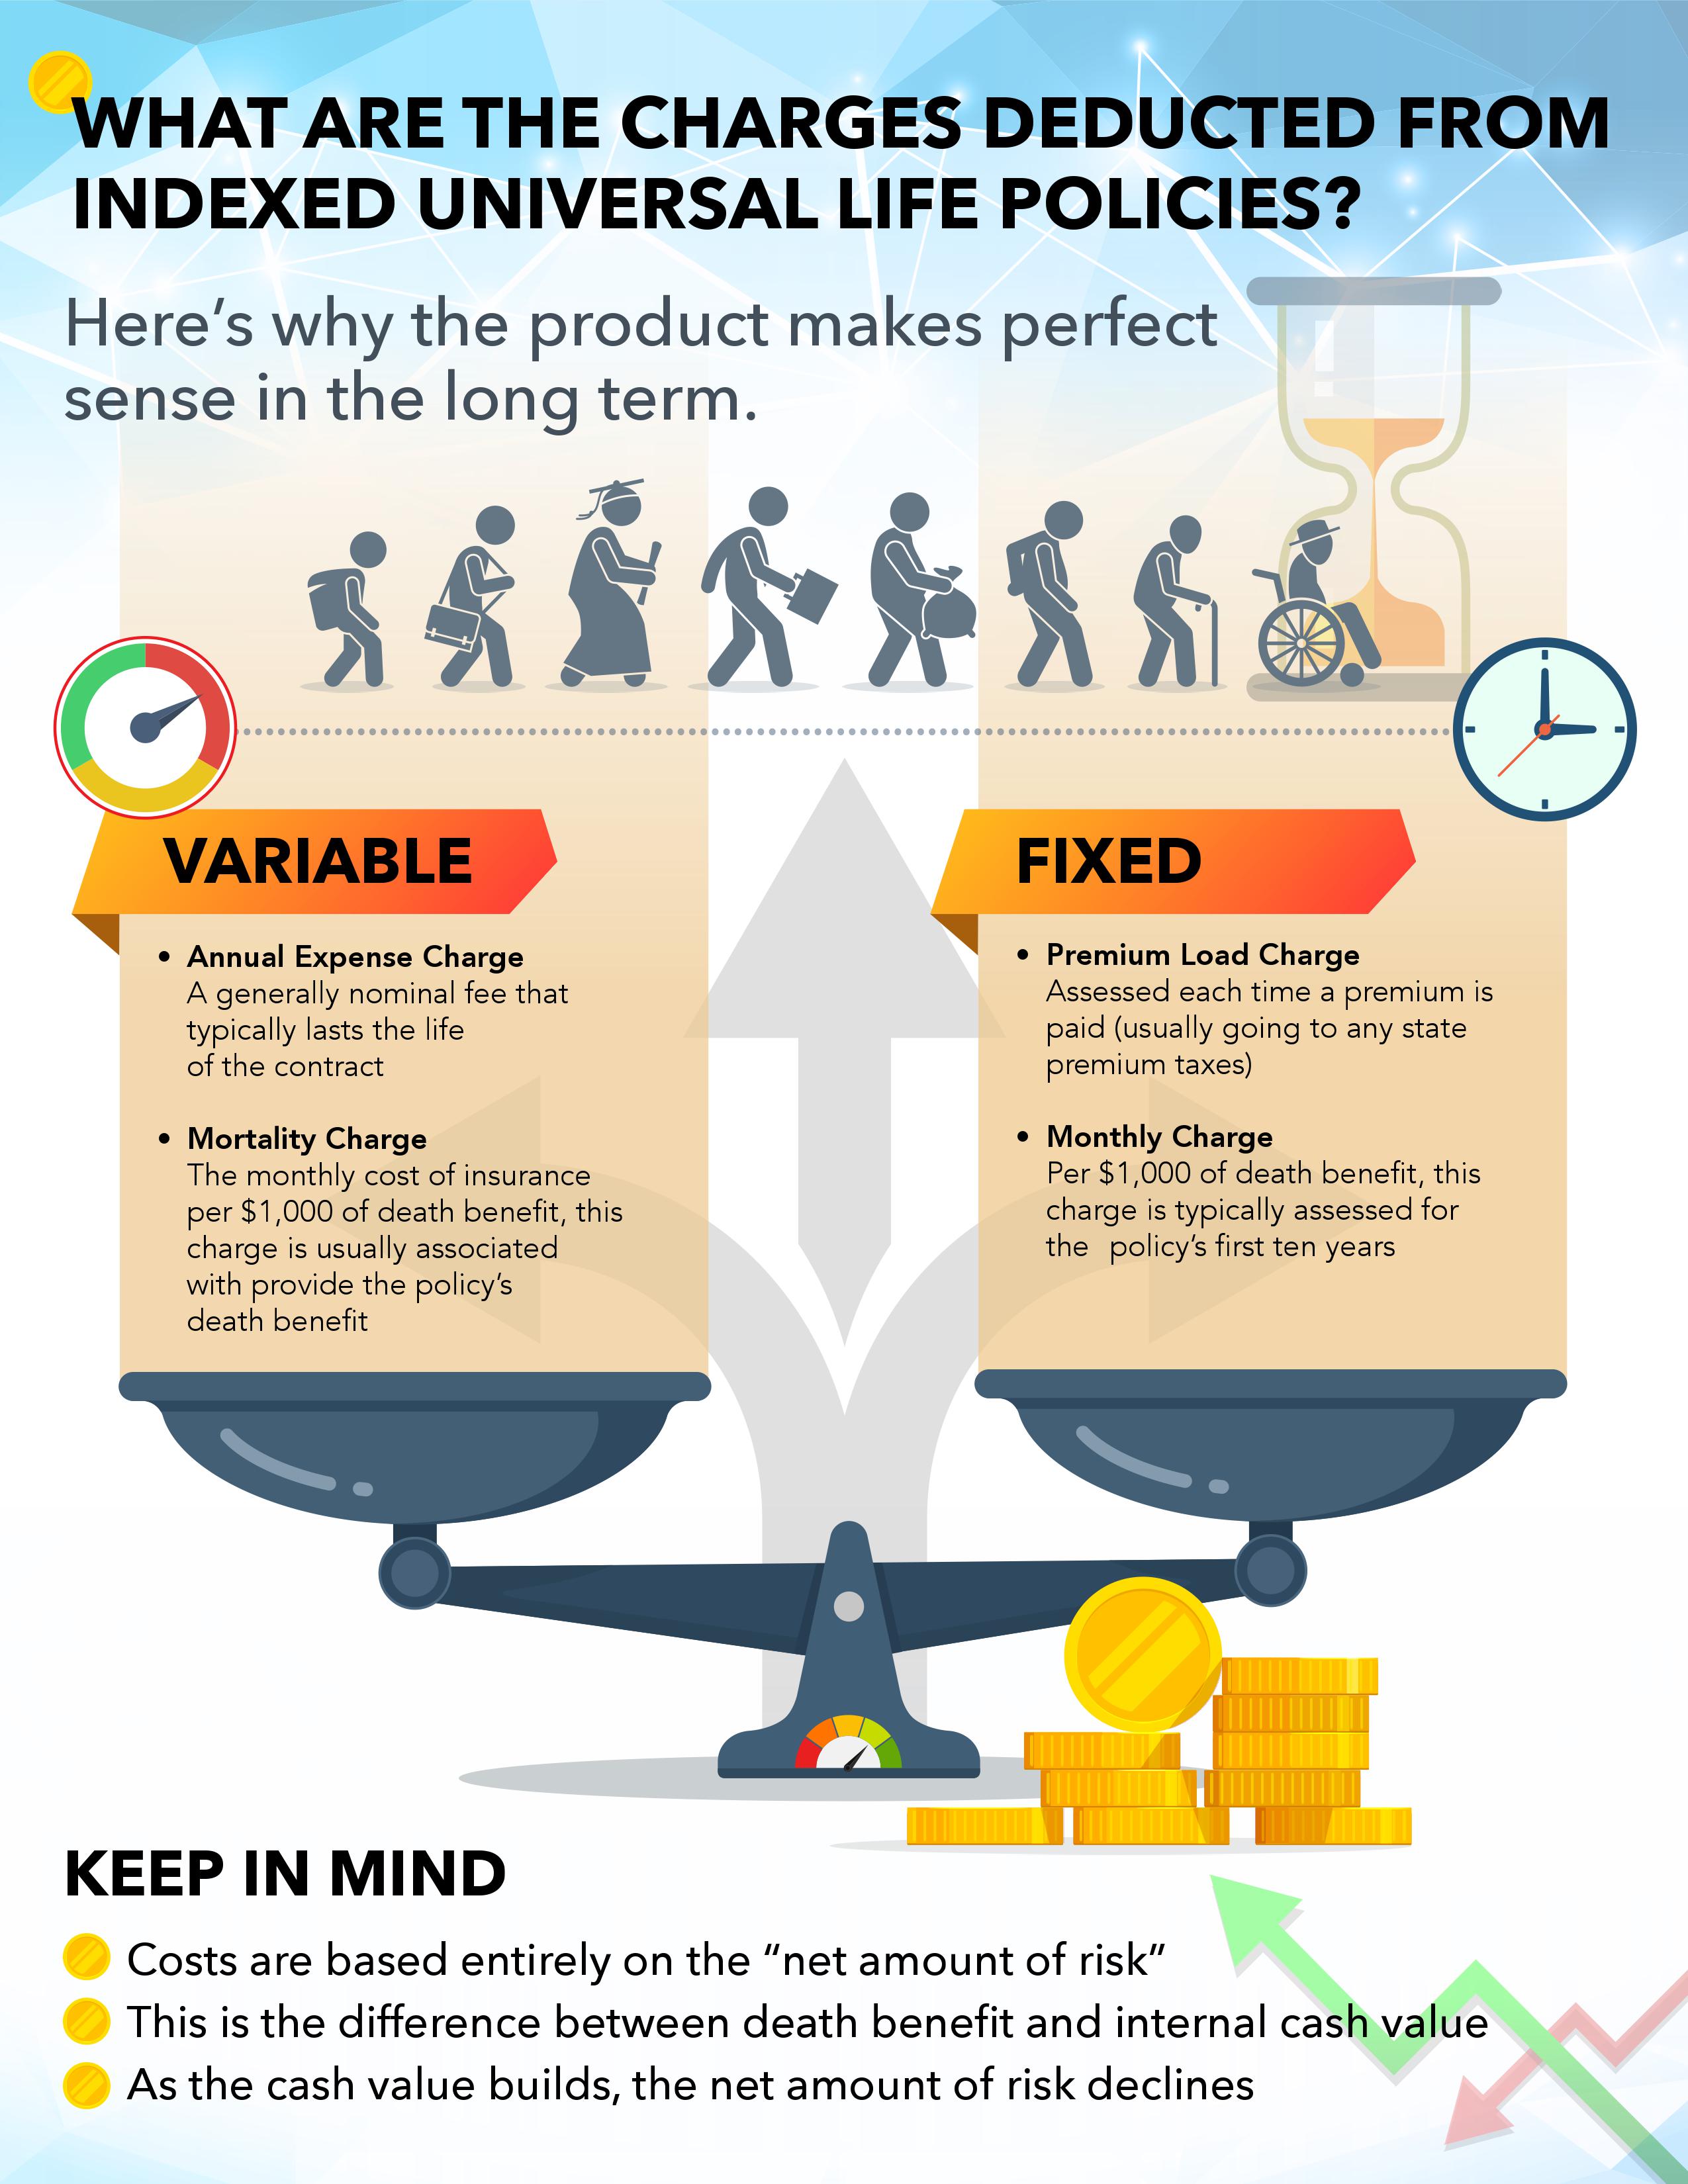
Evaluating indexed universal life insurance policies requires a granular examination of underlying costs, as structural fees directly erode cash value growth over decades. Policyholders encounter a complex matrix of premium loads, administrative charges, cost of insurance deductions, and equity index participation caps that dictate actual net performance.
Indexed Universal Life (IUL) insurance is a permanent life insurance product that provides a death benefit alongside a cash value component. The cash value can grow based on the performance of an external equity index, such as the S&P 500, without directly participating in the stock market. Because these policies blend insurance protection with equity-linked growth, understanding the associated fee structures is essential for policyholders seeking long-term accumulation and wealth transfer capabilities.
Unlike term life insurance, which carries straightforward premium pricing, or traditional whole life policies with fixed guarantees and bundled dividends, IUL policies feature unbundled fee architectures. This unbundling means every administrative expense, cost of insurance deduction, and rider fee is itemized on annual statements. Consequently, comparing fees across different IUL carriers requires careful analysis of guaranteed maximum rates versus current-scale charges, surrender schedules, and participation multipliers.
Deconstructing the Cost Structure of Indexed Universal Life Insurance
To effectively evaluate and compare IUL policies, one must first master the specific terminology and mechanics of policy expenses. Insurance carriers deduct various charges from either the premium payments before allocation or directly from the accumulated cash value account on a monthly basis.
Premium Expense Charges and Sales Loads
When a policyholder pays a premium, the insurance company rarely credits the entire amount to the cash value account. Instead, carriers deduct a premium expense charge—often referred to as a premium load or sales load. This fee covers the initial acquisition costs, agent commissions, and state premium taxes.
- Front-End Loads: These are percentage-based deductions taken immediately from each premium payment. For instance, a 6% front-end load means a $10,000 annual premium results in $600 going toward fees and $9,400 entering the allocation pool.
- Duration Variations: Some carriers decrease front-end loads over time, while others maintain a flat percentage for the life of the contract. Certain designs utilize back-end charges instead, shifting the recovery period to the surrender charge phase.
Monthly Administrative and Policy Fees
Regardless of market performance or premium payment fluctuations, insurers levy monthly flat-rate administrative charges to maintain the account ledger, issue annual statements, and manage regulatory compliance. These fees are typically deducted directly from the cash value or the unindexed fixed account. While flat fees (such as $5 to $15 per month) may appear negligible during the early policy years, their relative impact depends heavily on the size of the accumulated cash balance.
Cost of Insurance (COI) Charges
The Cost of Insurance represents the net amount-at-risk charge levied by the carrier to provide the actual death benefit. The COI is calculated monthly based on the insured's current age, gender, tobacco use, health classification, and the net amount at risk (the difference between the total death benefit and the accumulated cash value).
- Increasing Mortality Risk: As the insured ages, the COI rates increase exponentially. In poorly performing market scenarios, rising COI charges can outpace cash value growth, potentially causing policy lapse unless the owner increases premium contributions.
- Guaranteed vs. Current COI: Insurers publish a "current" COI table, which reflects their ongoing expectations of mortality and profitability, and a "guaranteed maximum" COI table, representing the legal limit they can charge under the contract. Comparing current COI scales to guaranteed maximums provides insight into the carrier's safety margin.
Examining Asset-Based Management Fees and Indexing Costs
Beyond fixed administrative and mortality charges, IUL policies feature costs tied directly to the management of the equity-linked indexing accounts. These mechanisms dictate how cash value growth is calculated and what portion of market returns is retained by the insurer.
Participation Rates, Caps, and Spreads
Unlike traditional variable universal life (VUL) policies that charge explicit asset-management fees (e.g., 0.75% to 1.5% annually for underlying mutual fund sub-accounts), IUL policies typically do not charge a direct management fee on indexed accounts. Instead, the insurance company covers its hedging costs and generates profit through structural limits:
- Participation Rates: This determines the percentage of the index's positive return credited to the policy. If the index gains 10% and the participation rate is 80%, the credited rate is 8%.
- Caps: The maximum interest rate the carrier will credit to the policy, regardless of how high the index climbs. If the S&P 500 returns 15% but the cap is 8%, the policy credits 8% (subject to floors).
- Spreads or Asset Fees: An explicit percentage subtracted from the index return. If the index gains 10% and the spread is 3%, the credited rate is 7%.
Fixed Account Margins and Loan Arbitrage Fees
Most IUL contracts include a fixed interest account option alongside indexed segments. When policyholders allocate funds to the fixed account, the insurer credits a guaranteed minimum interest rate while retaining a margin between its general portfolio yield and the credited rate. Additionally, policy loans incur interest charges; while some policies offer "participating loans" where the borrowed cash value continues to earn index interest, the net spread between the loan interest charged by the carrier and the interest credited to the loaned amount constitutes a significant internal cost.

Comparing IUL Fee Schedules Across Carriers
Comparing fee structures among different life insurance companies requires reviewing product illustrations and policy contracts. Because illustrated rates depend on hypothetical assumptions, focusing on guaranteed structural costs provides a more reliable baseline for financial planning.
| Fee Category | Typical Range / Structure | Impact on Cash Value |
|---|---|---|
| Front-End Premium Load | 3% to 9% of gross premium | Reduces immediate capital entering the growth pool. |
| Monthly Administration Fee | $5 to $20 per month (flat rate) | Steady drag, disproportionately impacts smaller policies. |
| Cost of Insurance (COI) | Variable; rises annually with age | Major long-term expense; accelerates depletion risk in later years. |
| Surrender Charges | 10% to 100% scaling down over 10 to 15 years | Severe penalty for early policy termination or withdrawal. |
| Rider Fees | Variable percentage or flat monthly cost | Adds optional benefits (e.g., chronic illness, waiver of premium) at an extra cost. |
Evaluating Surrender Charges and Vesting Periods
Surrender charges represent a primary liquidity barrier in IUL contracts. When an owner cancels the policy or surrenders a portion of the cash value beyond the penalty-free withdrawal limit (typically 10% annually), the insurer assesses a surrender charge.
- Duration: Surrender periods commonly span 10 to 15 years, starting at a high percentage of the first-year premium or account value and declining linearly to zero.
- Impact on Comparisons: Two policies with identical caps and participation rates may feature vastly different surrender schedules. A longer surrender period locks the policyholder into the contract's specific COI and administrative fee structure without the freedom to exchange or restructure the asset without financial penalty.
Hidden Costs of Policy Riders
Indexed universal life insurance policies offer numerous riders, such as accelerated death benefit riders for critical or chronic illness, guaranteed insurability riders, and premium waiver riders. While these add functional value, each rider introduces an internal deduction. When comparing policies, analyze whether rider charges are front-loaded, asset-based, or deducted as a flat monthly rate from the cash value.
Analyzing Long-Term Risks Associated with IUL Fee Structures
The architecture of IUL fees creates specific vulnerabilities that policyholders must navigate, particularly as they age or if market performance remains subdued over extended periods.
The "Lapse Trap" and Rising COI Dynamics
The most critical structural risk in an IUL policy is the interplay between rising COI charges and low index returns. If a sequence of flat or negative market years occurs (mitigated only by the 0% floor), the cash value fails to grow while the cost of insurance increases due to the insured's advancing age.
If the cash value drops below the level required to cover the upcoming monthly deductions, the policy enters a grace period. To prevent a policy lapse—which triggers immediate cancellation and potential tax liabilities on past gains—the policyholder must inject substantial premium payments outside the original funding schedule.
Over-leveraging and Policy Loans
Policy loans are often marketed as tax-free retirement income streams. However, taking loans reduces the active cash value generating index credits. If the loan balance grows faster than the remaining credited cash value due to high loan interest rates and stagnant market performance, the policy can collapse, leaving the owner with a large taxable event on forgiven debt.
Practical Steps to Compare and Select an IUL Policy
Evaluating competing IUL offers requires a systematic review methodology that looks beyond optimistic sales illustrations.
- Examine the Guaranteed Maximum Illustration: Request an illustration run at the guaranteed maximum COI and minimum interest crediting rate (e.g., 0%). This stress-test reveals how long the policy survives under worst-case economic and cost conditions.
- Scrutinize the Multiplier and Volatility Control Fees: Many modern IUL policies feature "volatility-controlled indices" or "participation multipliers." These enhancements often come with explicit asset fees or lower caps. Calculate the net return after subtracting all underlying index management fees.
- Review the Carrier's Historical Dividend and Cap Performance: While past performance does not guarantee future results, examine how consistently a carrier has adjusted its caps and participation rates over the past decade relative to broader economic benchmarks.
- Consult Independent Actuarial Analysis: Work with an independent financial advisor or life insurance specialist who is not captive to a single carrier to review the unbundled expense pages found in the back of the policy contract.
Frequently Asked Questions
What are the standard fees charged in an indexed universal life insurance policy?
Standard fees include premium expense loads (sales charges), monthly flat administrative fees, variable cost of insurance (COI) deductions based on age and mortality risk, surrender charges for early termination, and optional rider fees. Unlike variable universal life policies, IULs typically avoid explicit asset-management percentage fees on indexed accounts, relying instead on caps, participation rates, and spreads.
How do surrender charges affect an IUL fee comparison?
Surrender charges penalize policyholders who cancel or substantially withdraw from the contract within the first 10 to 15 years. When comparing policies, a shorter surrender period or lower penalty schedule offers greater liquidity and flexibility, reducing the risk of being locked into unfavorable long-term administrative or mortality costs.
Do IUL policies have hidden management fees?
While IUL policies do not feature mutual fund management fees, they incorporate indirect costs through caps, participation rates, and fixed account spreads. These structural limits determine how much of the underlying market gain is retained by the insurance company to cover hedging and operational expenses.
Why do Cost of Insurance (COI) charges increase over time?
COI charges rise because the probability of mortality increases as the insured ages. In an IUL policy, the monthly deduction is calculated using the net amount at risk multiplied by the current COI rate for the insured's exact age bracket, leading to higher absolute deductions in later policy years.
Can IUL fees cause a policy to lapse?
Yes. If poor market performance results in low cash value accumulation while COI and administrative fees continue to rise with age, the cash value may be entirely depleted. If the policy value drops to zero and no additional premium is paid during the grace period, the policy lapses, potentially triggering unexpected tax consequences.
How can I verify the actual fees of a specific IUL contract?
Policy fees are explicitly detailed in the policy contract and the product illustration ledger. Reviewing the "Guaranteed Policy Values" section and the narrative fee disclosure pages provides the exact maximum legal charges permitted underwritten by the carrier.
Conclusion and Next Actions
Comparing fees for indexed universal life insurance policies demands moving beyond projected growth columns to analyze guaranteed structural expenses. Prioritize policies with transparent, competitive COI tables, reasonable surrender schedules, and stable participation caps. To proceed, request a comprehensive illustration from at least three distinct carriers, specifically asking for a sensitivity test run at guaranteed maximum costs and zero index growth to verify long-term viability before committing capital.
Image Gallery
Select an image to open it in a new tab.
Akira Tanaka
International Academic Trends Correspondent
