When exploring specialized life insurance offerings, navigating unique identifiers, acronyms, or specific corporate entities requires careful research to ensure you secure the right financial protection for your beneficiaries. While "WLMN" is not a universally standardized industry acronym like "WL" (whole life) or "UL" (universal life), evaluating any specialized insurance product or company brand demands a rigorous review of policy types, financial stability, underwriting criteria, and your long-term personal financial goals.
Understanding how specialized life insurance works involves looking past marketing terminology to examine cash value accumulation, premium structures, death benefit guarantees, and the underlying contractual obligations of the issuing carrier. Whether you are investigating a specific financial institution, a white-labeled insurance product, or a unique corporate nomenclature, knowing the fundamental mechanics of life insurance will help you make an informed decision.
Decoding Insurance Terminology: Contextualizing Specialized Policies
The life insurance market features an array of product classifications, abbreviations, and proprietary names. Before committing to any policy, it is vital to distinguish between generic industry terms and specific product identifiers.
In standard insurance nomenclature, acronyms typically denote foundational policy categories. For example:
- Term Life Insurance: Provides coverage for a specified period (e.g., 10, 20, or 30 years) with no cash value component.
- Whole Life (WL): A form of permanent life insurance featuring level premiums, a guaranteed death benefit, and a cash value account that grows at a fixed rate.
- Universal Life (UL): A flexible permanent policy allowing the policyholder to adjust their premium payments and death benefits within certain limits, tied to an interest-bearing cash value account.
When encountering less common identifiers or corporate acronyms like WLMN, policyholders must verify whether the term refers to a distinct permanent whole life product variant, a specific broker-dealer network, or a localized financial services firm. Clarifying this identity directly with a licensed insurance producer or reviewing the official policy prospectus prevents costly misunderstandings regarding policy performance and guarantees.
Core Categories of Life Insurance Products
To understand how any specific policy fits into your financial strategy, you must evaluate the broader category to which it belongs. Life insurance fundamentally splits into two major domains: temporary and permanent protection.
| Policy Type | Primary Purpose | Cash Value Component | Premium Structure | Best Suited For |
|---|---|---|---|---|
| Term Life | Income replacement during working years | None | Fixed for the term (e.g., 10–30 years), increases upon renewal | Young families, mortgage protection, budget-conscious buyers |
| Whole Life | Lifelong protection and estate planning | Guaranteed growth with potential dividends | Fixed and level for life; higher initial cost | Final expenses, lifelong dependents, conservative wealth transfer |
| Universal Life | Flexible permanent coverage | Variable growth tied to market indices or crediting rates | Flexible; can fluctuate based on cash value performance | High earners seeking flexibility and cash accumulation |
| Variable Life | Investment-driven permanent coverage | Tied directly to sub-accounts (stocks/bonds) | Fixed or flexible; risk of policy lapse if investments underperform | Sophisticated investors comfortable with market volatility |
Evaluating these options requires aligning your current life stage, income replacement needs, and long-term estate planning objectives with the appropriate product mechanics.
Key Factors to Evaluate Before Purchasing a Policy
Securing life insurance is a binding financial commitment that requires careful due diligence. Whether evaluating a major national carrier or a specialized financial product, several critical criteria dictate the true value and reliability of the coverage.
Financial Strength and Stability
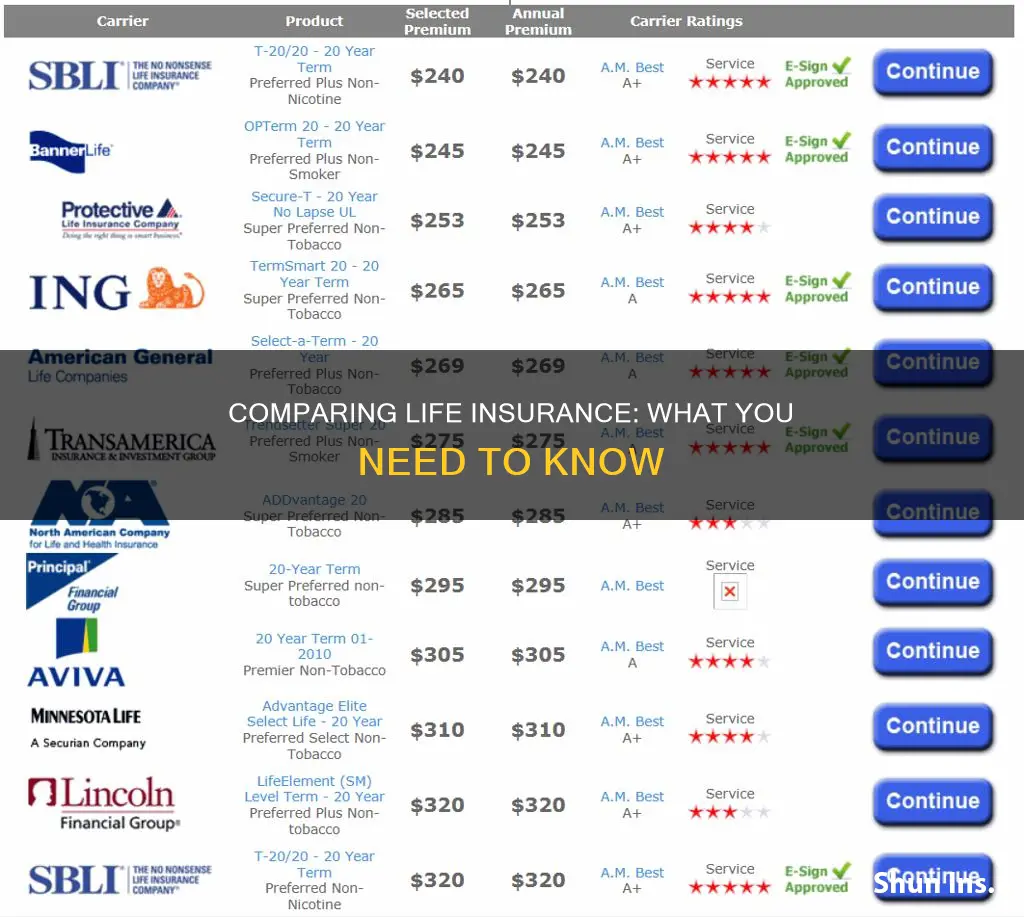
The most crucial element of any life insurance policy is the long-term solvency of the issuing insurance company. Because permanent policies can span decades, the carrier must possess the financial reserves required to pay future death benefits. Independent rating agencies—such as A.M. Best, Moody's, Standard & Poor's, and Fitch—evaluate insurer financial strength. Reviewing these ratings ensures the company maintains strong capitalization and a proven track record of claims-paying ability.
Underwriting and Eligibility Requirements
Every applicant must pass through the underwriting process, where insurance companies assess mortality risk based on age, health history, occupation, lifestyle habits, and family medical background.
- Medical Exams: Many permanent policies require a paramedical examination, including blood and urine draws.
- Simplified Issue: Some products offer accelerated underwriting without a physical exam, though these often feature lower maximum coverage limits and higher premium rates.
- Morbidity and Mortality Tables: Actuarial science dictates your premium costs based on statistical life expectancies. Applying earlier in life locks in significantly lower base rates.
Premium Affordability Versus Cash Value Growth
For permanent policies, striking a balance between premium affordability and cash value accumulation is essential. If a policy is over-leveraged with high premium payments that strain your monthly budget, the risk of policy lapse increases. Conversely, underfunding a permanent policy can diminish its cash value growth, neutralizing the tax-advantaged benefits intended for retirement supplementation or emergency liquidity.
Evaluating Policy Costs and Hidden Fees
Life insurance pricing is rarely a flat rate. Understanding the underlying cost structure ensures transparency and prevents unexpected financial strain down the road.
Premium Loading and Administrative Expenses
Insurance companies deduct various fees from your premium payments before allocating funds to cash value accounts. These include premium taxes, administrative fees, and sales loads. In the early years of a permanent policy, a substantial portion of your payment goes toward these expenses rather than building cash value.
Cost of Insurance (COI) Charges
For flexible permanent policies, the insurer deducts a monthly Cost of Insurance charge from the cash value to cover the pure risk of the death benefit. As you age, the COI increases. If your cash value underperforms, higher COI charges can deplete the account, forcing you to pay higher out-of-pocket premiums to keep the policy active.
Common Pitfalls to Avoid
Navigating the life insurance market can be complex, and certain missteps can jeopardize your financial security or leave your family underinsured.
- Underestimating Coverage Needs: Relying solely on a basic employer-provided group life policy (often capped at one or two times your salary) leaves most families critically underinsured. Personal coverage should account for total debt, future education costs, and long-term income replacement.
- Ignoring Policy Riders: Standard death benefits can often be enhanced with riders—such as accelerated death benefits for terminal illness, waiver of premium disability riders, or child riders. Overlooking these options can limit your policy's utility during a crisis.
- Failing to Disclose Medical History: Omission of pre-existing conditions or tobacco use on an application constitutes material misrepresentation. This can give the insurer grounds to deny a claim or rescind the policy entirely during the contestability period (typically the first two years of the contract).
Frequently Asked Questions
What should I do if I cannot verify a specific insurance brand or acronym?
Contact your state’s Department of Insurance or Office of the Insurance Commissioner. Regulators maintain licensing databases and active registries for all authorized insurance companies, products, and licensed producers operating within your jurisdiction.
How much life insurance coverage do I actually need?
A standard benchmark is multiplying your annual gross income by 10 to 15, then adding specific financial obligations such as outstanding mortgage balances, college funding goals, and final expenses. A personalized needs analysis provides a precise figure.
Can I convert a temporary term policy into a permanent policy?
Many term life insurance policies feature a conversion rider allowing you to transition into a permanent whole or universal life policy without undergoing a new medical examination. Review your specific policy contract for conversion windows and deadlines.
What happens if I miss a premium payment?
Most life insurance policies include a grace period (typically 31 days) during which late payments can be made without lapsing coverage. For permanent policies with accumulated cash value, automatic premium loans may be triggered if the cash value is sufficient to cover the missed payment.
Are life insurance death benefits taxable?
Generally, life insurance death benefits paid to named beneficiaries are income tax-free under Internal Revenue Code Section 101(a). However, proceeds may be subject to federal estate taxes if the insured retains ownership of the policy or if the estate is named as the beneficiary. Consult a qualified tax professional regarding estate planning implications.
Next Actions and Professional Guidance
Before entering into any life insurance contract, request a complete policy illustration detailing projected cash values, guaranteed minimums, and fee disclosures. Because life insurance laws, tax implications, and financial needs vary significantly depending on individual circumstances, consider consulting an independent financial advisor or a licensed insurance fiduciary who can compare multiple carriers and objectively match a policy to your long-term financial objectives.
Image Gallery
Select an image to open it in a new tab.
Lars Thomsen
Global Labor Markets and Economic Strategy Editor
