Smoker vs Non-Smoker Term Life Insurance: Analyzing the Premium Percentage Increase
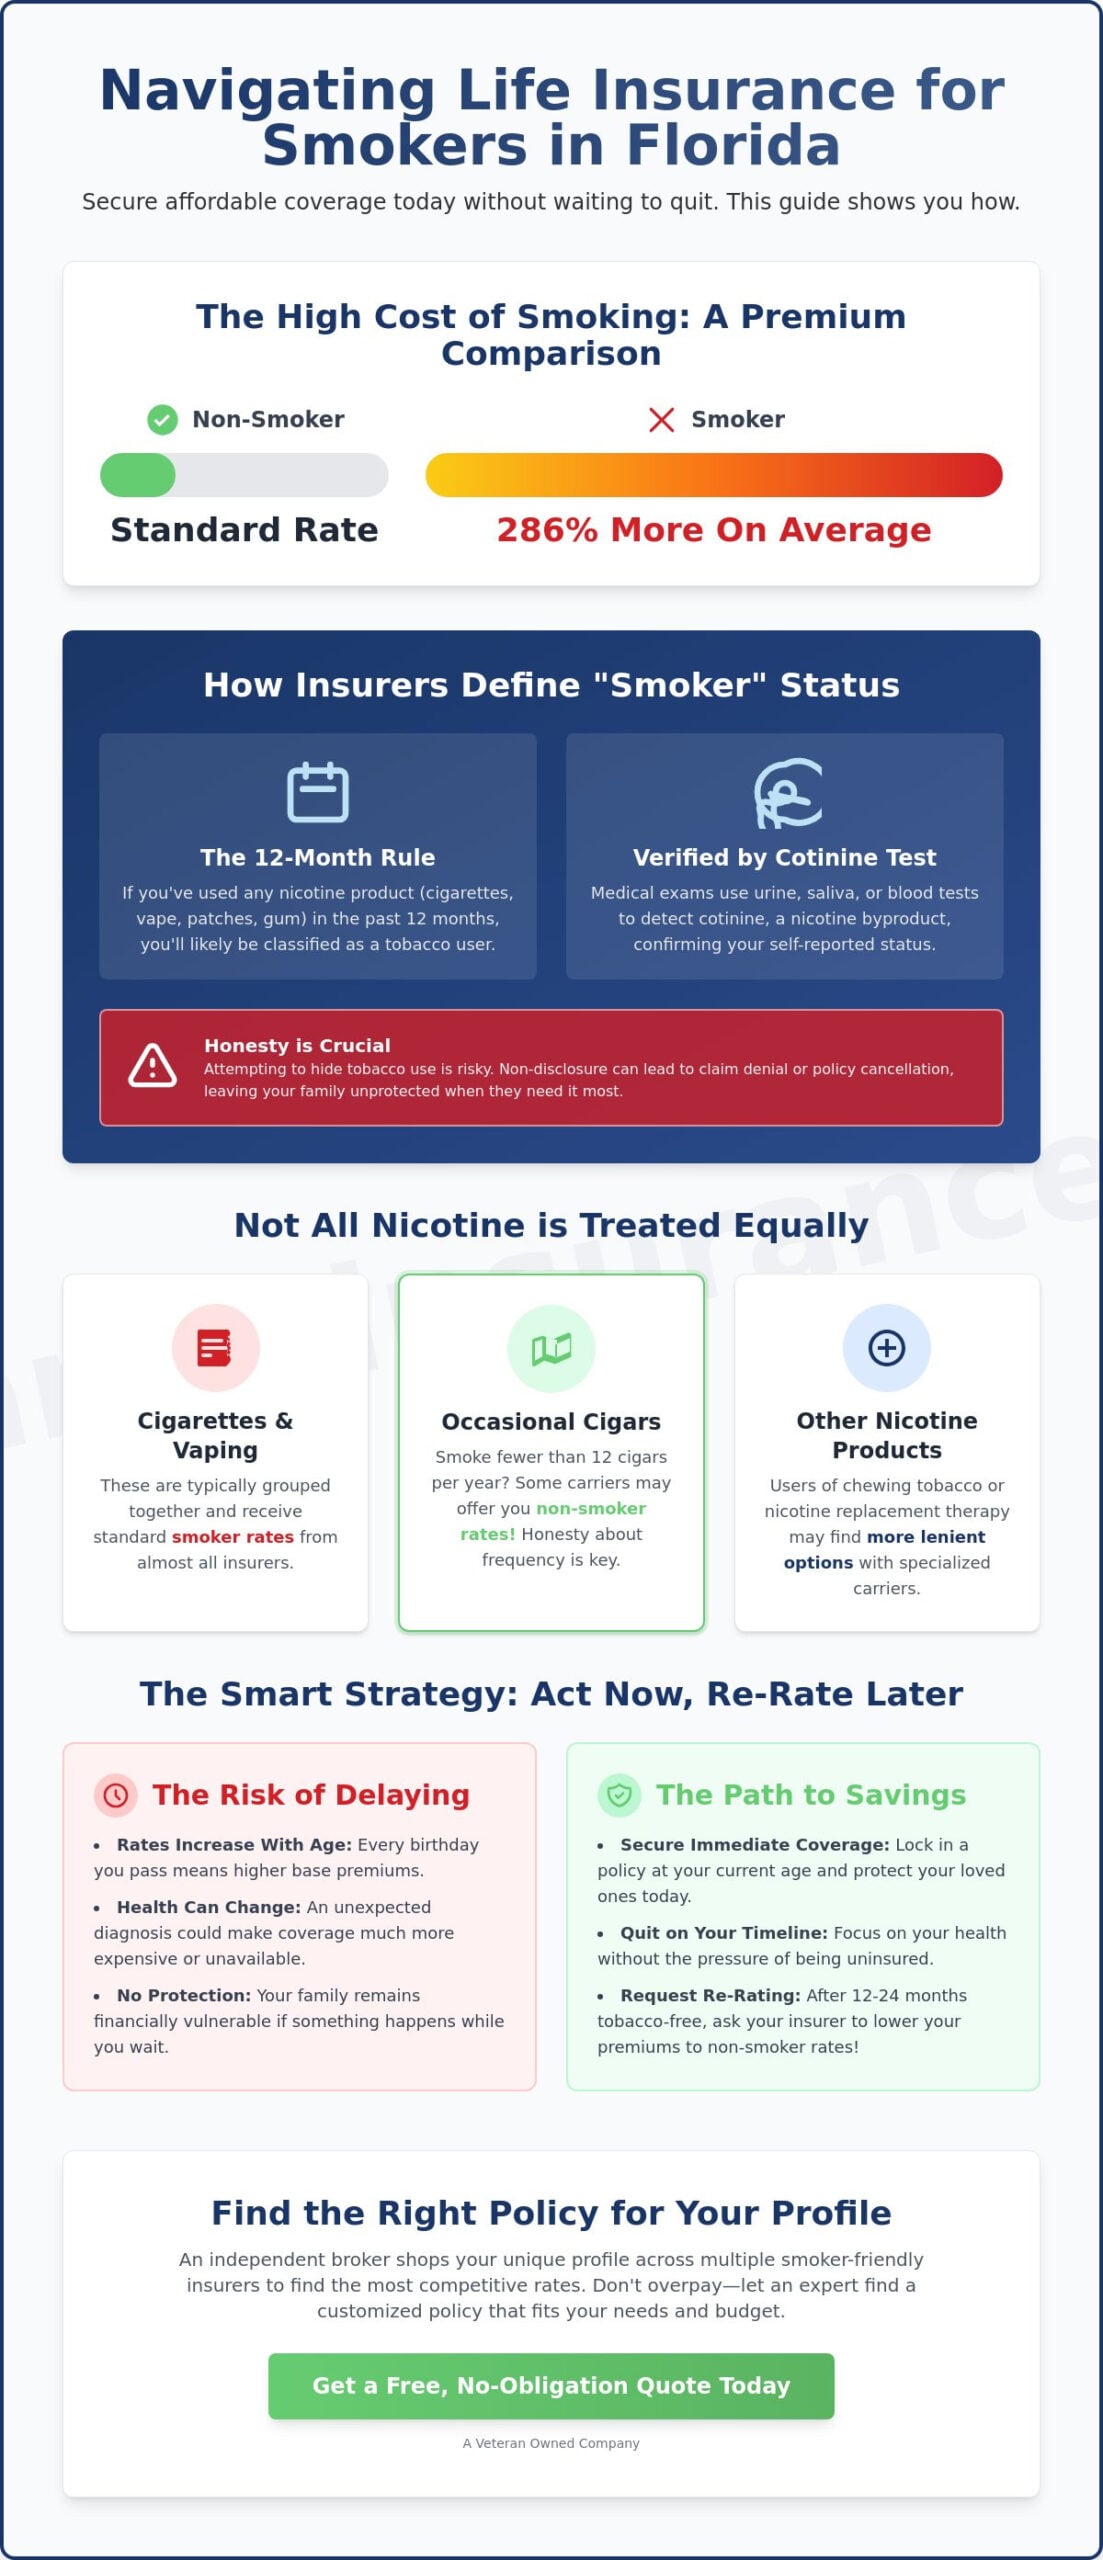
In 2026, smokers typically pay between 100% and 300% more for term life insurance premiums compared to non-smokers of the same age and health profile. This substantial percentage increase, often referred to as a "smoker's load," reflects the higher actuarial risk and shorter life expectancy associated with regular nicotine and tobacco consumption.
Why Insurance Companies Charge Smokers a Premium Surplus
The fundamental principle of life insurance is the assessment of risk. Actuaries—the professionals who calculate insurance risks and premiums—rely on vast datasets to determine the likelihood of a policyholder passing away during the term of their coverage. For decades, medical data has consistently shown that tobacco use is a primary driver of premature mortality.
From an insurer's perspective, a smoker represents a significantly higher probability of a claim payout. According to data maintained by major carriers and health organizations, smoking is linked to a myriad of chronic conditions, including lung cancer, chronic obstructive pulmonary disease (COPD), and cardiovascular diseases. Because the insurance company is taking on more "risk" by insuring a smoker, they must collect more "premium" to balance the potential for a payout.
In 2026, the gap between smoker and non-smoker rates has remained wide. While medical technology has improved outcomes for many diseases, the statistical correlation between smoking and shortened lifespans remains a cornerstone of underwriting. Consequently, smokers are rarely eligible for the "Preferred Plus" or "Super Preferred" rating classes, which offer the lowest possible rates in the market. Instead, they are relegated to "Smoker" tiers, which start at a baseline much higher than the "Standard Non-Smoker" rate.
Defining a "Smoker" in 2026 Underwriting
The definition of a smoker for life insurance purposes is broader than many applicants realize. It is not limited to those who smoke a pack of cigarettes a day. In the current 2026 insurance landscape, several different habits can trigger a smoker classification:
- Cigarettes: This is the most common trigger. Even "occasional" or "social" smoking is usually classified as full smoker status.
- Vaping and E-Cigarettes: Despite early marketing suggestions that vaping was a "safer" alternative, most life insurance carriers treat e-cigarette use and vaping as equivalent to cigarette smoking. This is primarily due to the nicotine content and the lack of long-term data on the respiratory effects of vaporized chemicals.
- Cigars and Pipes: Some carriers offer "occasional cigar" exceptions (e.g., one cigar per month with a clean urine test), but frequent use will result in smoker rates.
- Nicotine Replacement Therapy (NRT): Using nicotine patches, gum, or lozenges often results in a smoker rating. Insurers view the presence of nicotine in the system as the primary risk factor, regardless of the delivery method.
- Cannabis/Marijuana: The classification of marijuana use varies by carrier. Some insurers have moved toward a non-smoker classification for occasional users, while others still group any inhaled substance into the smoker category.

The Percentage Gap: Breaking Down the Costs
When comparing premiums, the percentage increase for smokers is rarely a flat rate. It scales with age and the length of the term. A 25-year-old smoker may see a 100% increase, while a 50-year-old smoker could see their premiums quadruple (a 300% increase) compared to a non-smoking peer.
The reason for this scaling is "compounded risk." As an individual ages, the cumulative damage of smoking on the cardiovascular and respiratory systems becomes more likely to manifest as a terminal illness. Therefore, the older the applicant, the more punitive the smoker's premium becomes.
Comparison Table: Estimated Monthly Premiums for $500,000 (20-Year Term)
The following table illustrates the typical premium differences observed in the 2026 market for individuals in otherwise good health. Note: These are estimates for educational purposes; actual quotes depend on individual medical history and specific carrier guidelines.
| Age | Non-Smoker (Standard) | Smoker (Standard) | Percentage Increase |
|---|---|---|---|
| 25 | $22.00 | $51.00 | ~132% |
| 35 | $31.00 | $88.00 | ~184% |
| 45 | $62.00 | $215.00 | ~246% |
| 55 | $145.00 | $560.00 | ~286% |
As the data shows, the financial burden of smoking increases exponentially with age. A 55-year-old smoker is not just paying a bit more; they are paying nearly four times what their non-smoking counterpart pays for the exact same death benefit.
The Underwriting Process and Verification
Insurers do not simply take an applicant's word regarding their smoking habits. The underwriting process involves several layers of verification to ensure the policy is priced correctly.
The Paramedical Exam
Most term life insurance policies require a medical exam. During this exam, a technician collects blood and urine samples. These samples are tested for cotinine, a metabolite of nicotine. Cotinine is the "gold standard" for tobacco detection because it stays in the body much longer than nicotine itself—typically up to several days or even weeks depending on the level of usage.
Medical Record Review
Insurers often request an Attending Physician Statement (APS). If your doctor's notes mention tobacco use, even if you claim to be a non-smoker on the application, the insurer will likely default to the smoker rate.
Prescription History
Underwriters also review prescription databases. If you have been prescribed smoking cessation medications, such as Chantix or Zyban, within the last year or two, this will alert the insurer to your history of tobacco use.
The Financial Impact Over Time
To truly understand the "cost" of being a smoker in the eyes of an insurance company, one must look at the total outlay over the life of the policy.
Consider a 35-year-old male purchasing a 20-year term policy for $500,000.
- Non-Smoker: $31/month x 240 months = $7,440 total
- Smoker: $88/month x 240 months = $21,120 total
The "smoker's tax" on this policy is $13,680. If that $57 monthly difference were instead invested in a retirement account with a 7% average annual return, it could grow to over $30,000 over those 20 years. This demonstrates that the cost of smoking in life insurance isn't just the higher bill—it's the opportunity cost of the capital lost to higher premiums.
Can You Lower Your Premiums After Quitting?
One of the most frequent questions from applicants is how soon they can qualify for non-smoker rates after they stop using nicotine. In 2026, most major life insurance carriers require you to be 100% nicotine-free for at least 12 months to qualify for standard non-smoker rates.
However, reaching the most favorable "Preferred" or "Preferred Plus" tiers usually requires a longer period of abstinence—often three to five years.
If you already have a policy and have recently quit smoking, you have two main options:
- Request a Re-rating: Some carriers allow you to undergo a new medical exam after one or two years of being smoke-free. If you pass the cotinine test and your health is otherwise stable, they may lower your existing premium.
- Apply for a New Policy: Often, the most effective way to lower costs is to apply for a brand-new policy once you hit the 12-to-24-month smoke-free milestone. This allows you to shop the entire market for the carrier that is currently most "quit-friendly."
The Risks of Material Misrepresentation
It can be tempting for a smoker to hide their habit on an insurance application to save thousands of dollars. However, this is considered material misrepresentation, a form of insurance fraud that carries severe consequences.
Life insurance policies typically include a two-year contestability period. If the policyholder dies within the first two years of the policy, the insurer has the right to investigate the original application for accuracy. If they discover the deceased was a smoker but claimed to be a non-smoker, they can legally deny the entire death benefit claim.
Even if the death occurs after the two-year contestability period, some jurisdictions allow insurers to adjust the death benefit. In this scenario, the company might calculate how much coverage the premiums paid would have bought at the smoker rate and only pay out that reduced amount to the beneficiaries.
Specialized Insurance for Smokers
For those who smoke and have other health complications, traditional term life insurance might be difficult to obtain or prohibitively expensive. In 2026, there are alternative products available:
- Simplified Issue Life Insurance: These policies require a health questionnaire but no medical exam. While they still ask about smoking, the underwriting is less stringent regarding other health markers. However, premiums are generally higher than standard term life.
- Guaranteed Issue Life Insurance: These policies have no medical questions and no exams. They are almost always "smoker-friendly" by default, but they offer much lower death benefits (usually under $25,000) and are significantly more expensive per dollar of coverage. They are typically used for final expenses rather than income replacement.
FAQs
1. Does vaping count as smoking for term life insurance in 2026?
Yes. The vast majority of insurance carriers classify vaping and e-cigarette use as "smoker" status. This is because these products still deliver nicotine, which is the primary chemical underwriters track via cotinine testing. While a small handful of "vape-friendly" carriers may offer non-smoker rates for vapers who do not use traditional tobacco, these are exceptions rather than the rule.
2. How long after quitting smoking can I get non-smoker rates?
Most carriers require a minimum of 12 consecutive months without any nicotine or tobacco use to qualify for "Standard Non-Smoker" rates. To qualify for the best rates (Preferred or Preferred Plus), you generally need to be nicotine-free for 3 to 5 years.
3. Will my life insurance go up if I start smoking after I buy the policy?
Generally, no. If you were a non-smoker when you applied and were honest on your application, your rates are "locked in" for the duration of the term. You are not required to notify the insurance company if you take up smoking later. However, if you let the policy lapse and have to re-apply, you will be subject to new underwriting at smoker rates.
4. Can I get non-smoker rates if I only smoke cigars occasionally?
Possibly. Some insurance companies have a "celebratory cigar" policy. They may allow you to qualify for non-smoker rates if you smoke 12 or fewer cigars per year and your urine test is negative for cotinine at the time of the exam. You must disclose this habit upfront to find the specific carriers that offer this leniency.
5. Does the use of nicotine patches or gum result in a smoker's premium?
Yes, in most cases. Because nicotine replacement therapies (NRT) result in a positive cotinine test, underwriters usually classify the applicant as a smoker. The insurance company’s logic is that the individual is still addicted to nicotine and has a high statistical likelihood of returning to tobacco use.
Practical Recommendation
If you are a smoker looking for term life insurance in 2026, the most effective strategy is to work with an independent broker rather than applying directly to a single carrier. Independent brokers have access to the underwriting guidelines of dozens of companies and can identify which ones are currently offering the lowest "smoker's load" or are more lenient toward specific habits like vaping or occasional cigar use.
Furthermore, if you are planning to quit, do not wait until you have been smoke-free for a year to get coverage. It is often wiser to secure a policy at the smoker rate now to ensure your family is protected, and then apply for a re-rating or a new policy once you have reached your one-year "anniversary" of being nicotine-free. This approach provides immediate protection while creating a path toward lower costs in the future.
Image Gallery
Select an image to open it in a new tab.

Simon Caldwell
Enterprise Technology and Systems Editor
