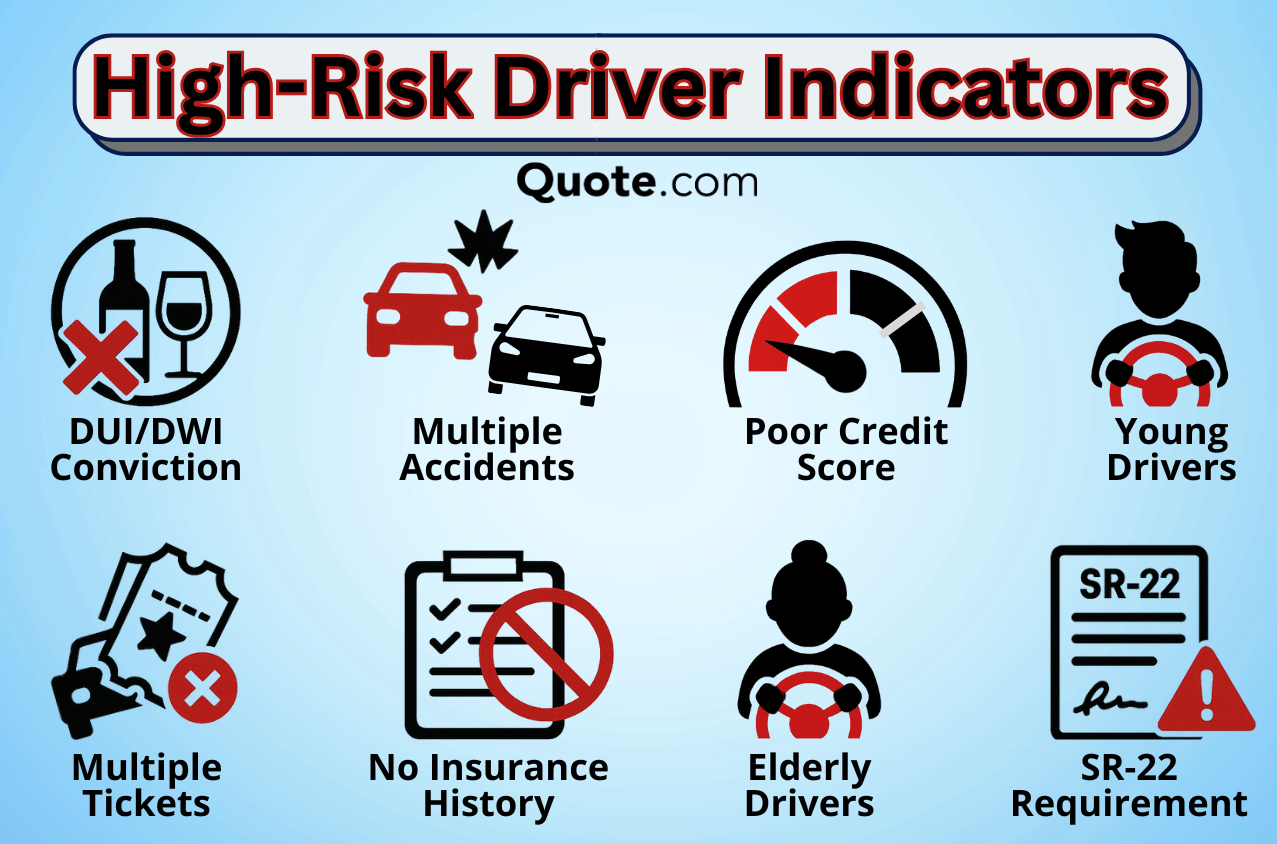
Finding the cheapest auto insurance in California for high-risk drivers in 2026 requires looking beyond standard carriers toward specialized providers and state-sponsored programs. For many, the California Low Cost Automobile Insurance Program (CLCA) offers the lowest absolute rates, while private insurers like Progressive, Mercury, and National General typically provide the most competitive premiums for those with DUIs or multiple accidents.
Understanding the High-Risk Designation in California
In the California insurance market of 2026, a "high-risk" designation is not a singular label but a spectrum of risk profiles that insurers use to determine premiums. Under the guidelines maintained by the California Department of Insurance (CDI), you are generally categorized as high-risk if you have a recent history of at-fault accidents, multiple moving violations, a DUI conviction, or if you are a newly licensed driver with no established history.
California is unique because of Proposition 103, a landmark law that dictates how insurance companies can set rates. Unlike most other states, California prohibits insurers from using your credit score to determine your premium. This is a significant advantage for drivers who might have poor credit but a relatively clean driving record. However, it also means that your actual driving behavior—accidents and tickets—carries significantly more weight in your final quote.
To be considered a "Good Driver" in California and qualify for a mandatory 20% discount, you must have been licensed for the previous three years and have no more than one "point" on your record. Once you exceed this threshold, you move into the high-risk category, where insurers are no longer required to offer that 20% discount and may apply significant surcharges.
Top Providers for High-Risk Drivers in 2026
While many national brands shy away from drivers with checkered records, several companies have optimized their underwriting models to serve this segment. In 2026, the following providers are consistently cited for offering the best balance of coverage and cost for high-risk individuals in the Golden State.
Progressive
Progressive has long been a leader in the high-risk market. Their use of advanced data analytics allows them to price risk more accurately than some legacy carriers. In 2026, Progressive remains a top choice for drivers needing an SR-22 filing, which is a certificate of financial responsibility often required by the DMV following a DUI or a license suspension. They tend to be more "forgiving" of a single major incident compared to carriers like State Farm or Farmers.
Mercury Insurance
As a California-based company, Mercury has a deep understanding of the local regulatory environment. They often offer competitive rates for drivers who have been priced out of the national "Big Four" carriers. Mercury’s strength lies in its tiered policy structures, which allow drivers to gradually move into lower-priced categories as their driving records improve over time.
National General
Now a part of the Allstate family, National General specializes specifically in non-standard auto insurance. They are often the go-to provider for drivers with "hard-to-place" risks, such as those with multiple DUIs or a history of lapsed coverage. While their base rates may be higher than a "Good Driver" policy at a standard firm, they are frequently the cheapest option for those at the far end of the risk spectrum.
GEICO
While GEICO is often associated with low rates for preferred drivers, they have a robust "Casualty" division that handles higher-risk policies. In 2026, GEICO continues to be competitive for younger high-risk drivers (ages 18–25) who have a single accident or speeding ticket on their record but otherwise show a commitment to safe driving habits.

The California Low Cost Automobile Insurance Program (CLCA)
For drivers who are struggling to find any affordable private insurance, the state-sponsored California Low Cost Automobile Insurance Program (CLCA) is a vital safety net. Established by the state legislature and managed by the California Automobile Assigned Risk Plan (CAARP), this program provides affordable liability insurance to low-to-moderate-income drivers who meet specific eligibility requirements.
To qualify for CLCA in 2026, you must:
- Have a valid California driver’s license.
- Own a vehicle valued at $25,000 or less.
- Be at least 16 years of age.
- Meet specific income eligibility requirements (calculated as a percentage of the Federal Poverty Level).
- Have a "good" driving record or be a "high-risk" driver who cannot find coverage elsewhere, provided you don't have a felony conviction for a driving-related offense.
The CLCA policy meets the state's minimum financial responsibility limits, which are lower than standard private limits but sufficient to keep you legal on the road. In 2026, annual premiums for this program often range from $250 to $600 depending on the county of residence, making it the absolute cheapest option for those who qualify.
Comparing High-Risk Premiums by Violation Type
The type of violation on your record significantly impacts which company will offer you the best rate. Insurance companies weight risks differently; some are more concerned with speed, while others are more concerned with sobriety or financial responsibility.
| Violation Type | Impact on Premium (Est.) | Recommended 2026 Provider | Key Consideration |
|---|---|---|---|
| DUI (First Offense) | 80% - 120% Increase | Progressive / Mercury | Requires SR-22 filing for 3 years. |
| At-Fault Accident | 30% - 60% Increase | GEICO / State Farm | "Good Driver" status lost for 3 years. |
| Multiple Speeding Tickets | 20% - 50% Increase | National General | Points accumulate; watch for suspension. |
| Lapsed Coverage | 15% - 30% Increase | Progressive | "Continuous insurance" discounts lost. |
| SR-22 Requirement | $25 - $50 Filing Fee | Mercury | Not all insurers offer SR-22 filings. |
Note: These percentages are estimates based on 2026 market trends in California and vary by ZIP code and vehicle type.
The Role of SR-22 in California
If your license has been suspended or revoked due to a DUI, reckless driving, or driving without insurance, the California DMV will likely require you to file an SR-22. Contrary to popular belief, an SR-22 is not insurance; it is a document issued by an insurance company that proves to the state that you carry the minimum required liability coverage.
In 2026, obtaining an SR-22 can be a hurdle because many "standard" or "preferred" insurance companies may choose to non-renew your policy once they learn an SR-22 is required. When shopping for the cheapest high-risk insurance, you must explicitly ask if the carrier can file an SR-22 electronically with the DMV. Companies like Progressive and Dairyland are specialists in this area, often processing the filing within 24 hours to help drivers reinstate their driving privileges quickly.
Strategies to Reduce Costs for High-Risk Drivers
Even with a high-risk designation, you are not powerless. There are several proactive steps you can take in 2026 to mitigate the high cost of insurance in California.
1. Telematics and Usage-Based Insurance (UBI)
Most major carriers in California now offer telematics programs (e.g., Progressive’s Snapshot or State Farm’s Drive Safe & Save). By installing an app or a plug-in device that monitors your braking, acceleration, and mileage, you can prove to the insurer that your actual driving behavior is safer than your past record suggests. While privacy concerns exist, the potential savings—sometimes up to 30%—make this a compelling option for high-risk drivers looking to lower their bills.
2. Increase Deductibles
If you carry collision and comprehensive coverage, increasing your deductible from $500 to $1,000 or $1,500 can significantly lower your monthly premium. However, this strategy should only be used if you have the funds set aside to cover that higher deductible in the event of a claim.
3. Defensive Driving Courses
In 2026, many California insurers offer a discount if you complete a DMV-approved defensive driving course. While the discount is often modest (around 5%), it also helps remove points from your driving record faster in the eyes of some insurers, potentially moving you back toward "Good Driver" status sooner.
4. Vehicle Selection
The vehicle you drive plays a massive role in your premium. For high-risk drivers, insuring a high-performance sports car or a luxury SUV can lead to astronomical rates. Switching to a vehicle with high safety ratings and lower repair costs—such as a used Honda Civic or Toyota Camry—can drastically reduce the base rate of your policy.
Navigating the Non-Renewal Process
In the 2026 California market, insurers are increasingly using "non-renewal" notices to shed high-risk clients. If you receive a notice that your current insurer will not be renewing your policy, do not panic, but act immediately. California law requires insurers to provide at least 30 days' notice before the policy expiration date.
During this window, you should:
- Request your CLUE report: This report shows your claims history. Ensure there are no errors, as an incorrectly reported accident can drive up your quotes.
- Shop around early: Don't wait until the final week of coverage. High-risk applications often require manual underwriting, which can take several days.
- Check CAARP: If you are denied by multiple private companies, the California Automobile Assigned Risk Plan is legally obligated to assign you an insurer, though this is typically a more expensive route than CLCA or Progressive.
Frequently Asked Questions
How long does a DUI stay on my insurance record in California?
In California, a DUI conviction typically affects your insurance rates for 10 years. While the points on your DMV record may technically expire sooner for license suspension purposes, Prop 103 allows insurers to look back a full decade when determining eligibility for the Good Driver discount. However, the most severe premium hikes usually occur in the first three to five years following the conviction.
Can I get cheap high-risk insurance if I don't own a car?
Yes, you can purchase a Non-Owner Auto Insurance policy. This is often the cheapest way for high-risk drivers to maintain continuous insurance coverage or fulfill an SR-22 requirement when they do not have regular access to a vehicle. Companies like Progressive and Mercury offer these policies at a fraction of the cost of a standard owner's policy.
Does my credit score affect my California insurance rates?
No. Under Proposition 103, California is one of the few states where insurance companies are strictly prohibited from using credit scores to determine auto insurance premiums. This is a major benefit for high-risk drivers who may also be facing financial difficulties, as their premiums are based solely on driving record, mileage, and years of experience.
What is the minimum liability coverage required in California in 2026?
As of 2026, California's mandatory minimum liability limits (unless insured via CLCA) remain at 15/30/5:
- $15,000 for injury/death to one person.
- $30,000 for injury/death to more than one person.
- $5,000 for damage to property. Note that these limits are quite low and may not fully protect your assets in a major accident.
How can I get points off my California driving record faster?
You can typically complete a Traffic Violator School (TVS) course once every 18 months to hide one point from your public driving record. While this helps with your DMV record and may prevent a license suspension, some insurance companies may still see the underlying violation during the underwriting process if it was not masked correctly.
Practical Recommendations
If you are a high-risk driver in California looking for the cheapest insurance in 2026, your first step should be to check your eligibility for the California Low Cost Automobile Insurance Program (CLCA) at mylowcostauto.com. This program is the floor of the market and provides the most significant savings for those on a budget.
If you do not qualify for CLCA due to income or vehicle value, obtain quotes from Progressive and Mercury simultaneously. These two companies currently dominate the competitive high-risk space in California. Always opt for a slightly higher deductible to lower your monthly outflow, and if you are required to file an SR-22, ensure the company handles the filing electronically to avoid delays in your license reinstatement. Finally, revisit your policy every 12 months; as your violations age, your risk profile improves, and you may find that a different carrier becomes the "cheapest" option for your evolving record.
Image Gallery
Select an image to open it in a new tab.
Celine Dubois
Contemporary Living and Global Arts Columnist
