How to Buy Private Health Insurance in 2026: A Comprehensive Step-by-Step Guide

To buy private health insurance, you must first determine if you qualify for a Special Enrollment Period or must wait for the annual Open Enrollment, which typically begins November 1. You can purchase coverage through the federal Health Insurance Marketplace, state-based exchanges, or directly from private insurance carriers and licensed brokers.
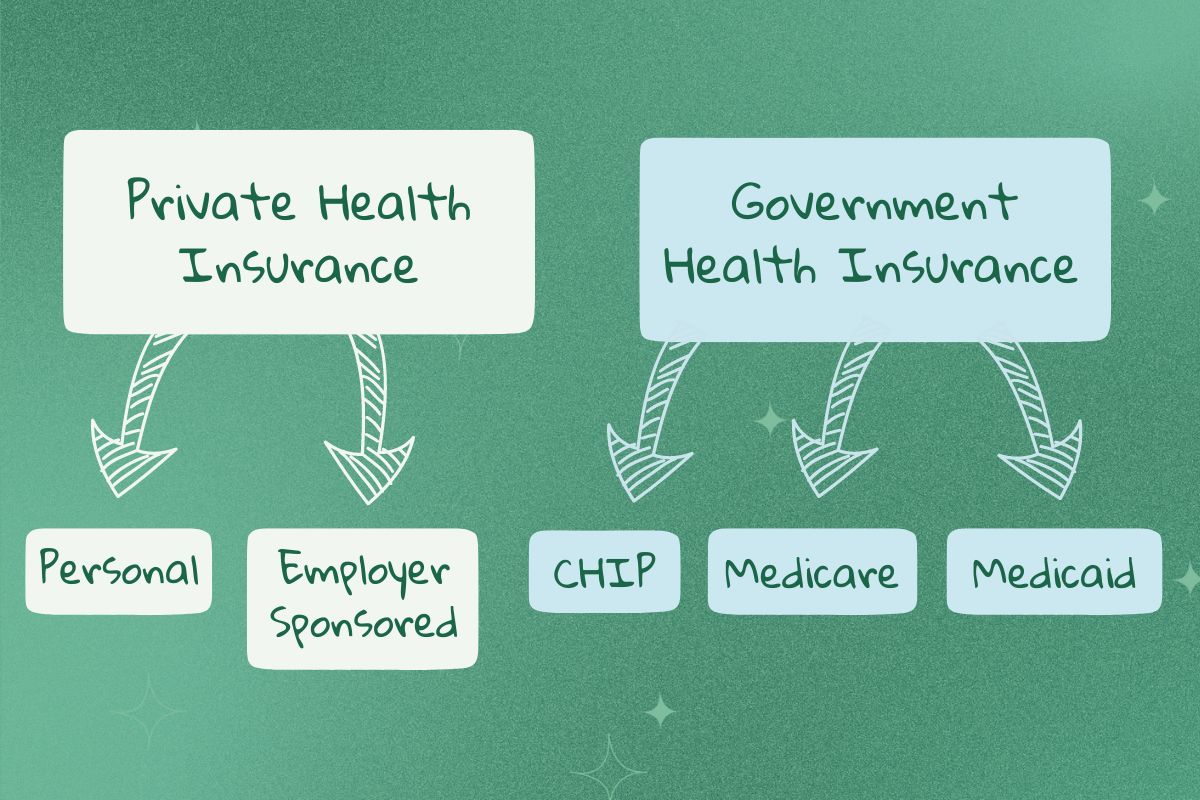
Private health insurance refers to any health coverage not funded by the government (such as Medicare or Medicaid). For 2026, the landscape of private insurance continues to be defined by the Affordable Care Act (ACA), which mandates specific "essential health benefits" for most plans. Whether you are self-employed, an early retiree, or working for a small business that does not offer benefits, navigating the private market requires a systematic approach to balance monthly premiums against potential out-of-pocket costs.
Understanding the Categories of Private Health Insurance
Before beginning the purchase process, it is critical to distinguish between the two primary ways to access private insurance: On-Exchange and Off-Exchange plans.
On-Exchange plans are sold through the Health Insurance Marketplace (Healthcare.gov) or state-equivalent portals. These plans are the only ones eligible for Premium Tax Credits (subsidies) and Cost-Sharing Reductions. In 2026, these subsidies remain a primary factor in affordability for middle-income households. If your income falls within specific ranges, the government pays a portion of your premium directly to the insurance company.
Off-Exchange plans are purchased directly from insurance companies or through private brokers. While these plans must still follow most ACA regulations—such as covering pre-existing conditions—they are not eligible for federal subsidies. Consumers often look toward the off-exchange market if they seek a specific niche provider network or if their income is high enough that they do not qualify for tax credits.
Furthermore, you must choose a "metal tier" that dictates how you and the insurer share costs. Bronze plans have the lowest premiums but highest deductibles; Silver plans are the benchmark for subsidies; Gold and Platinum plans have high premiums but much lower costs when you actually receive medical care.
Step 1: Determine Your Enrollment Window
You cannot buy private major medical insurance at any time of the year. For the 2026 plan year, the standard Open Enrollment Period (OEP) generally runs from November 1, 2025, to January 15, 2026. If you sign up by December 15, your coverage usually begins January 1. Applications submitted between December 16 and January 15 typically see coverage begin February 1.
Outside of these dates, you can only buy private insurance if you experience a Qualifying Life Event (QLE). This triggers a 60-day Special Enrollment Period (SEP). Common QLEs include:
- Loss of qualifying health coverage: This includes losing a job-based plan, turning 26 and "aging out" of a parent's plan, or losing Medicaid eligibility.
- Changes in household: Getting married, having a baby, adopting a child, or a death in the family that affects eligibility.
- Changes in residence: Moving to a new ZIP code or county that offers different plan options.
- Other specific circumstances: Gaining citizenship, leaving incarceration, or certain income changes that affect subsidy eligibility.

Step 2: Calculate Your Budget and Subsidy Eligibility
In 2026, the "Total Cost of Care" is the most important metric for your budget. This includes your monthly premium (the fixed cost to keep the policy active) and your out-of-pocket costs (deductibles, copayments, and coinsurance).
Before shopping, use a subsidy calculator on Healthcare.gov to estimate your Modified Adjusted Gross Income (MAGI). Because the 2026 tax year may involve specific inflation-adjusted thresholds, verifying your eligibility for Premium Tax Credits can save you thousands of dollars annually. If your income is below 250% of the Federal Poverty Level, you may also qualify for Cost-Sharing Reductions, but only if you choose a Silver-tier plan. These reductions lower your deductible and out-of-pocket maximum, effectively turning a Silver plan into a Gold or Platinum equivalent for a lower price.
Step 3: Compare Plan Network Types
Private insurance companies control costs by creating "networks" of doctors and hospitals. Choosing the wrong network type can lead to massive unexpected bills if you see a provider who is considered "out-of-network."
| Plan Type | Primary Care Physician (PCP) Required? | Referral Needed for Specialist? | Out-of-Network Coverage? | Network Flexibility |
|---|---|---|---|---|
| HMO (Health Maintenance Organization) | Yes | Yes | No (Except emergencies) | Low |
| PPO (Preferred Provider Organization) | No | No | Yes (At higher cost) | High |
| EPO (Exclusive Provider Organization) | No | No | No (Except emergencies) | Moderate |
| POS (Point of Service) | Yes | Yes | Yes (At higher cost) | Moderate |
For most consumers, a PPO offers the greatest freedom but comes with the highest premiums. If you have a specific doctor you trust, you must verify their participation in the specific plan's network for 2026 before enrolling. Network directories change annually, so never assume your doctor is still "in-network" because they were last year.
Step 4: Evaluate the Summary of Benefits and Coverage (SBC)
Every private health insurance plan is required to provide a Summary of Benefits and Coverage (SBC). This is a standardized document that allows you to compare plans "apples-to-apples." When reviewing an SBC, look beyond the premium and focus on:
- The Deductible: The amount you pay for covered services before the insurance company starts to pay.
- The Out-of-Pocket Maximum: The most you could possibly pay in a year for covered services. Once you hit this, the insurer pays 100% of allowed charges.
- Prescription Drug Formulary: Check if your specific medications are covered and what "tier" they fall into. Tier 1 is usually generic (cheap), while Tier 4 or 5 includes specialty drugs (expensive).
- Emergency Room vs. Urgent Care costs: Understanding these fees can help you manage costs during a minor medical crisis.
Step 5: Gather Necessary Documentation and Apply
Once you have selected a plan, the application process requires specific personal and financial information. Whether applying through a state exchange or a private carrier, have the following ready:
- Personal Information: Full legal names, dates of birth, and Social Security numbers for everyone in the household to be covered.
- Income Verification: Recent pay stubs, W-2s, or 1099 forms. For the self-employed, an estimated net income for 2026 is required.
- Current Coverage Details: If anyone in your household currently has insurance (even if it's ending), you will need the policy numbers.
- Citizenship Status: Documents proving legal residency or citizenship, such as a passport or Green Card.
You can complete the application online, by phone, or with the help of a certified navigator or licensed insurance agent. There is no cost to use a navigator or agent; they are paid by the insurance companies or through government grants.
Step 6: Finalize the Purchase and Confirm Enrollment
An application is not the same as a policy. Your private health insurance is not active until you make the first premium payment (the "binder payment"). Most insurers provide an online portal to pay this immediately after the application is processed.
After payment, you should receive a welcome packet and member ID cards within 7 to 14 days. Verify that the effective date on your ID card matches your expectations (usually January 1 for OEP applicants). If you do not receive confirmation, contact the insurer's customer service department immediately to ensure your application wasn't flagged for "data matching issues," which can happen if your reported income doesn't match IRS records.
Common Pitfalls to Avoid
- Ignoring the HSA Opportunity: If you buy a High Deductible Health Plan (HDHP), you may be eligible for a Health Savings Account (HSA). In 2026, the tax advantages of an HSA—tax-deductible contributions, tax-free growth, and tax-free withdrawals for medical expenses—make it a powerful financial tool for those who are relatively healthy.
- Underestimating Income: If you receive a subsidy based on an underestimated income, you may have to pay back some or all of the tax credit when you file your 2026 tax return in 2027. Always update the Marketplace if your income changes mid-year.
- Buying "Junk" Plans: Be wary of "fixed indemnity" or "medical discount" plans. These are often marketed as cheap private insurance but do not meet ACA standards. They may not cover hospital stays, surgery, or pre-existing conditions, leaving you with massive debt if you get seriously ill.
- Missing the Deadline: If you miss the January 15 deadline without a QLE, you will generally be unable to buy major medical private insurance for the remainder of 2026.
Frequently Asked Questions
Can I buy private health insurance if I have a pre-existing condition?
Yes. Under the Affordable Care Act, private health insurance companies cannot deny you coverage, charge you more, or exclude treatment for pre-existing conditions. This protection applies to all ACA-compliant plans, whether purchased on or off the Marketplace. The only factor that can significantly increase your premium (other than the plan type and your age) is tobacco use.
Is it cheaper to buy insurance directly from a company or through the Marketplace?
If you qualify for a premium subsidy, it is almost always cheaper to buy through the Marketplace. Subsidies are not available for plans purchased directly from private insurers (off-exchange). If you do not qualify for a subsidy, the prices are generally similar, but the off-exchange market may offer a wider variety of provider networks.
What is the difference between a deductible and an out-of-pocket maximum?
The deductible is the initial amount you pay for most services before the insurance company begins sharing the cost (coinsurance). The out-of-pocket maximum is the "safety net." It is the absolute maximum you will pay in a calendar year for covered, in-network services. Once you reach the maximum, the insurer pays 100% of all covered costs for the rest of the year.
Do I need a broker to buy private health insurance?
While not required, a licensed broker can be helpful, especially if you find the different network types and metal tiers confusing. Brokers can help you compare plans across multiple insurance companies. If you use a broker, ensure they are "Marketplace-certified" so they can still help you access federal subsidies if you are eligible.
How do I cancel my private insurance if I get a job with benefits?
If you move from a private plan to an employer-sponsored plan, you can cancel your private coverage at any time. If you bought through the Marketplace, you can log in to your account and select "Terminate Coverage." It is usually best to set the termination date for the day before your new employer's coverage begins to avoid a gap in insurance.
Practical Next Action
Before the next Open Enrollment begins on November 1, gather your projected income figures for 2026 and a list of your current prescriptions. Visit Healthcare.gov to check for state-specific deadline variations and use their "See Plans and Prices" tool to get a preliminary look at the 2026 rates in your area. This preparation ensures you can make an informed decision without the pressure of the mid-January deadline.
Image Gallery
Select an image to open it in a new tab.
Zara El-Hashem
Sociocultural Dynamics and Academics Writer
