For self-employed individuals, a home equity loan provides a way to access lump-sum capital by leveraging the appraised value of their primary residence. While the core product functions like a second mortgage with fixed interest rates, self-employed borrowers must undergo more rigorous income verification, typically requiring two years of tax returns, profit and loss statements, and 1099 records to prove stable earnings.
Navigating the financial landscape as a freelancer, contractor, or small business owner often feels like a balancing act. In 2026, as the "gig economy" and independent consulting continue to represent a massive segment of the workforce, lenders have refined their processes for evaluating non-traditional income. However, the fundamental challenge remains: how do you convince a bank of your creditworthiness when your income fluctuates and your tax returns are designed to minimize taxable profit?
Understanding a home equity loan for the self-employed requires looking beyond the interest rate. It involves a deep dive into "debt-to-income" (DTI) calculations, the nuances of "add-backs" for depreciation, and the strategic decision between a traditional bank and a non-QM (Non-Qualified Mortgage) lender.
The Fundamentals of Home Equity for Business Owners
A home equity loan, often referred to as a "second mortgage," allows you to borrow against the "equity" in your home—the difference between your home’s current market value and the remaining balance on your primary mortgage. For the self-employed, this capital can be a lifeline for business expansion, debt consolidation, or significant home improvements that further increase the property's value.
Unlike a Home Equity Line of Credit (HELOC), which acts like a credit card with a variable rate, a home equity loan provides a one-time payment. This payment is then repaid over a fixed term—usually 5 to 20 years—at a fixed interest rate. In the economic climate of 2026, where interest rate volatility is a constant consideration, the stability of a fixed-rate home equity loan offers a predictable monthly expense that can be easier for a fluctuating business budget to absorb.
Equity Requirements and LTV Limits
Lenders typically allow you to borrow up to 80% or 85% of your home's value, known as the Loan-to-Value (LTV) ratio. For example, if your home is valued at $500,000 and you owe $300,000 on your first mortgage, your total available "room" at an 80% LTV is $400,000 ($500,000 x 0.80). Subtracting your existing $300,000 mortgage leaves you with a maximum potential loan of $100,000.
For self-employed borrowers, some lenders may slightly lower the maximum LTV to 75% to mitigate the perceived risk of inconsistent income. Establishing a significant equity cushion is therefore the first prerequisite for any successful application.
The Verification Hurdle: Why It Is Different for the Self-Employed
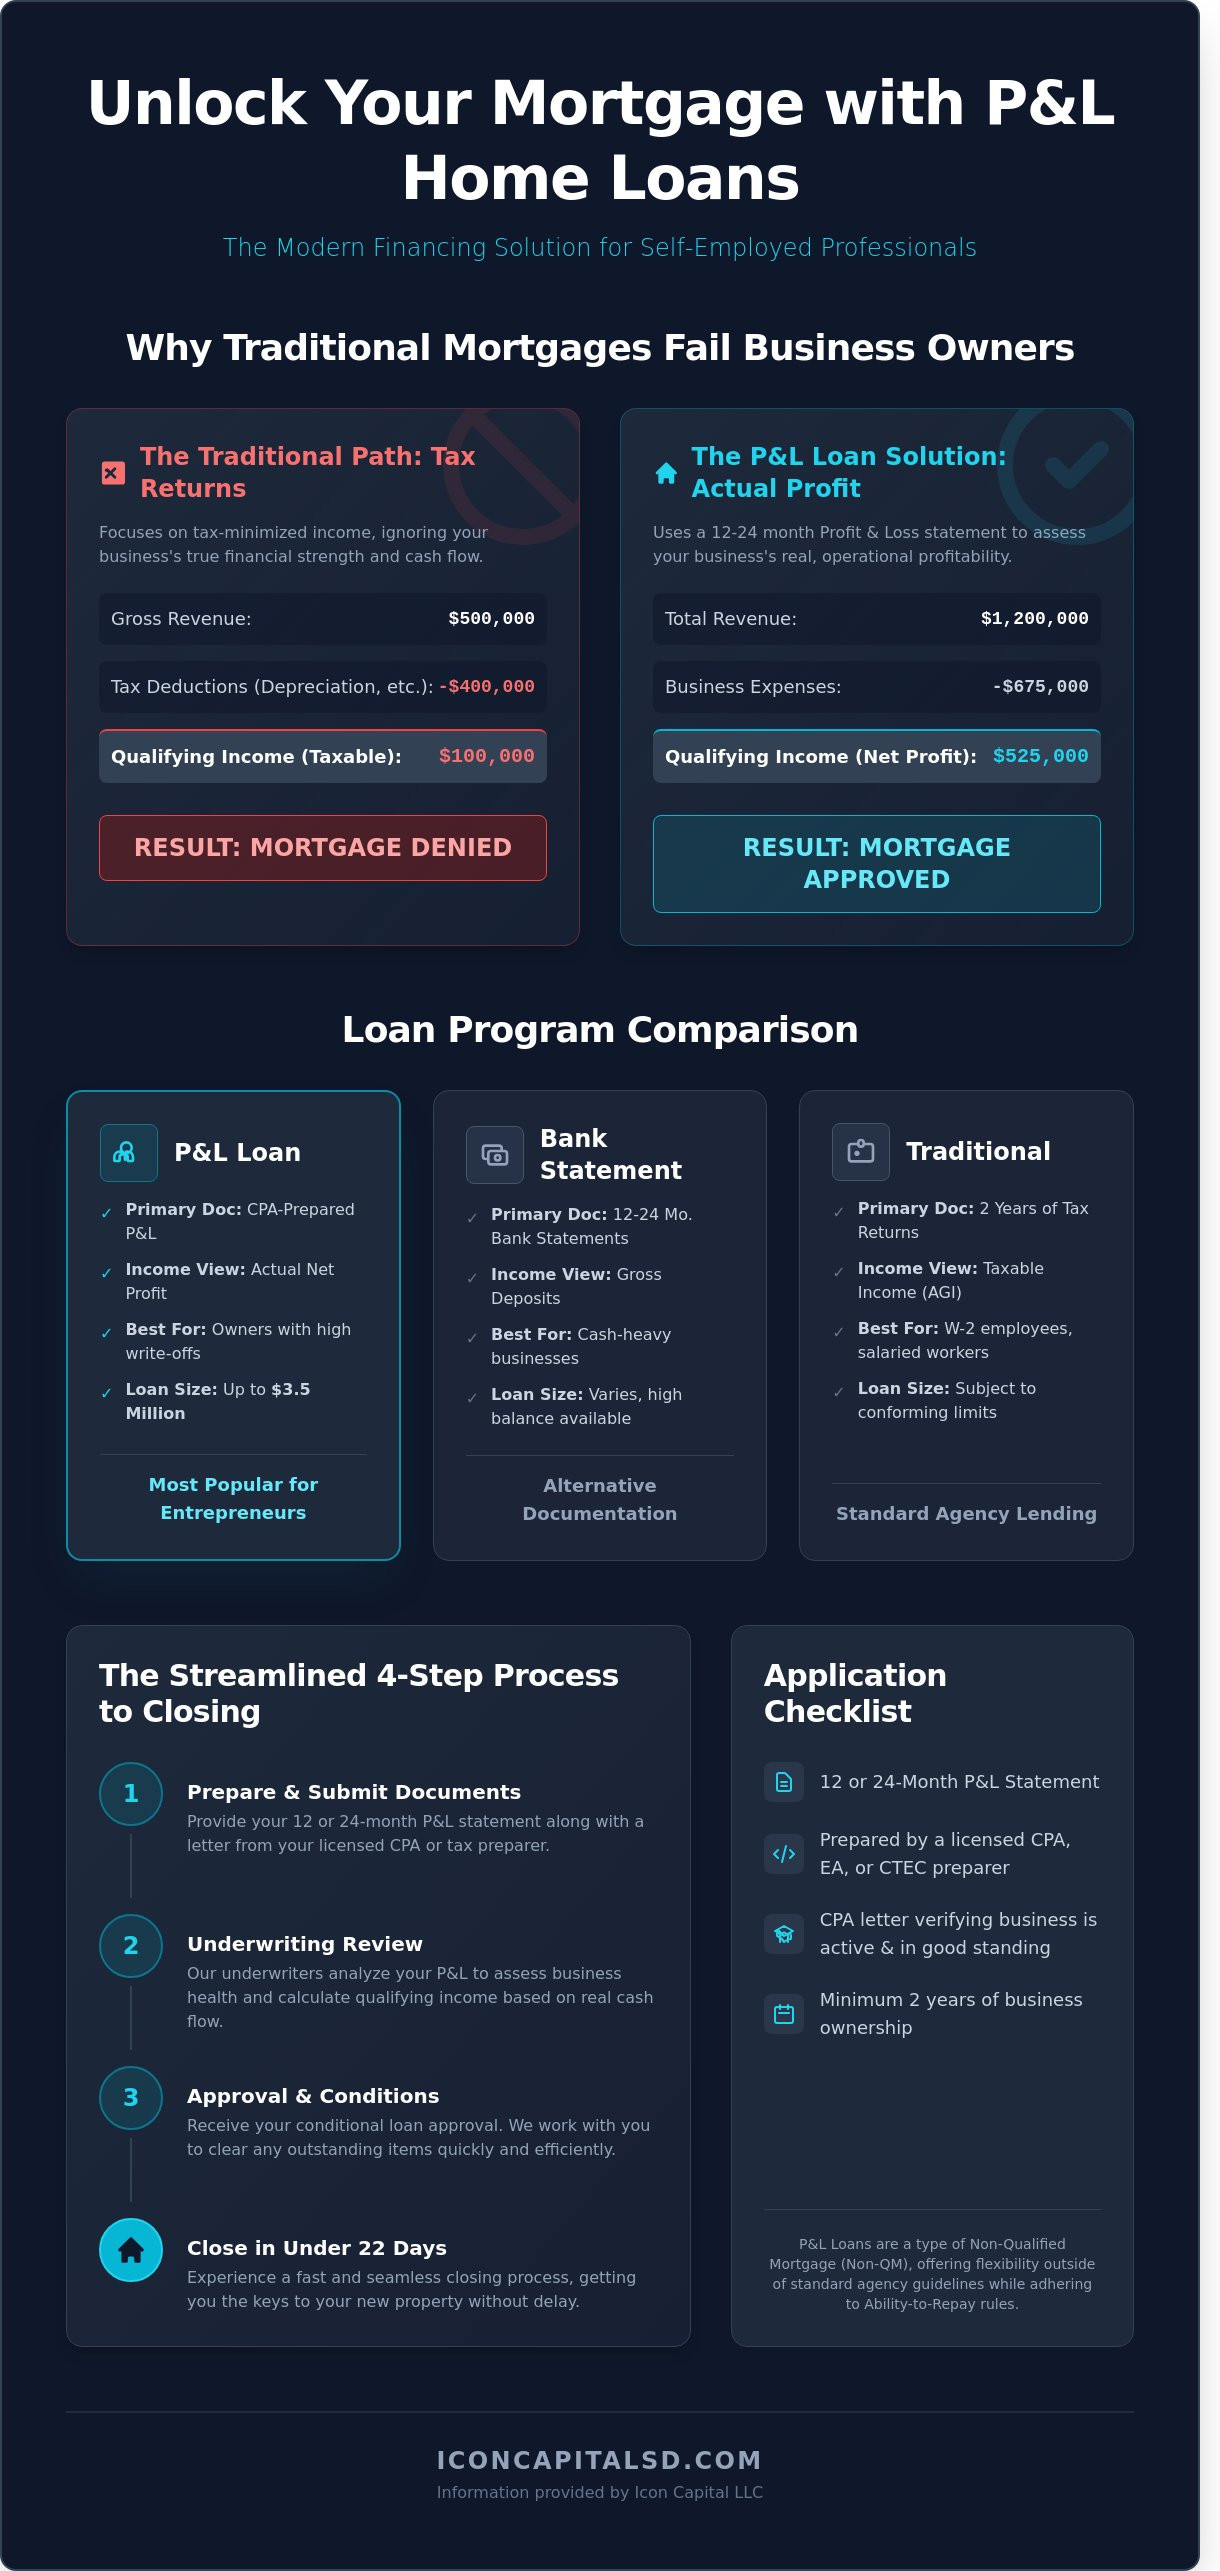
The primary friction point in securing a home equity loan as a self-employed individual is the verification of "qualifying income." A W-2 employee provides a few pay stubs and a W-2 form, and the lender accepts the gross income. For a business owner, the lender starts with the net income reported to the IRS.
The Tax Deduction Paradox
As a business owner, you likely work with an accountant to maximize legal tax deductions. While reducing your taxable income is excellent for your tax bill, it can be detrimental to your loan application. If your business grossed $200,000 but you claimed $150,000 in expenses and deductions, a lender sees your income as $50,000. This lower figure is what they use to calculate your Debt-to-Income (DTI) ratio.
The "Add-Back" Process
Experienced lenders in 2026 utilize an "add-back" system to get a more accurate picture of your cash flow. Certain non-cash expenses that appear on your tax returns can be added back to your net income to help you qualify. Common add-backs include:
- Depreciation: Since depreciation is an accounting expense and not a physical cash outflow, most lenders will add this back to your income.
- Amortization: Similar to depreciation, this is often treated as a paper loss.
- Home Office Deductions: Specifically the portion related to utilities or insurance that doesn't represent an external business cost.
- One-time Business Expenses: If you had a singular, non-recurring cost (like a major equipment repair), some lenders may exclude it from their negative calculations.

Essential Documentation for the 2026 Applicant
To succeed in the current lending environment, preparation of a "loan bible" is essential. Lenders are no longer just looking at the last year of performance; they want to see a trajectory of stability.
- Personal and Business Tax Returns: Usually the most recent two years. This includes all schedules (Schedule C for sole proprietors, Schedule E for S-Corp owners, etc.).
- Year-to-Date (YTD) Profit and Loss (P&L) Statement: Lenders want to see that your business has remained profitable since your last tax filing. In 2026, many lenders require this to be signed by a CPA.
- Business Bank Statements: Usually 3 to 12 months of statements. This proves that the "paper income" on your P&L is actually flowing through your accounts.
- Verification of Business Existence: This can be a business license, a letter from a CPA, or proof of a business insurance policy.
- 1099 Forms: If you are a contractor, these provide a secondary layer of verification for your gross receipts.
Comparing Standard vs. Alternative Lending Paths
Not every self-employed borrower fits into the "Conventional" box. If your tax returns show too little income to qualify for a traditional home equity loan, you may need to look at Non-Qualified Mortgage (Non-QM) products.
| Feature | Traditional Home Equity Loan | Bank Statement / Non-QM Loan |
|---|---|---|
| Income Verification | Tax Returns (IRS Form 1040) | 12-24 Months of Bank Statements |
| Interest Rates | Lower (Market Standard) | Higher (typically 1% - 3% premium) |
| Credit Score | Usually 680+ Required | Often more flexible (620+) |
| DTI Requirements | Strict (usually < 43%) | More flexible (up to 50%) |
| Approval Speed | 30 - 45 Days | 15 - 30 Days |
| Best For | Established businesses with high net profits | Growth-stage businesses with high cash flow |
Bank Statement Loans: The Alternative Route
In 2026, bank statement loans have become a mainstream alternative for the self-employed. Instead of looking at tax returns, the lender analyzes your monthly deposits into your business or personal accounts. They typically average these deposits over 12 or 24 months and apply an "expense ratio" (often 50% for service businesses) to determine your qualifying income. This is an ideal solution for those who have high revenue but significant tax write-offs.
Strategic Benefits of a Home Equity Loan in 2026
Choosing a home equity loan over a personal loan or a business line of credit offers several distinct advantages for the self-employed professional.
Lower Interest Rates
Because the loan is secured by your real estate, the risk to the lender is significantly lower than it is for an unsecured personal loan. In 2026, interest rates for home equity loans remain competitive compared to the double-digit rates often found on business credit cards or unsecured "working capital" loans.
Potential Tax Deductibility
While tax laws are complex, the interest on a home equity loan may be tax-deductible if the funds are used to "buy, build, or substantially improve" the home that secures the loan. For a self-employed individual who works from home, certain improvements to a home office or the property at large may offer dual benefits: increasing property value and providing a potential tax shield. Note: Always consult with a qualified tax professional regarding current 2026 IRS regulations.
Debt Consolidation
Many entrepreneurs use personal credit to float business expenses during lean months. Consolidating high-interest credit card debt into a single, lower-interest home equity loan can drastically improve your monthly cash flow, making it easier to reinvest in your business operations.
Common Mistakes to Avoid
The path to a home equity loan is fraught with potential pitfalls for the self-employed. Avoiding these can mean the difference between an approval and a rejection.
- Drastic Changes in Business Structure: Switching from a Sole Proprietorship to an S-Corp right before applying can reset the "two-year clock" for some conservative lenders. Try to maintain a consistent legal structure for at least 24 months before your application.
- Large Unexplained Deposits: Lenders scrutinize bank statements for "source of funds." If you received a large personal gift or a one-time non-business windfall, document it clearly so it isn't confused with regular business revenue.
- Applying During a "Down" Year: If your 2025 was a year of heavy investment with low profits, wait until your 2026 YTD P&L shows a strong recovery before approaching a lender.
- Co-mingling Funds: Using your personal account for business expenses (or vice versa) makes it incredibly difficult for a loan officer to verify your true income. Professionalized bookkeeping is your greatest asset.
Step-by-Step Application Guide for 2026
- Check Your Credit and Equity: Ensure your credit score is at least 680 and you have at least 15-20% equity in your home.
- Organize Your Bookkeeping: Use software like QuickBooks or Xero to generate clean P&L statements. Ensure your 2024 and 2025 tax returns are filed and accessible.
- Research Lenders: Start with your current mortgage holder, but don't stop there. Look for credit unions and specialized "self-employed friendly" lenders who offer bank statement programs.
- Get a Pre-Qualification: Provide your basic numbers to a loan officer to see if you are in the right ballpark for the amount you need.
- Formal Application and Appraisal: Once you apply, the lender will order an appraisal of your home. Be prepared for a site visit to verify the property's condition.
- Underwriting Q&A: This is the most intense phase for the self-employed. Be prepared to answer "Letters of Explanation" (LOX) regarding any fluctuations in your business income or large expenses.
Frequently Asked Questions
Can I get a home equity loan if I've been self-employed for less than two years?
It is significantly more difficult, but not impossible. Some lenders will accept one year of tax returns if you were in the same field for several years as a W-2 employee before starting your business. However, expect to pay a higher interest rate or be required to have a higher credit score.
Will a home equity loan affect my business credit score?
Usually, no. Home equity loans are personal debts secured by your residence. They will appear on your personal credit report (affecting your personal FICO score), but they typically do not report to business credit bureaus like Dun & Bradstreet unless you are borrowing through a formal business entity and providing a personal guarantee.
Can I use the funds for business purposes?
Yes. Once the funds are disbursed, you have the flexibility to use them for anything—from hiring new staff and buying inventory to personal debt consolidation. However, remember that if the funds are used for business and not "home improvement," the interest is generally not deductible as home mortgage interest.
What is the minimum credit score for a self-employed home equity loan in 2026?
Most traditional lenders look for a score of 680 or higher. Some non-QM lenders may go as low as 620, but these loans often come with lower LTV limits (e.g., they will only lend up to 70% of the home's value) and significantly higher interest rates.
How does "Net Operating Income" differ from the income the lender uses?
Lenders often use "Qualifying Income," which is your Net Income from your tax returns plus specific add-backs like depreciation. Your "Net Operating Income" (NOI) might be what you use to run your business, but the lender's formula is more rigid and tied to what you actually reported to the government.
Recommendation for Next Actions
If you are a self-employed professional seeking a home equity loan in 2026, your first step should be a consultation with a mortgage broker who specializes in "Alternative Documentation" or "Non-QM" loans. Unlike a standard bank officer, a specialized broker has access to multiple lending "buckets" and can determine whether your tax returns or your bank statements will give you a better chance of approval.
Simultaneously, ensure your bookkeeping is up to date through the current month. A clean, professional Profit and Loss statement is often the "tipping point" that gives an underwriter the confidence to approve a self-employed application. By demonstrating a clear understanding of your cash flow and maintaining a strong equity position, you can successfully leverage your home to provide the capital necessary for your personal or professional growth.
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
