Understanding Auto Insurance in 80920: A Comprehensive Guide for Colorado Springs Residents

Navigating auto insurance in the 80920 ZIP code requires a balance of meeting Colorado’s state-mandated minimums and protecting against localized risks like severe Front Range hail and heavy Briargate traffic. In 2026, residents must secure at least 25/50/15 liability coverage while considering comprehensive and uninsured motorist protections to address El Paso County’s specific environmental and driving conditions.
Understanding auto insurance in the northern reaches of Colorado Springs, specifically the 80920 ZIP code, involves more than just finding the lowest monthly premium. This area, which encompasses much of the Briargate community and sits adjacent to the United States Air Force Academy, presents a unique profile for insurance underwriters. From the high-density traffic along the Interstate 25 and Woodmen Road corridors to the volatile weather patterns that roll off the Rampart Range, drivers in this region face specific challenges that dictate the structure and cost of their insurance policies.
Colorado’s Legal Framework for Auto Insurance
Before diving into the specifics of the 80920 area, it is essential to understand the legal foundation upon which all Colorado auto policies are built. Colorado operates under a tort system, which means that the driver found at fault in an accident is responsible for all resulting damages, including medical expenses and property repairs.
State Minimum Liability Requirements
As of 2026, the Colorado Division of Insurance maintains specific minimum requirements for all registered motor vehicles. These are often referred to as "25/50/15" coverage:
- $25,000 for bodily injury per person: This covers medical expenses, lost wages, and pain and suffering for a single individual injured in an accident where you are at fault.
- $50,000 for bodily injury per accident: This is the total cap the insurance company will pay for all injuries sustained by multiple people in a single accident.
- $15,000 for property damage: This pays for repairs to the other party's vehicle, fences, buildings, or other property damaged in the collision.
While these are the legal minimums, insurance professionals in Colorado Springs generally advise against them. In 2026, the cost of medical care and the average price of a new vehicle often far exceed these limits. If you are at fault in an accident that causes $40,000 in property damage, your $15,000 limit leaves you personally liable for the remaining $25,000.
Medical Payments (MedPay) Coverage
Colorado law requires insurance companies to offer at least $5,000 in Medical Payments (MedPay) coverage. This is a "no-fault" portion of the policy that pays for immediate medical expenses for you and your passengers, regardless of who caused the accident. While you can opt out of this coverage in writing, it remains a critical safety net for residents in 80920 who may face high health insurance deductibles.
Local Risk Factors Specific to the 80920 ZIP Code
The 80920 ZIP code is one of the most desirable areas in Colorado Springs, but it also carries higher-than-average insurance risks due to geography and infrastructure.
The Impact of "Hail Alley"
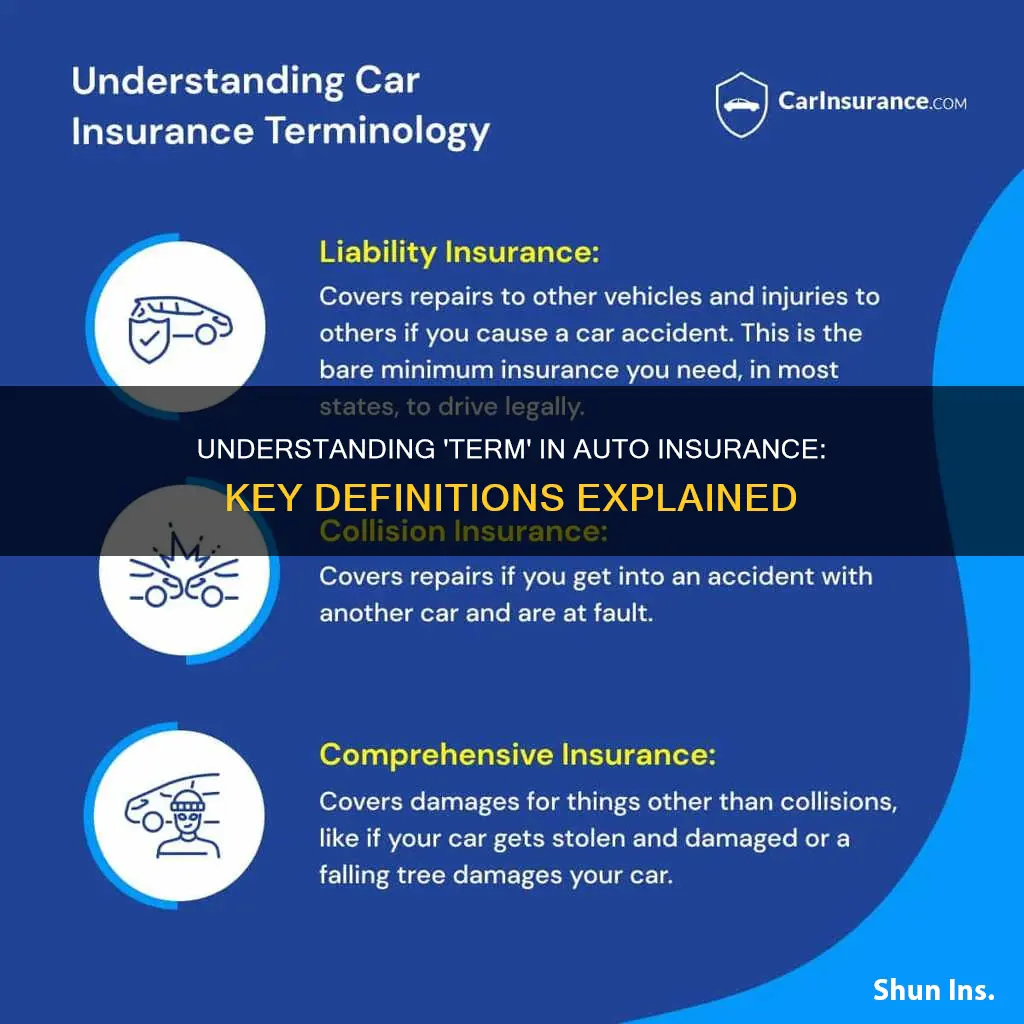
Colorado Springs is situated in the heart of "Hail Alley." The 80920 area, due to its elevation and proximity to the mountains, is frequently targeted by severe thunderstorms that produce large, damaging hail. In the context of auto insurance, this makes Comprehensive Coverage a non-negotiable for most residents.
Comprehensive insurance covers "acts of God," including hail, wind, fire, and theft. In 80920, a single hailstorm can result in thousands of dollars in "total loss" claims for vehicles parked outside. When selecting a policy in 2026, residents should pay close attention to their comprehensive deductible. A $500 deductible may result in higher premiums but offers more manageable out-of-pocket costs after a localized storm event.
Traffic Density and Commuter Hazards
The 80920 area is a major residential and commercial hub. The intersection of I-25 and Briargate Parkway, as well as the heavy flow of traffic on Woodmen Road, contributes to a higher frequency of "fender benders" and multi-vehicle collisions.
Furthermore, the proximity to the Air Force Academy means a high volume of transient traffic and young drivers, which insurance algorithms often associate with increased risk. Higher traffic density naturally leads to higher liability premiums compared to more rural ZIP codes in El Paso County.
Uninsured and Underinsured Motorist Statistics
A persistent issue in Colorado is the rate of uninsured motorists. According to historical data from the Insurance Research Council, Colorado has frequently ranked in the upper tier of states for uninsured drivers. In 2026, this remains a significant concern for 80920 residents.
If you are involved in a hit-and-run or an accident with a driver who carries only the state minimums (or no insurance at all), Uninsured/Underinsured Motorist (UM/UIM) coverage is the only mechanism that protects your financial interests. This coverage steps in to pay for your medical bills and lost wages when the at-fault driver’s insurance is insufficient.
Determining the Right Coverage Limits for 2026
Given the rising costs of vehicle technology and medical inflation, the 2026 insurance landscape requires more robust limits than in previous decades.
| Coverage Type | Statutory Minimum | Recommended for 80920 Residents | Why the Difference Matters |
|---|---|---|---|
| Bodily Injury | $25,000 / $50,000 | $100,000 / $300,000 | Protects personal assets against major medical lawsuits. |
| Property Damage | $15,000 | $100,000 | The average SUV or EV in 80920 costs over $50,000. |
| MedPay | $5,000 (Optional) | $10,000+ | Covers immediate ER visits and health insurance gaps. |
| Uninsured Motorist | Not Required | Match Bodily Injury Limits | Essential due to high local rates of uninsured drivers. |
| Comprehensive | Not Required | Full Coverage ($500 Deductible) | Mandatory for protection against frequent hail damage. |
| Collision | Not Required | Full Coverage ($500 Deductible) | Necessary for accidents on high-traffic roads like I-25. |
Factors Influencing Premiums in Northern Colorado Springs
Insurance companies use hundreds of variables to determine your specific rate in 80920. Understanding these can help you manage your costs more effectively.
Credit-Based Insurance Scores
In Colorado, insurers are permitted to use your credit history as a factor in setting premiums. Individuals with higher credit scores are statistically shown to file fewer claims, leading to lower rates. If you are looking to lower your insurance costs in 80920, improving your credit profile is often as effective as shopping for different carriers.
Telematics and Usage-Based Insurance (UBI)
By 2026, nearly every major carrier (such as State Farm, Progressive, and GEICO) offers a telematics program. These involve using a smartphone app or a plug-in device to monitor driving habits like braking, acceleration, and time of day spent on the road. For 80920 residents who work from home or have short commutes to local offices in Briargate, UBI can result in significant discounts—sometimes up to 30%.
Vehicle Safety and Repairability
The types of vehicles popular in 80920—specifically luxury SUVs and Electric Vehicles (EVs)—carry higher insurance costs. This is due to the advanced driver-assistance systems (ADAS) integrated into bumpers and windshields. In 2026, a simple bumper replacement on a modern vehicle involves recalibrating sensors and cameras, which dramatically increases claim payouts and, subsequently, premiums.
The "Military Discount" Factor
Given the proximity to the Air Force Academy and Fort Carson, many residents in 80920 are active-duty military or veterans. Insurers like USAA specialize in this demographic, often providing rates and service levels that are difficult for standard carriers to match. Always verify your eligibility for military-affiliated insurance, as it remains one of the strongest ways to save in El Paso County.
How to Manage a Claim in the 80920 Area
Should you find yourself in an accident or discover hail damage after a storm, the steps you take immediately following the event are crucial for a smooth insurance experience.
- Document the Scene: Use your smartphone to take wide-angle and close-up photos of all vehicles involved, the surrounding environment (traffic signs, weather conditions), and any property damage.
- File a Police Report: For accidents on Woodmen Road or I-25, the Colorado Springs Police Department or Colorado State Patrol should be notified. A formal report is often required by insurers for claims exceeding a certain dollar amount.
- Choose the Right Repair Shop: Many residents in 80920 prefer using certified collision centers in the northern part of the city to avoid long tow distances. Ensure the shop works directly with your insurer to streamline the supplemental estimate process, which is common in complex hail or collision repairs.
- Mitigate Further Damage: If your windshield is cracked or a window is broken due to hail, cover it immediately. Insurance policies typically require the policyholder to take "reasonable steps" to prevent additional damage (like rain entering the vehicle) after the initial event.
Common Mistakes to Avoid
When "understanding auto insurance in 80920," many residents fall into traps that can lead to financial hardship during a claim.
- Underestimating Property Damage Limits: Many people assume $15,000 or $25,000 is plenty. However, if you hit a Tesla or a high-end pickup truck—common sights in the 80920 area—you could easily exceed those limits in seconds.
- Choosing Too High a Deductible for Comprehensive: While a $1,000 deductible lowers your monthly premium, it can be a barrier to getting your car fixed after a common Colorado hailstorm.
- Neglecting the "Gap": If you have a loan or lease on a newer vehicle, ensure you have Gap Insurance. Because cars depreciate quickly, you might owe more on your loan than the insurance company pays out for a total loss.
Frequently Asked Questions
Does my auto insurance cover my car if it’s damaged by hail in 80920?
Yes, provided you have Comprehensive Coverage. Liability-only policies do not cover weather-related damage. In Colorado Springs, comprehensive coverage is highly recommended because of the frequency of severe hailstorms. You will still be responsible for paying your chosen deductible before the insurance company covers the remaining repair costs.
How does living near the Air Force Academy affect my rates?
Living near a major military installation like the Air Force Academy can influence rates in two ways. First, the high volume of traffic can slightly increase the base rate for the ZIP code. However, many insurance companies offer significant discounts for active-duty military, veterans, and their families, which often more than offsets the localized rate increase.
Is Uninsured Motorist coverage mandatory in Colorado?
No, UM/UIM coverage is not mandatory, but Colorado law requires insurance companies to offer it to you in writing. You must specifically sign a waiver to reject it. Given that a significant percentage of drivers in the Colorado Springs area may be underinsured or completely uninsured, keeping this coverage is considered a best practice for financial protection.
Will my rates go up if I file a hail claim?
In Colorado, insurance companies generally cannot raise your individual rates solely because of a comprehensive claim for an "Act of God," such as hail. However, if an entire ZIP code like 80920 experiences a catastrophic storm, the insurance company may raise the base rates for the entire area during the next filing period to account for the increased regional risk.
What is the best way to lower my car insurance in 80920?
The most effective ways to lower premiums in 2026 include bundling your auto and homeowners insurance, participating in telematics (usage-based) programs, increasing your deductibles, and maintaining a high credit score. Additionally, residents should shop for new quotes every two years, as insurance companies frequently update their pricing models for specific ZIP codes.
Next Actions for 80920 Residents
To ensure you are properly protected, start by reviewing your current "Declarations Page." Check your property damage limits and confirm you have comprehensive coverage with a deductible you can afford to pay on short notice. If you haven't compared rates since 2024 or 2025, contact a local independent agent in Colorado Springs who can provide quotes from multiple carriers tailored to the unique risks of the 80920 area. For more information on state-specific regulations, visit the Colorado Department of Regulatory Agencies (DORA).
Image Gallery
Select an image to open it in a new tab.
Zara El-Hashem
Sociocultural Dynamics and Academics Writer
