
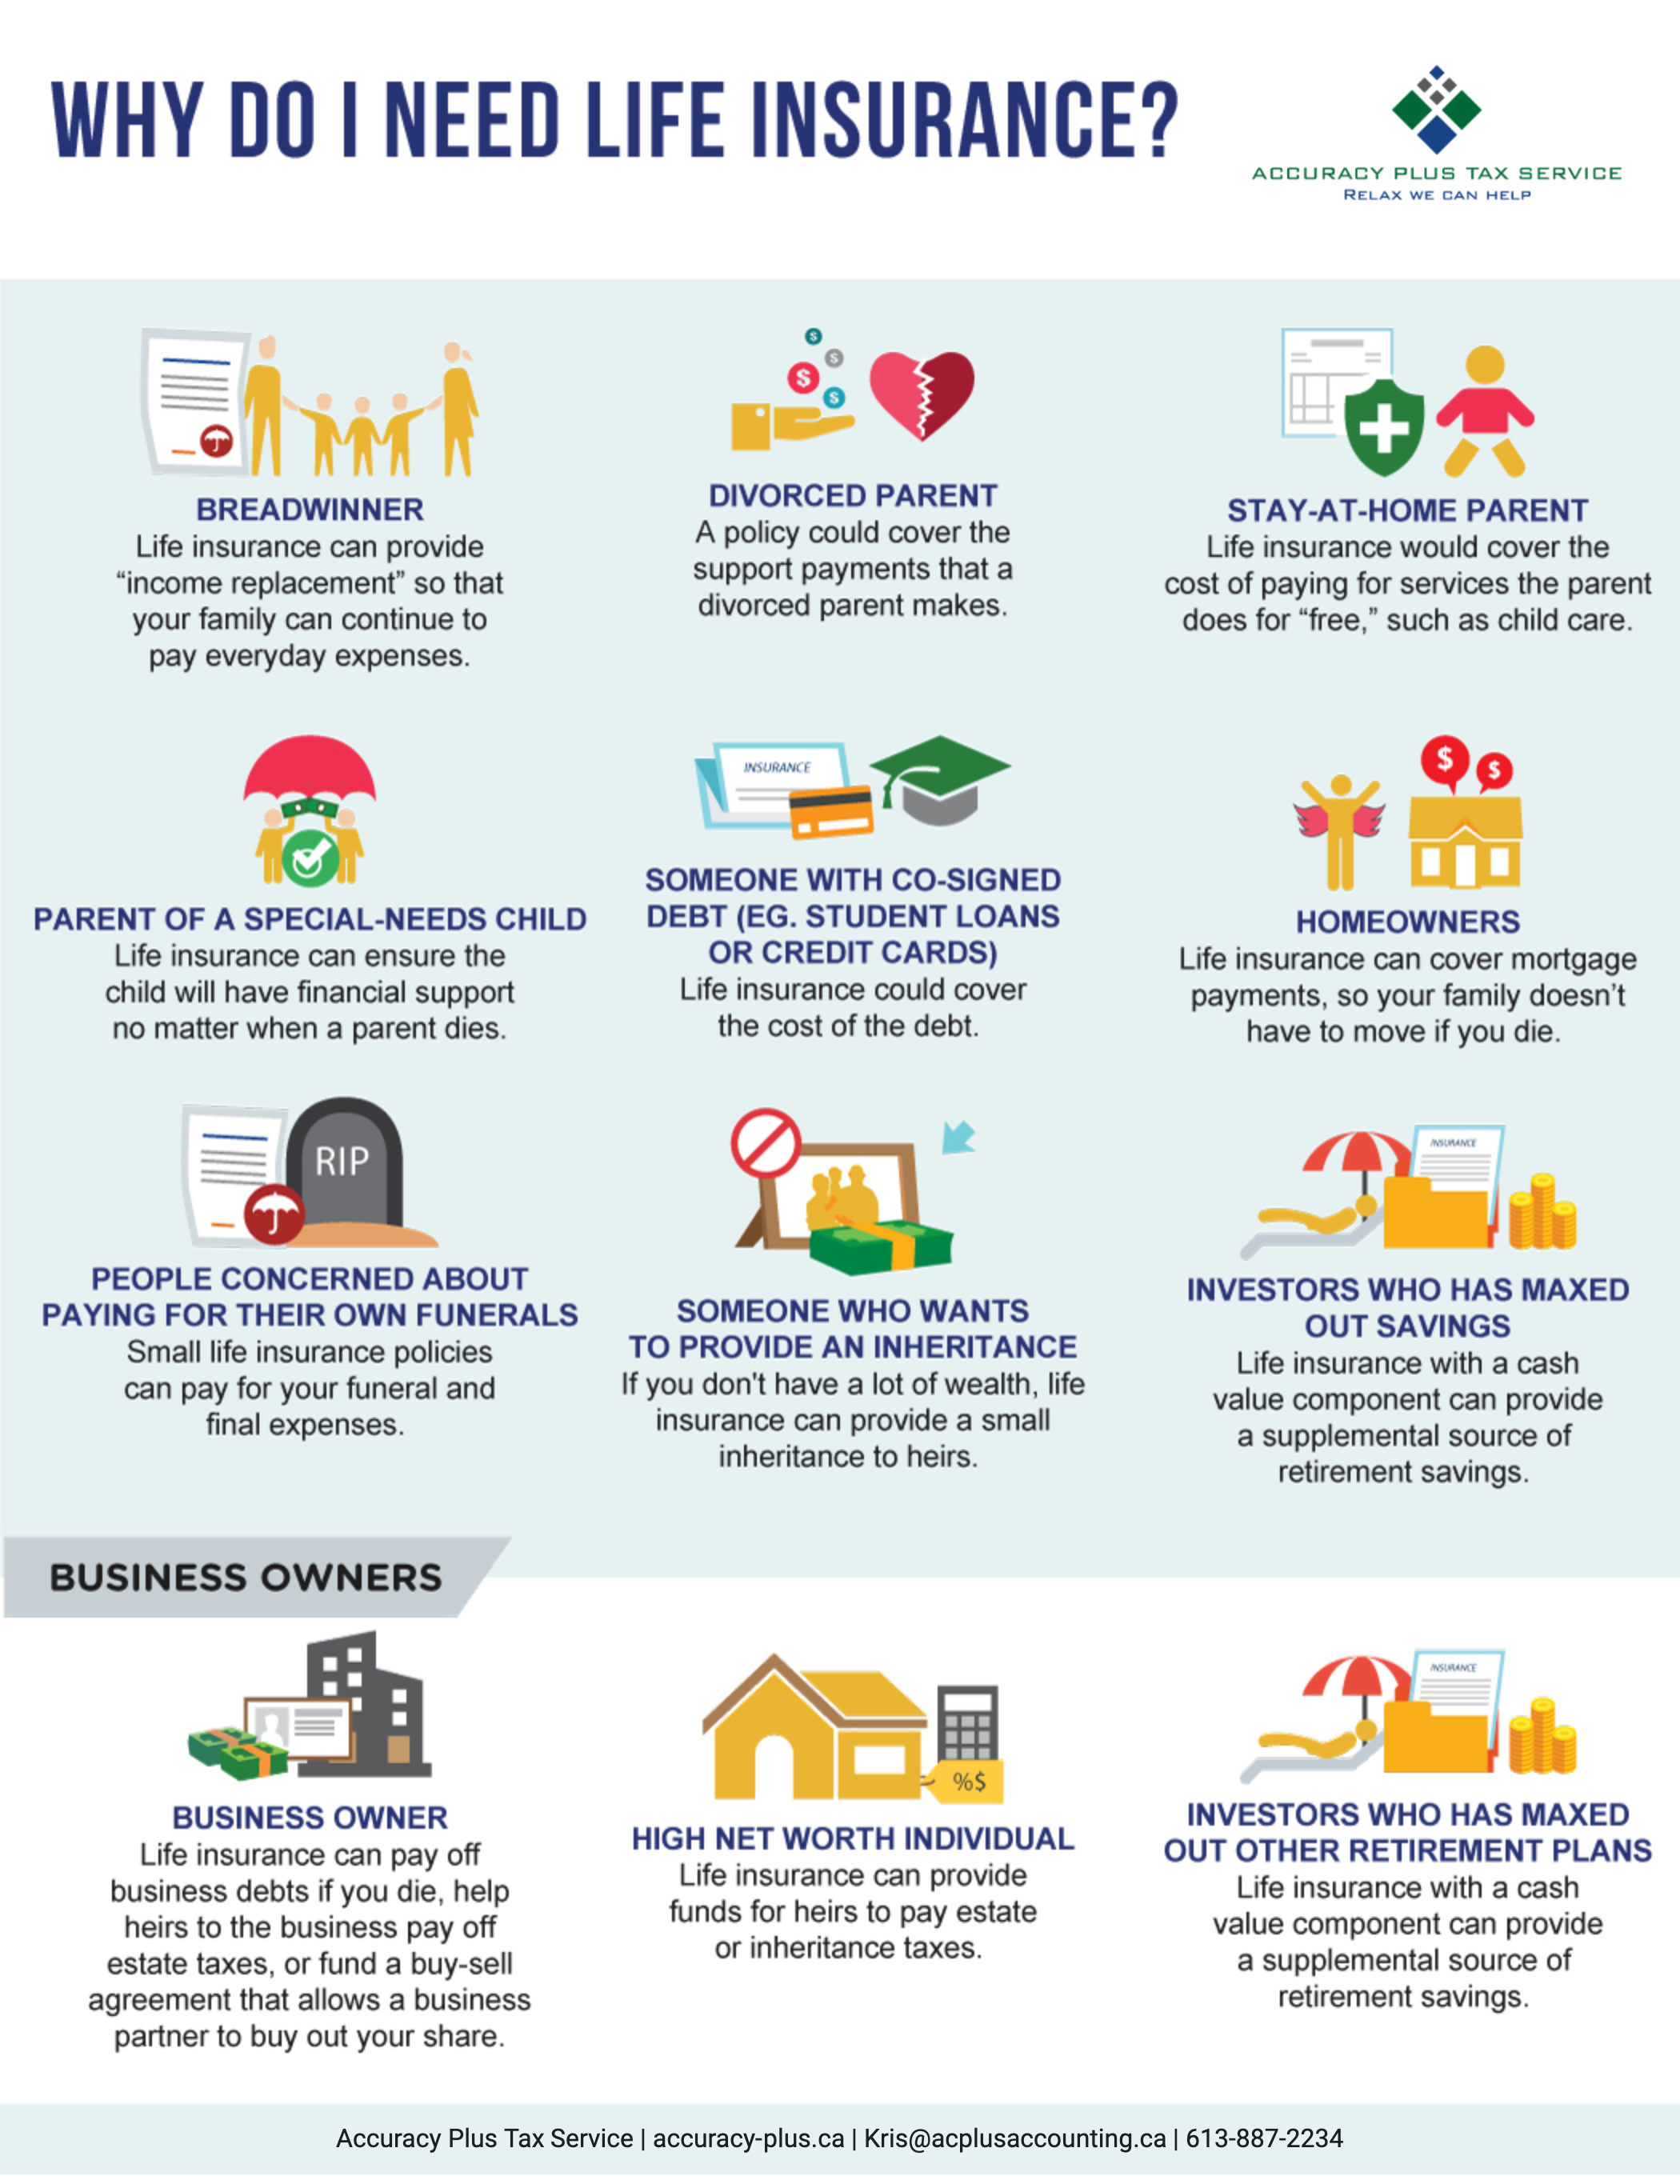
You need to get life insurance the moment someone else depends on your income or labor to maintain their standard of living. Common triggers include getting married, becoming a parent, purchasing a home with a mortgage, or starting a business. Essentially, if your death would create a financial vacuum for survivors, coverage is necessary.
Life insurance is not a product you buy for yourself; it is a financial tool you purchase for those you leave behind. While the concept seems straightforward, the timing is critical. In 2026, the insurance landscape is shaped by more personalized underwriting and a wider array of "living benefits," making the decision of when to enter the market more nuanced than in previous decades. Determining the right moment requires an honest assessment of your financial liabilities, your dependents’ future needs, and your current health status.
The Fundamental Trigger: Identifying Financial Dependents
The most significant indicator that you need life insurance is the existence of financial dependents. A dependent is not strictly defined as a minor child; it includes anyone who would suffer a loss of quality of life or be unable to meet financial obligations without your contribution.
In 2026, the definition of a dependent continues to evolve. It may include a spouse who relies on your salary to pay the mortgage, an aging parent for whom you provide long-term care, or even a business partner who would struggle to keep a company solvent if you were no longer there to manage operations. When your income is the glue holding a family or business budget together, life insurance serves as the necessary solvent to keep those structures intact.
If you are single, have no debt, and no one relies on your income, the need for life insurance is minimal. However, even in these cases, some individuals choose to lock in lower premiums while they are young and healthy, anticipating future needs. This proactive approach ensures that when they eventually reach a milestone—like marriage or parenthood—they are already protected at a significantly lower cost than if they had waited.
Key Life Milestones That Mandate Coverage
Life insurance needs are rarely static. They fluctuate based on "insurable interest," a legal and financial concept where a person or entity has a valid reason to protect your life. Several specific milestones serve as the primary catalysts for seeking coverage.
Marriage and Domestic Partnerships
When two people merge their lives, they often merge their finances. This includes shared bank accounts, joint leases, and co-signed loans. If one partner’s income is suddenly removed, the surviving partner may find it impossible to maintain their current lifestyle or even stay in their home.
In 2026, many dual-income households rely on both salaries to meet rising costs of living. If you and your partner have structured your life around two incomes, you both likely need life insurance. This ensures that the surviving partner can pay off shared debts, cover funeral expenses, and have a "bridge" of capital to adjust to a single-income reality without immediate financial panic.
Growing Your Family: The Impact of Children
The birth or adoption of a child is perhaps the most common reason people seek life insurance. Children are financial dependents for at least two decades, requiring food, clothing, healthcare, and education. According to the U.S. Department of Agriculture, the cost of raising a child has continued to climb, making life insurance a non-negotiable part of modern parenting.
When calculating coverage for children, parents must consider more than just immediate needs. You must factor in:
- Income Replacement: How many years of your salary would be needed to support the child until adulthood?
- Education Savings: Will the policy provide enough to cover future college or vocational training costs?
- Childcare Costs: If a primary caregiver passes away, the cost of replacing their labor (daycare, transportation, household management) is often higher than many families realize.
Homeownership and the Mortgage Burden
A home is often a family’s largest asset but also its largest debt. Most mortgage lenders do not require life insurance, but for the homeowner, it is a vital safeguard. If you die, a life insurance payout can allow your family to pay off the mortgage entirely, ensuring they have a secure, permanent place to live.
In 2026, with property values and interest rates remaining significant factors in household wealth, "mortgage protection" is a common use for term life insurance. By matching the term of your life insurance policy to the length of your mortgage (e.g., a 30-year term for a 30-year mortgage), you ensure that the debt is covered for the entire duration of the loan.
Beyond Family: Business and Professional Needs
For entrepreneurs and business owners, the need for life insurance extends into the professional realm. Your business is likely one of your most valuable assets, but it can also be a liability for your heirs if not protected correctly.
Key Person Insurance and Partnership Protections
If your business relies heavily on your specific skills, reputation, or technical expertise, the company itself may need to own a life insurance policy on you. This is known as "Key Person Insurance." If you pass away, the business receives a tax-free death benefit that can be used to hire a replacement, pay off business debts, or provide a buffer while the company reorganizes.
Furthermore, if you have business partners, life insurance is essential for "Buy-Sell Agreements." These legal contracts specify what happens to your share of the business if you die. Usually, the insurance payout provides the surviving partners with the funds to buy your shares from your heirs at a fair market value. This prevents your grieving family from having to run a business they may not understand, and it prevents the surviving partners from having to work with an accidental co-owner.
Protecting Aging Parents and Extended Family
The "sandwich generation"—those caring for both children and aging parents—faces unique insurance needs in 2026. If you provide financial support or physical care for an elderly parent, your death would leave them vulnerable. Life insurance can be structured to provide a fund for a parent's long-term care or to pay for a professional caregiver in your absence. This ensures that the standard of care you provide is maintained even if you are no longer there to facilitate it.
Why "Later" is Usually More Expensive: The Cost of Waiting
A common mistake is waiting until a health scare or a specific age to purchase life insurance. In the insurance industry, your "insurability" is at its peak when you are young and healthy.
The Mathematics of Age and Health
Insurance companies determine premiums based on mortality risk. Every year you age, the statistical likelihood of death increases, and premiums rise accordingly. More importantly, health conditions that develop over time—such as high blood pressure, diabetes, or high cholesterol—can lead to "rated" policies with much higher premiums, or even a total denial of coverage.
By getting life insurance when you first need it (or even slightly before), you lock in rates that can remain level for 10, 20, or 30 years. In 2026, many insurers utilize "accelerated underwriting," which uses data algorithms to approve healthy applicants in minutes. Waiting until you have a medical history makes this process longer, more intrusive, and significantly more expensive.
Evaluating Your Current Situation: A Comparison of Needs
Not everyone needs the same type of coverage at the same time. The following table outlines how life insurance needs typically shift across different demographics and life stages.
| Life Stage | Primary Insurance Goal | Recommended Policy Type | Priority Level |
|---|---|---|---|
| Young Professional (Single) | Debt (Student loans) / Funeral costs | Term Life (Small amount) | Low |
| Newly Married | Income replacement / Shared debt | Term Life (10-20 years) | Moderate |
| New Parents | Child support / Education / Mortgage | Term Life (20-30 years) | High |
| Established Business Owner | Business continuity / Buy-Sell funds | Key Person / Permanent Life | High |
| Empty Nesters | Estate taxes / Inheritance / Final expenses | Whole or Universal Life | Moderate |
| Retirees | Final expenses / Wealth transfer | Final Expense / Whole Life | Low to Moderate |
Common Misconceptions About Timing
Many people delay getting life insurance due to misconceptions about what they already have or what they can afford.
1. "I have coverage through my employer." While group life insurance is a great benefit, it is rarely enough. Most employer-provided policies offer only one or two times your annual salary. For a family with a mortgage and children, this is woefully inadequate. Furthermore, these policies are usually not portable; if you leave your job or the company downsizes, you lose your coverage exactly when you might be most vulnerable.
2. "I should wait until I have a higher income." Waiting for a higher salary often means waiting until you are older. The money you save by starting a policy at age 25 versus age 35 can amount to tens of thousands of dollars over the life of the policy. It is better to start with a smaller, affordable policy and add more coverage later than to have no coverage at all.
3. "Stay-at-home parents don't need insurance." This is a dangerous myth. While a stay-at-home parent doesn't bring in a traditional paycheck, the services they provide (childcare, transportation, cooking, home maintenance) have a massive market value. If that parent passes away, the surviving spouse would have to pay significantly for those services. Insuring a stay-at-home parent is essential for the economic stability of the household.
Frequently Asked Questions
Is there a specific age when life insurance becomes too expensive?
There is no "cutoff" age, but premiums generally see a significant jump every five years (at ages 30, 35, 40, etc.). By age 50 or 60, term insurance becomes considerably more expensive, and permanent insurance premiums can be prohibitive unless you are in excellent health. Most financial advisors suggest securing your primary coverage before age 45.
What is the "DIME" formula for deciding when I have enough?
The DIME formula is a standard tool used by the Financial Industry Regulatory Authority (FINRA) and other bodies to help individuals calculate their needs. It stands for Debt (total of all loans), Income (salary multiplied by the years your family needs support), Mortgage (remaining balance), and Education (estimated college costs for children). When your current assets cannot cover the total of these four categories, you need life insurance.
Can I get life insurance if I am already sick?
Yes, but the options are different. You may be eligible for "Guaranteed Issue" or "Simplified Issue" policies that do not require a medical exam. These policies have lower coverage limits and higher premiums, but they ensure that those with chronic conditions can still provide for final expenses or small debts.
Do I need life insurance if I am retired?
It depends on your estate. If your home is paid off, your children are independent, and your spouse is well-provided for by pensions or Social Security, you may not need it. However, many retirees use life insurance as a tax-advantaged way to leave an inheritance or to cover the costs of estate taxes and funeral expenses.
How does 2026 technology affect when I should apply?
In 2026, "fluidless" underwriting is the norm. Insurers use your digital health records, pharmacy history, and even data from wearable fitness devices to assess risk. This means healthy individuals can get covered almost instantly. If you are currently in a period of peak health and activity, now is the ideal time to apply and capitalize on these data-driven discounts.
Practical Recommendation: Your Next Steps
If you have identified that you fall into one of the "high-priority" categories—such as being a new parent or a homeowner—the next step is to conduct a formal needs analysis. Do not guess your coverage amount. Use the DIME formula or consult with a financial planner to determine the exact gap between your survivors’ needs and your current assets.
Start by getting quotes for Term Life Insurance. For the majority of people in 2026, term life offers the most significant amount of protection for the lowest cost, allowing you to cover your most vulnerable years without overextending your monthly budget. Once your baseline protection is in place, you can then explore permanent options for long-term wealth transfer or business needs.
Image Gallery
Select an image to open it in a new tab.


Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
