Dave Ramsey recommends purchasing a term life insurance policy with a death benefit equal to 10 to 12 times your annual gross income. He specifies that this should be a level-premium term policy lasting for a duration of 15 or 20 years, designed strictly to provide financial protection for your family rather than acting as a savings or investment vehicle.
Financial expert Dave Ramsey has built a decades-long career on the principle of simplicity in personal finance. When it comes to life insurance, his advice remains one of the most consistent pillars of his "Baby Steps" program. In 2026, despite shifts in the economic landscape and the evolution of digital insurance products, the core philosophy behind his recommendation remains rooted in the concept of "Buying Term and Investing the Difference" (BTID). This strategy focuses on obtaining the maximum amount of protection for the lowest possible cost, allowing individuals to redirect their remaining capital toward debt elimination and wealth building.
The 10–12x Rule: Calculating Your Coverage
The cornerstone of the Ramsey philosophy is the "10 to 12 times" multiplier. This isn't an arbitrary figure; it is based on the math of income replacement. The goal is to create a "pile of money" (the death benefit) that, if invested wisely by the surviving family members, can generate enough annual growth to replace the lost income of the deceased indefinitely.
Why 10 to 12 Times?
Ramsey argues that if a survivor receives a death benefit equal to 10–12 times the annual salary of the deceased and invests that money in a series of good growth-stock mutual funds, they can reasonably expect an annual return that covers their living expenses. For example, if a spouse earns $100,000 a year, a $1.2 million policy invested at a 10% average annual return would yield approximately $120,000 a year. Even after accounting for inflation and taxes, this provides a significant safety net that allows the family to maintain their standard of living without depleting the principal amount.
Using Gross Income, Not Net
A common point of confusion is whether to calculate the coverage based on "take-home pay" or "gross income." Ramsey advises using the gross annual income (before taxes). This ensures that the death benefit is robust enough to cover not just basic bills, but also the future tax liabilities of the investment gains and the rising costs of lifestyle needs, such as healthcare and education.
Why Ramsey Only Recommends Term Life Insurance
In the world of insurance, there are two primary categories: term life and "permanent" life insurance (which includes whole life, universal life, and variable life). Dave Ramsey is famously opposed to any form of permanent or "cash value" life insurance.
The Problem with Whole Life Insurance
Ramsey refers to whole life insurance as one of the "worst financial products on the market." His critique centers on three main issues:
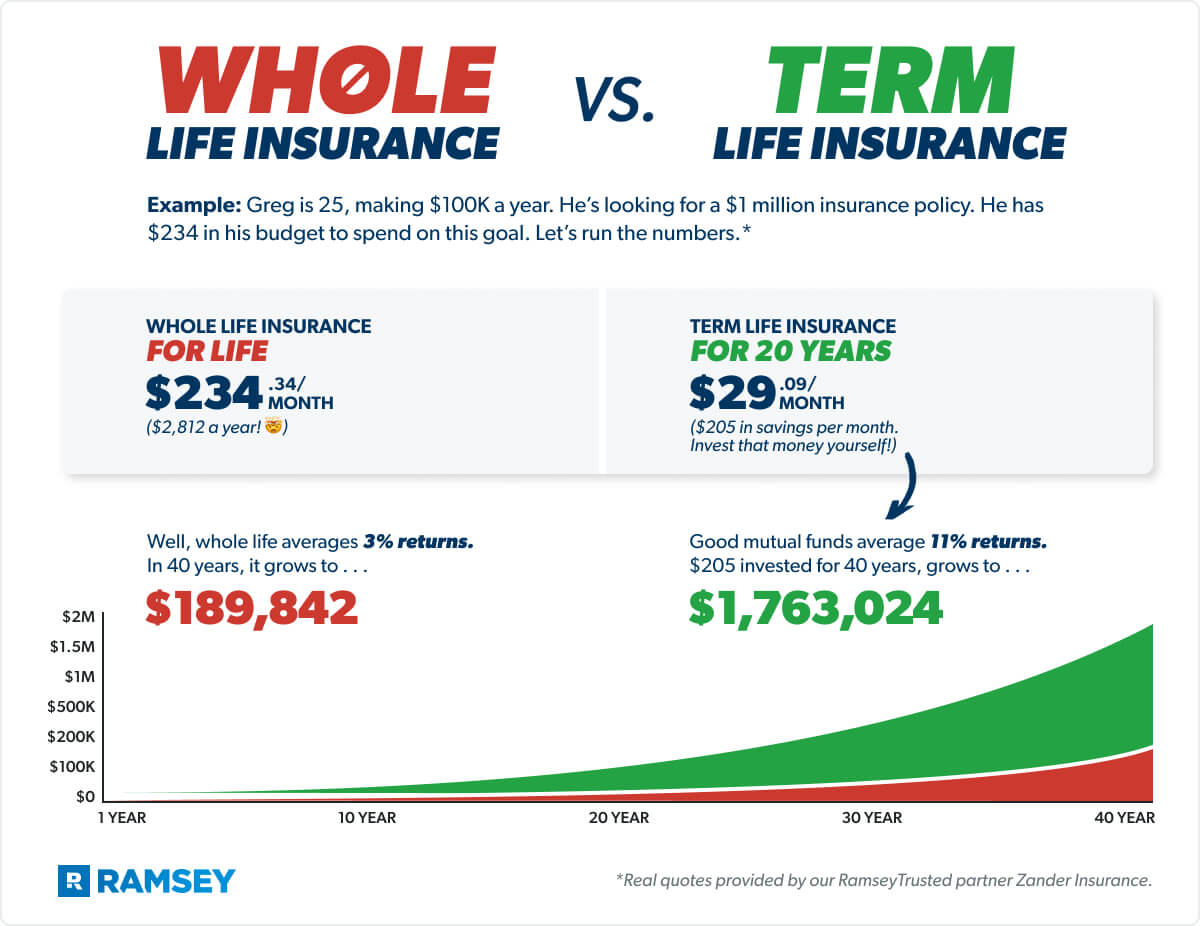
- Cost: Whole life premiums can be 20 times more expensive than term life premiums for the same amount of coverage.
- Low Returns: The cash-value component typically grows at a much lower rate than a standard mutual fund or the S&P 500.
- Fees: High administrative fees and agent commissions eat into the "investment" portion of the policy in the early years.
The "Buy Term and Invest the Difference" Strategy
By opting for a term policy—which provides coverage for a specific period (the "term") and has no cash value—a consumer saves a significant amount in monthly premiums. Ramsey’s advice is to take those savings and invest them into a Roth IRA or a 401(k). By 2026 standards, the transparency of low-cost brokerage accounts makes this strategy even more accessible than it was when Ramsey first began teaching it. The term policy provides protection while you are building wealth; once you have significant assets and no debt, the insurance becomes unnecessary.

Choosing the Right Term Length: 15 vs. 20 Years
The "term" in term life insurance refers to how long the policy remains active. Ramsey typically suggests a 15-year or 20-year level term policy. A "level term" means your premium stays exactly the same for the entire duration of the policy.
The 15-Year Term
This is often recommended for individuals who are already well into their career or are aggressively following the Baby Steps. The logic is that within 15 years, a person following the Ramsey plan should have their home paid off and their retirement accounts fully funded, rendering them "self-insured."
The 20-Year Term
This is the standard recommendation for younger families. If you have young children, you want a term that lasts at least until they are through college and out of the house. A 20-year term provides that window of protection during the family's most vulnerable financial years—when the mortgage is high and the children are dependent.
Why Not a 30-Year Term?
While some advisors suggest 30-year terms, Ramsey often steers people toward 15 or 20 years to encourage the urgency of becoming self-insured. However, if a 30-year term provides peace of mind for a family with a newborn and a 30-year mortgage, it is still a far better choice than any whole life policy.
The Goal of Becoming Self-Insured
The ultimate objective of the Ramsey financial plan is to reach a point where you no longer need life insurance. This state is known as being self-insured.
According to the Ramsey Solutions philosophy, you are self-insured when:
- You have zero debt (including the mortgage).
- Your children are grown and financially independent.
- Your retirement nest egg is large enough that its growth can support your surviving spouse indefinitely.
If you follow the "Baby Steps"—saving an emergency fund, paying off all debt, and investing 15% of your income—you should theoretically reach this point by the time your 20-year term policy expires. At that stage, paying premiums for a death benefit is a waste of money because your actual net worth provides the necessary "death benefit" to your heirs.
Coverage Recommendations by Income Level
To visualize the Ramsey 10–12x rule, consider the following table which breaks down recommended coverage amounts based on various annual gross income levels.
| Gross Annual Income | 10x Coverage (Minimum) | 12x Coverage (Recommended) | Estimated Monthly Term Cost* |
|---|---|---|---|
| $40,000 | $400,000 | $480,000 | $20 - $35 |
| $60,000 | $600,000 | $720,000 | $25 - $45 |
| $80,000 | $800,000 | $960,000 | $35 - $60 |
| $100,000 | $1,000,000 | $1,200,000 | $45 - $80 |
| $150,000 | $1,500,000 | $1,800,000 | $70 - $120 |
| $200,000 | $2,000,000 | $2,400,000 | $90 - $160 |
*Estimates are for a healthy 35-year-old in 2026. Actual rates vary significantly based on age, health status, and tobacco use.
Special Considerations: Spouses and Stay-at-Home Parents
A common mistake in life insurance planning is only insuring the primary "breadwinner." Dave Ramsey emphasizes that both spouses need coverage, regardless of who brings home a paycheck.
Insuring the Stay-at-Home Parent
If a stay-at-home parent passes away, the surviving spouse will face significant new expenses, including full-time childcare, housekeeping, and transportation logistics. Ramsey suggests that a stay-at-home parent should carry approximately $250,000 to $400,000 in term life insurance coverage. This amount provides a cushion to cover those services for several years, allowing the surviving parent to focus on the family’s emotional transition without immediate financial strain.
Working Spouses
If both spouses work, both should follow the 10–12x rule independently. If one spouse earns $50,000 and the other earns $100,000, the first should have $500,000–$600,000 in coverage, and the second should have $1 million–$1.2 million.
When to Buy Life Insurance in the "Baby Steps"
In the Ramsey timeline, life insurance is not something you wait to buy until you are debt-free. It is considered a fundamental "defensive" necessity.
- Baby Step 0/1: You should have your term life insurance in place as soon as you decide to get your finances in order. You do not want to be in the middle of "Baby Step 2" (paying off debt) and have a tragedy occur without protection.
- Medical Exams: Because term life insurance requires underwriting, Ramsey suggests applying sooner rather than later. Your health is your greatest asset in securing low premiums; waiting until you are older or develop health issues can make the 10–12x coverage prohibitively expensive.
Common Life Insurance Gimmicks to Avoid
In addition to his stance against whole life insurance, Ramsey warns against several other common industry "riders" or policy types that he deems unnecessary:
- Accidental Death and Dismemberment (AD&D): Ramsey calls this a "gimmick." If you have 10–12x your income in term life, your family is protected regardless of how you die. You don't need extra coverage just because the death was an accident.
- Credit Life Insurance: This pays off a specific debt (like a mortgage or car loan) if you die. It is much more expensive than standard term life. A simple term policy covers all your needs, including your debts.
- Child Life Insurance: Ramsey argues that children do not have an income to replace. While a small rider for funeral expenses is acceptable to some, he generally advises against buying policies for children. Instead, invest that money for their college or future.
- Return of Premium (ROP) Riders: These riders promise to give you your premiums back if you outlive the term. However, they significantly increase the monthly cost. Ramsey suggests you are better off keeping the cash and investing it yourself.
FAQ: Dave Ramsey's Term Life Recommendations
Should I cancel my whole life policy immediately?
You should never cancel an existing life insurance policy until your new term life policy is fully in force. Once you have received your new term policy documents and confirmed the coverage has begun, you can then move to cash out your whole life policy. Ramsey suggests using the surrendered cash value to jumpstart your emergency fund or pay down debt in Baby Step 2.
What if I have a medical condition and cannot get term life?
If you are uninsurable due to a chronic or terminal illness, Ramsey suggests looking for "guaranteed issue" policies or maximizing any group life insurance offered through your employer. While employer-provided insurance is usually insufficient (often only 1x or 2x salary), it is better than nothing if you cannot qualify for an individual policy.
Does Dave Ramsey recommend specific companies?
For many years, Dave Ramsey has endorsed Zander Insurance, an independent brokerage that shops various carriers to find the lowest rates. His recommendation is less about a specific carrier and more about finding an independent agent who can compare "Level Term" policies from many highly-rated companies (rated A or A+ by A.M. Best).
Is 10–12x income still enough with 2026 inflation?
Yes, because the recommendation is a multiplier. As your income rises with inflation or career growth, the amount of insurance you need rises proportionally. If inflation causes your salary to jump from $60,000 to $80,000, you simply update your coverage to reflect the new 10–12x requirement.
Can I have multiple term policies?
Yes. This is often called "laddering," though Ramsey typically keeps his advice simple: one solid 15- or 20-year policy. However, if you already have a $500,000 policy and your income increases, you can simply buy a second "layer" of $500,000 term insurance to meet the 10–12x goal.
Practical Next Steps for Coverage
To align with the Dave Ramsey suggested amounts, your first step is to calculate your "Protection Gap." Total your annual gross income and multiply it by 12. Subtract any current term life insurance you have that is not tied to your employer. The resulting number is the amount of new coverage you likely need.
Once you have determined the amount, contact an independent insurance broker to get quotes for a 15- or 20-year level term policy. Ensure the company is highly rated (A or better) for financial stability. Do not let an agent talk you into "flexible" premiums or "investment components." Stick to the simple, low-cost term insurance that protects your family while you focus on building a legacy of wealth.
Image Gallery
Select an image to open it in a new tab.
Mateo Castillo
Decentralized Finance and E-Payments Strategist
