
Life insurance is worth it for most Riverside residents who have financial dependents, outstanding debt, or a mortgage. In 2026, with the Inland Empire’s cost of living and housing prices remaining high, a policy provides a critical safety net that ensures your family can remain in their home and maintain their lifestyle if a primary earner passes away.
The Financial Reality of Living in Riverside in 2026
To determine if life insurance is worth the monthly premium, one must first look at the economic landscape of Riverside and the broader Inland Empire. As of 2026, Riverside has transitioned from a traditionally "affordable" alternative to Los Angeles into a robust metropolitan area with its own significant cost of living challenges.
For many families in neighborhoods like Canyon Crest, Orangecrest, or Woodcrest, the primary financial burden is the mortgage. While interest rates and market fluctuations vary, the median home price in Riverside remains substantial. If a household relies on two incomes to cover a mortgage, the loss of one partner can lead to immediate housing instability. Life insurance acts as a "mortgage protection" tool, ensuring that the death benefit can wipe out the remaining debt, allowing the surviving family members to stay in their community and schools.
Beyond housing, Riverside residents face California-specific inflationary pressures. From utility costs under Southern California Edison to the general cost of goods, the "safety margin" for families has narrowed. Life insurance provides the liquidity necessary to cover not just immediate final expenses—which can exceed $15,000 for a standard funeral and burial in California—but also the long-term loss of income that would have otherwise funded college tuition at local institutions like UC Riverside or California Baptist University.
Types of Life Insurance Policies Available in Riverside
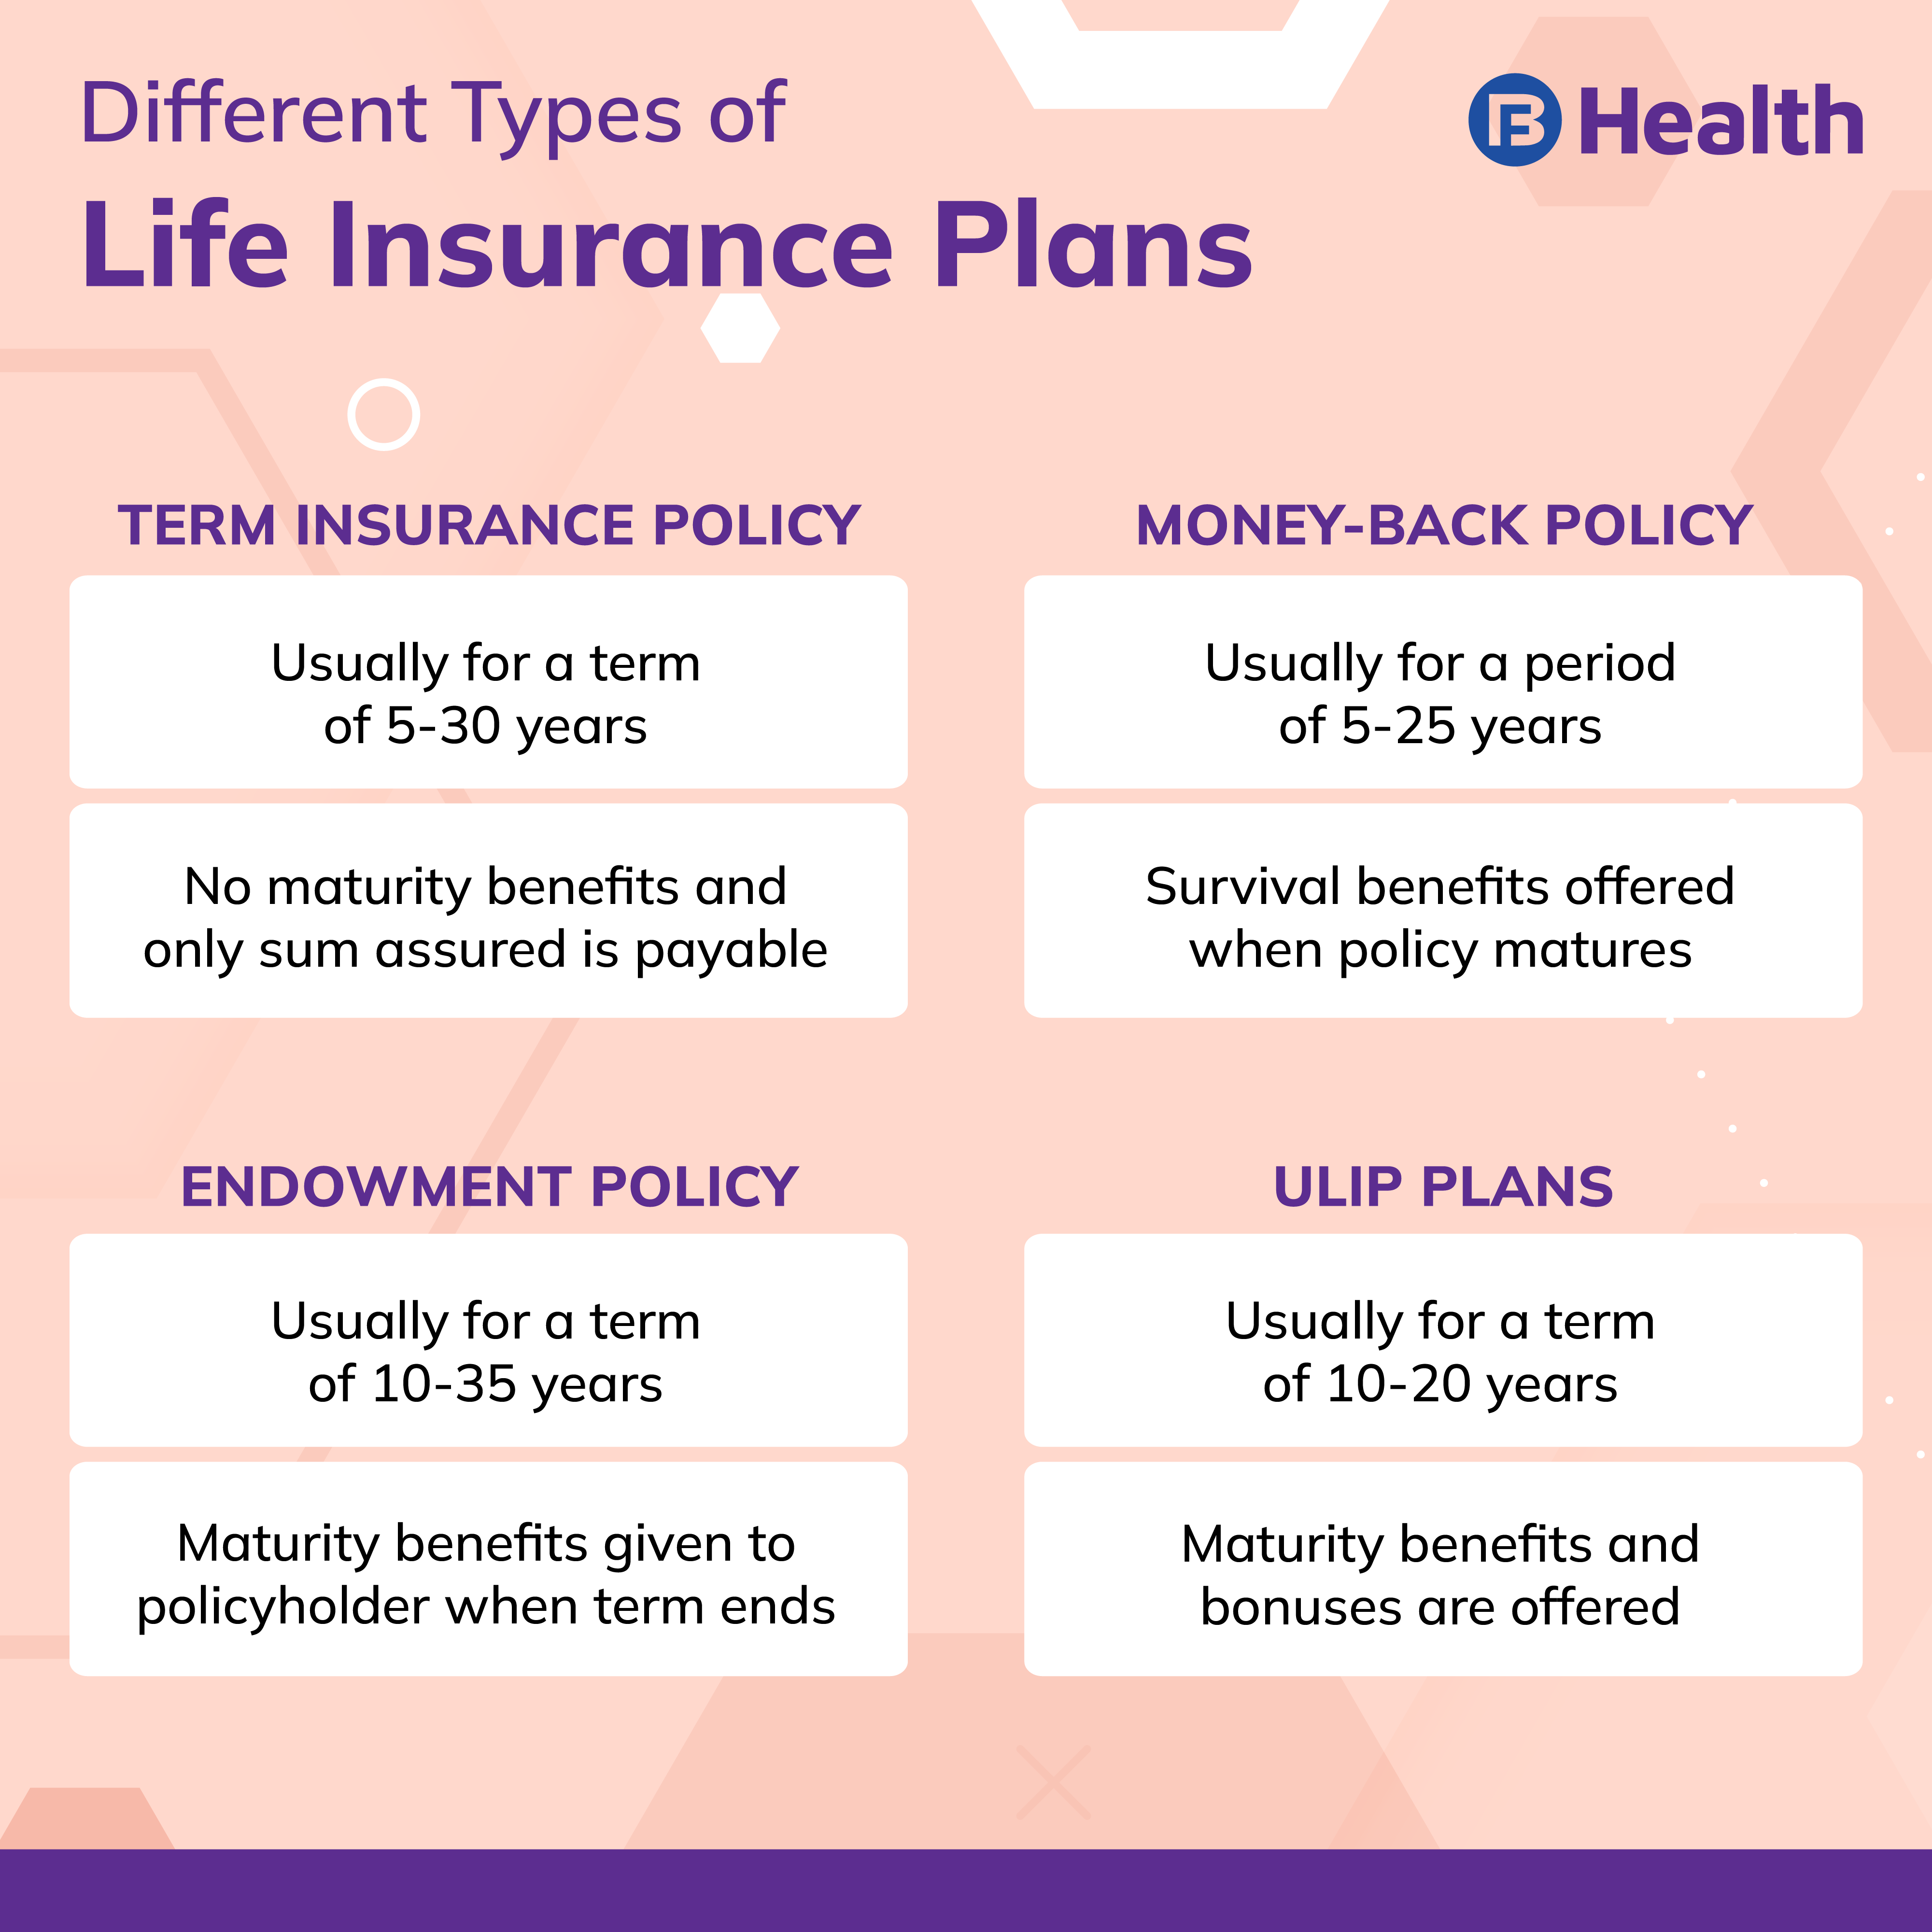
Understanding whether life insurance is "worth it" requires a look at the specific products available. Not every policy fits every budget or goal. In 2026, the market is primarily split between temporary protection and permanent financial vehicles.
Term Life Insurance: Pure Protection
Term life insurance is often cited as the most cost-effective option for Riverside families. It provides coverage for a specific period, typically 10, 20, or 30 years.
- Why it’s worth it: It is the least expensive way to secure a large death benefit. For a healthy 35-year-old in Riverside, a $500,000 policy might cost less than a monthly dinner out in downtown Riverside.
- Best for: Young families, those with 30-year mortgages, and individuals looking to cover their peak earning years.
Whole Life Insurance: Permanent Coverage and Cash Value
Whole life insurance stays in effect for your entire life, provided premiums are paid. It also includes a "cash value" component that grows over time.
- Why it’s worth it: It offers a guaranteed death benefit and a tax-advantaged savings element. In the 2026 financial climate, some residents use the cash value as a source of emergency funds or as part of a diversified retirement strategy.
- Best for: High-net-worth individuals, estate planning, and those who want lifelong coverage regardless of when they pass.
Universal Life (UL) and Indexed Universal Life (IUL)
These policies offer more flexibility than whole life, allowing policyholders to adjust their premiums and death benefits. IULs link the cash value growth to a market index, such as the S&P 500.
- Why it’s worth it: It provides a middle ground between the rigidity of whole life and the temporary nature of term life.
- Best for: Those who want permanent coverage but need the flexibility to change their payment structures as their Riverside-based businesses or careers evolve.
California-Specific Regulations and Protections
Residents of Riverside benefit from some of the strongest consumer protection laws in the United States, governed by the California Department of Insurance (CDI). These regulations add to the "value" of a policy by ensuring transparency and fairness.
The 30-Day Grace Period
In California, life insurance companies must provide a 30-day grace period for late premium payments. This means if you miss a payment due to a temporary financial hiccup, your coverage does not immediately vanish. This protection is vital for maintaining the "worth" of your investment during lean months.
The "Free Look" Period
California law generally mandates a "free look" period (often between 10 and 30 days, depending on the age of the applicant and the policy type). During this time, a Riverside resident can review the policy documents and cancel for a full refund if they decide the coverage isn't right for them. This minimizes the risk of "buyer's remorse."
The California Life and Health Insurance Guarantee Association (CLHIGA)
If an insurance company becomes insolvent, CLHIGA provides a safety net for California residents. While there are limits to the coverage (generally up to $300,000 for life insurance death benefits), this adds a layer of security to your purchase, ensuring that the promise of protection is backed by state-mandated safeguards.
Calculating the "Worth": Cost vs. Benefit in 2026
When evaluating if life insurance is worth it, you must compare the cost of premiums against the potential financial catastrophe of being uninsured.
| Feature | Term Life Insurance | Whole Life Insurance | Indexed Universal Life |
|---|---|---|---|
| Average Monthly Cost | Low ($20–$60) | High ($200–$600+) | Moderate ($100–$300) |
| Coverage Duration | Fixed (e.g., 20 years) | Lifetime | Lifetime (Flexible) |
| Cash Value Growth | None | Guaranteed Fixed Rate | Linked to Market Index |
| Policy Loans | No | Yes | Yes |
| Best Use Case | Mortgage/Child Rearing | Estate Tax/Legacy | Wealth Accumulation |
Note: Costs are estimates based on a healthy 35-year-old non-smoker in Riverside, CA. Actual rates depend on individual underwriting.
The Opportunity Cost of No Coverage
If a 40-year-old breadwinner in Riverside passes away without insurance, the surviving family may be forced to:
- Sell the home quickly: Potentially losing equity in a forced sale.
- Relocate: Moving to a lower-cost area, which may be far from support networks and jobs.
- Incur Debt: Using high-interest credit cards or personal loans to cover funeral costs and immediate bills.
When viewed through this lens, the "worth" of life insurance is not just the death benefit; it is the prevention of a total financial collapse.
Common Factors Influencing Your Premium in Riverside
Your specific location in Riverside doesn't directly change your life insurance rates the way it might for auto or home insurance (which account for local traffic or fire risks). However, your lifestyle within the region does.
- Health and Wellness: Riverside has a variety of outdoor spaces, from Mount Rubidoux to the Santa Ana River Trail. Staying active and maintaining a healthy BMI can significantly lower your premiums. In 2026, many insurers offer "accelerated underwriting" or discounts for policyholders who use wearable devices to track fitness.
- Occupational Hazards: Riverside’s economy is heavily involved in logistics, healthcare, and education. While most of these roles are considered "standard risk," those working in more hazardous construction or industrial roles near the Jurupa Valley border may see slight adjustments in their ratings.
- Tobacco Use: This remains the single largest controllable factor. In California, smokers can pay 2x to 4x more than non-smokers for the same coverage.
The Role of Living Benefits in 2026
A major shift in the "is it worth it" debate for 2026 is the prevalence of Living Benefits. Modern policies often include riders that allow the policyholder to access a portion of the death benefit while they are still alive if they are diagnosed with a terminal, chronic, or critical illness.
For a Riverside resident, this means if you suffer a major heart attack or stroke and are treated at a facility like Riverside Community Hospital or Kaiser Permanente, your life insurance policy could provide a lump sum to help pay for out-of-pocket medical expenses or home modifications. This transforms life insurance from a "death-only" benefit into a versatile tool for financial survival during a health crisis.
Strategic Considerations for Different Life Stages
For Young Families in the Inland Empire
If you are just starting out, term life is almost always worth it. The goal here is "income replacement." If you make $75,000 a year, a $750,000 policy provides a 10-year buffer for your spouse and children. In the 2026 economy, this is a baseline requirement for responsible financial planning.
For Seniors and Retirees in Riverside
As you age, the "worth" of life insurance shifts toward final expense coverage and estate planning. Many seniors in Riverside use "Final Expense" or "Burial Insurance" to ensure their children aren't burdened with the $10,000+ cost of a local service. Additionally, if you have a significant estate that will be subject to California's complex probate process, life insurance provides immediate liquidity to pay taxes and legal fees without liquidating property.
For Business Owners
Riverside is home to thousands of small businesses. Life insurance is "worth it" here for Buy-Sell Agreements. If a business partner dies, the insurance policy provides the funds for the surviving partner to buy out the deceased partner's heirs, ensuring the business remains operational and the heirs receive a fair price.
FAQ
Is life insurance mandatory in California?
No, life insurance is not legally mandated for individuals in California. However, lenders may occasionally require a life insurance policy (often called credit life insurance) as a condition for certain high-value business loans. For personal mortgages, it is highly recommended but not required by law.
How much life insurance do I need for a home in Riverside?
A common rule of thumb is to carry enough coverage to pay off your mortgage entirely, plus 5–10 times your annual salary. If your Riverside home has a $550,000 balance and you earn $80,000, a policy of $1 million to $1.2 million would be a robust target for 2026.
Can I change my policy if I move out of Riverside?
Yes. Life insurance policies are portable. If you move to another city in California or another state entirely, your coverage remains in effect as long as you continue to pay your premiums. You should, however, update your address with the insurer to ensure you receive important notices.
Does California tax life insurance death benefits?
Generally, no. Life insurance death benefits are usually paid out to beneficiaries free of federal and state income tax. This tax-free status is one of the primary reasons life insurance is considered such a high-value financial tool in California’s high-tax environment.
What happens if I outlive my term life policy?
If you have a standard term policy and reach the end of the 10, 20, or 30-year period, the coverage simply expires. Some policies offer a "Return of Premium" rider (which costs more) that refunds your payments if you outlive the term, or a "Conversion Rider" that allows you to turn the term policy into a permanent one without a new medical exam.
Final Recommendation: Next Steps for Riverside Residents
Deciding that life insurance is "worth it" is only the first step. To ensure you are getting the best value in 2026, follow these practical actions:
- Audit Your Debt: Total your mortgage, car loans, and student debt. This is your "floor" for coverage.
- Check Employer Coverage: Many Riverside employers offer a basic life insurance policy (often 1x your salary). While helpful, this is rarely enough and usually ends if you leave the job.
- Get a Medical Check-up: Since rates are based on health, knowing your current blood pressure and cholesterol levels will help you get accurate quotes.
- Consult a Local Professional: While online quotes are a great starting point, speaking with an independent agent who understands California’s specific policy riders can help you find a plan that includes the "living benefits" most relevant to your lifestyle.
By securing coverage now, you are locking in a rate based on your current age and health, ensuring that no matter how the Riverside economy shifts over the next decade, your family’s financial foundation remains secure.
Image Gallery
Select an image to open it in a new tab.

Lars Thomsen
Global Labor Markets and Economic Strategy Editor
