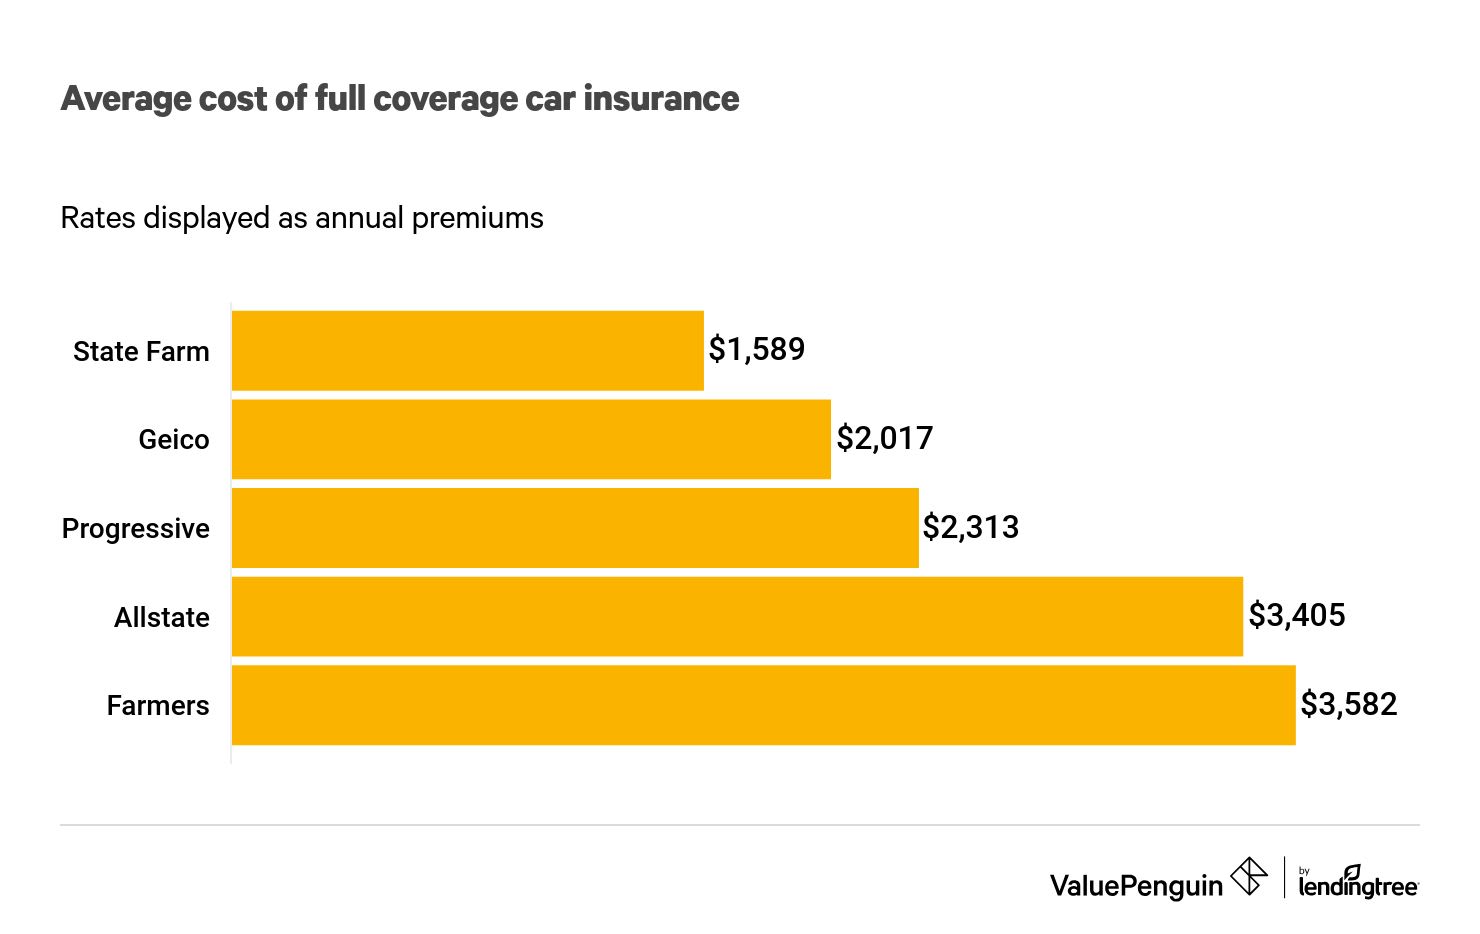
The cost of GEICO car insurance is determined by a complex interplay of personal risk factors, vehicle specifications, and state-mandated coverage requirements. Because premiums are calculated based on individual actuarial data, there is no single fixed rate; instead, costs fluctuate significantly based on your driving history, location, age, and the specific policy limits you select to protect your financial interests.
How GEICO Determines Your Insurance Premium
GEICO, like most major insurers, uses a sophisticated underwriting process to assess risk. The fundamental goal of this process is to predict the likelihood of you filing a claim and the potential severity of that claim. When you request a quote, the company aggregates data points to build a risk profile that dictates your specific rate.
Personal Driving History and Claims
Your history behind the wheel is arguably the most significant factor in your premium calculation. Drivers with a clean record—no accidents, moving violations, or claims—are classified as low-risk and generally receive the most competitive pricing. Conversely, tickets for speeding, at-fault accidents, or a history of multiple claims signal to the insurer that you represent a higher statistical probability of future loss, which leads to higher premiums.
Geographic Location and State Requirements
Where you park your car at night impacts your insurance cost. Insurance is regulated at the state level, meaning minimum liability limits, personal injury protection (PIP) requirements, and uninsured motorist coverage mandates vary drastically across the country. Additionally, GEICO analyzes localized data such as accident frequency, theft rates, and severe weather risks in your specific zip code. If you live in an area with high rates of vehicle vandalism or heavy traffic congestion, your premium will likely reflect the higher risk profile of that territory.
Driver Demographics
In many jurisdictions, age, marital status, and gender remain legal components of risk assessment. Younger, inexperienced drivers typically face the highest premiums due to statistically higher accident rates. As drivers gain experience, rates often decrease until senior age brackets, where premiums may rise again due to changes in reaction times and health considerations.
Vehicle Characteristics and Coverage Selections
The vehicle you choose to insure is as important as the person driving it. The cost to repair or replace your vehicle is a primary driver of the physical damage portions of your policy, specifically Comprehensive and Collision coverage.
- Vehicle Make and Model: High-performance vehicles or luxury cars often carry higher premiums because their parts are expensive, and specialized labor is required for repairs. Furthermore, vehicles with higher theft rates often result in higher Comprehensive premiums.
- Safety Features: Vehicles equipped with advanced driver-assistance systems (ADAS), such as automatic emergency braking or lane-keep assist, may qualify for certain discounts because these features can reduce the frequency of accidents.
- Coverage Limits and Deductibles: Choosing higher liability limits provides more financial protection in a catastrophic event, but it increases your base premium. Selecting a higher deductible—the amount you pay out-of-pocket before insurance kicks in—is one of the most effective ways to lower your monthly premium, as it shifts more of the initial risk onto the policyholder.
Comparing Coverage Options and Financial Protection
When evaluating the cost of GEICO car insurance, it is essential to distinguish between mandatory requirements and elective protections. Understanding the difference allows you to tailor a policy that balances affordability with adequate risk mitigation.
| Coverage Type | Purpose | Cost Impact |
|---|---|---|
| Bodily Injury Liability | Covers injuries to others you cause. | High |
| Property Damage Liability | Covers damage to other people's property. | Medium |
| Collision Coverage | Repairs your car after an accident. | Variable (Vehicle Value) |
| Comprehensive Coverage | Covers theft, fire, or weather damage. | Variable (Market Value) |
| Uninsured/Underinsured | Protects you from under-insured drivers. | Low to Moderate |
The Role of Deductibles in Premium Reduction
The relationship between your deductible and your premium is inverse. If you choose a $1,000 deductible rather than a $500 deductible, GEICO assumes less financial liability for small, frequent claims. This change results in a lower premium. Before selecting a high deductible, ensure you have sufficient personal savings to cover that amount if an accident occurs; otherwise, a high deductible could present a significant financial hardship during an emergency.
Available Discounts and Loyalty Programs
GEICO is well-known for its aggressive marketing of discounts, which can significantly lower the overall cost of coverage. It is common for policyholders to overlook these potential savings. To minimize your costs, investigate the following categories:
- Multi-Policy Discounts: Bundling your car insurance with homeowners, renters, or condo insurance is one of the most effective ways to reduce your total premium.
- Driver Safety Programs: Completing a defensive driving course or maintaining a "claims-free" status for a specific number of years often results in tiered discounts.
- Vehicle Equipment: Features like airbags, anti-lock brakes, and anti-theft systems are often automatically factored into your quote, but ensure your vehicle information is accurate to maximize these benefits.
- Affiliation and Professional Groups: GEICO offers specialized rates for members of various professional organizations, alumni associations, and federal employee groups. Always verify your current employment or association status during the quoting process.
Frequently Asked Questions
Why did my GEICO premium increase at renewal?
Premium increases at renewal can occur due to general inflationary trends in the auto repair industry, changes in your personal risk profile (such as a new ticket or claim), or changes in state-wide rate filings approved by your local insurance commissioner.
Does my credit score affect my GEICO insurance rate?
In states where it is permitted by law, insurance companies use credit-based insurance scores to predict the likelihood of a future claim. Generally, individuals with higher credit scores are viewed as lower risk, which can lead to lower premiums.
How can I get the lowest possible rate with GEICO?
The best way to secure a lower rate is to increase your deductible, bundle multiple insurance products (such as home and auto), maintain a clean driving record, and actively request a review of your policy to see if you qualify for newly available discounts.
Is GEICO always the cheapest insurance provider?
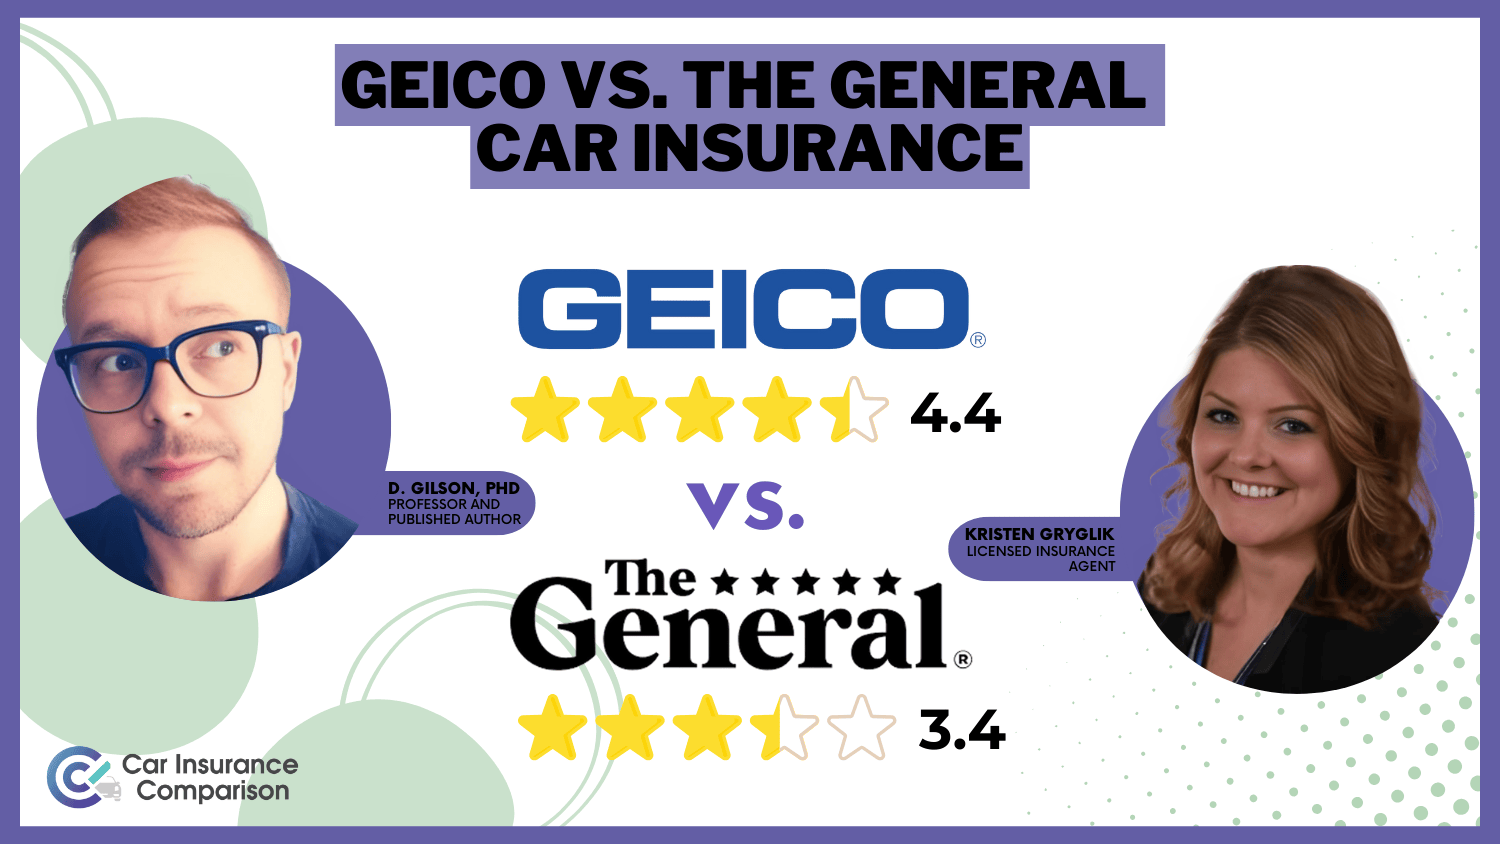
Insurance pricing is highly subjective and depends on your unique demographic and geographic factors. While GEICO is often cited for competitive pricing, it is not guaranteed to be the cheapest for every individual. Comparing multiple quotes is a standard best practice.
What should I do if I am unhappy with my current premium?
If you feel your premium is too high, contact a GEICO representative to review your policy. They can help you identify missing discounts, explain the impact of your current coverage limits, and discuss how adjusting your deductible might align your coverage with your current budget.
Next Steps for Managing Your Insurance Costs
Managing the cost of your GEICO car insurance is an ongoing process that requires proactive engagement. Start by reviewing your current policy declarations page to understand exactly what you are paying for—ensure you are not paying for "Full Coverage" on an older vehicle that may no longer justify the cost of Collision or Comprehensive protection.
If you have experienced significant life changes, such as a change in your daily commute distance, marriage, or moving to a different zip code, contact GEICO to update your profile. These changes frequently impact your risk assessment and could lead to immediate premium reductions. By regularly auditing your policy, leveraging available discounts, and maintaining a safe driving record, you ensure that you are paying the most accurate rate possible for your specific circumstances.
Image Gallery
Select an image to open it in a new tab.


Declan O'Connor
Higher Education and Campus Culture Reporter
