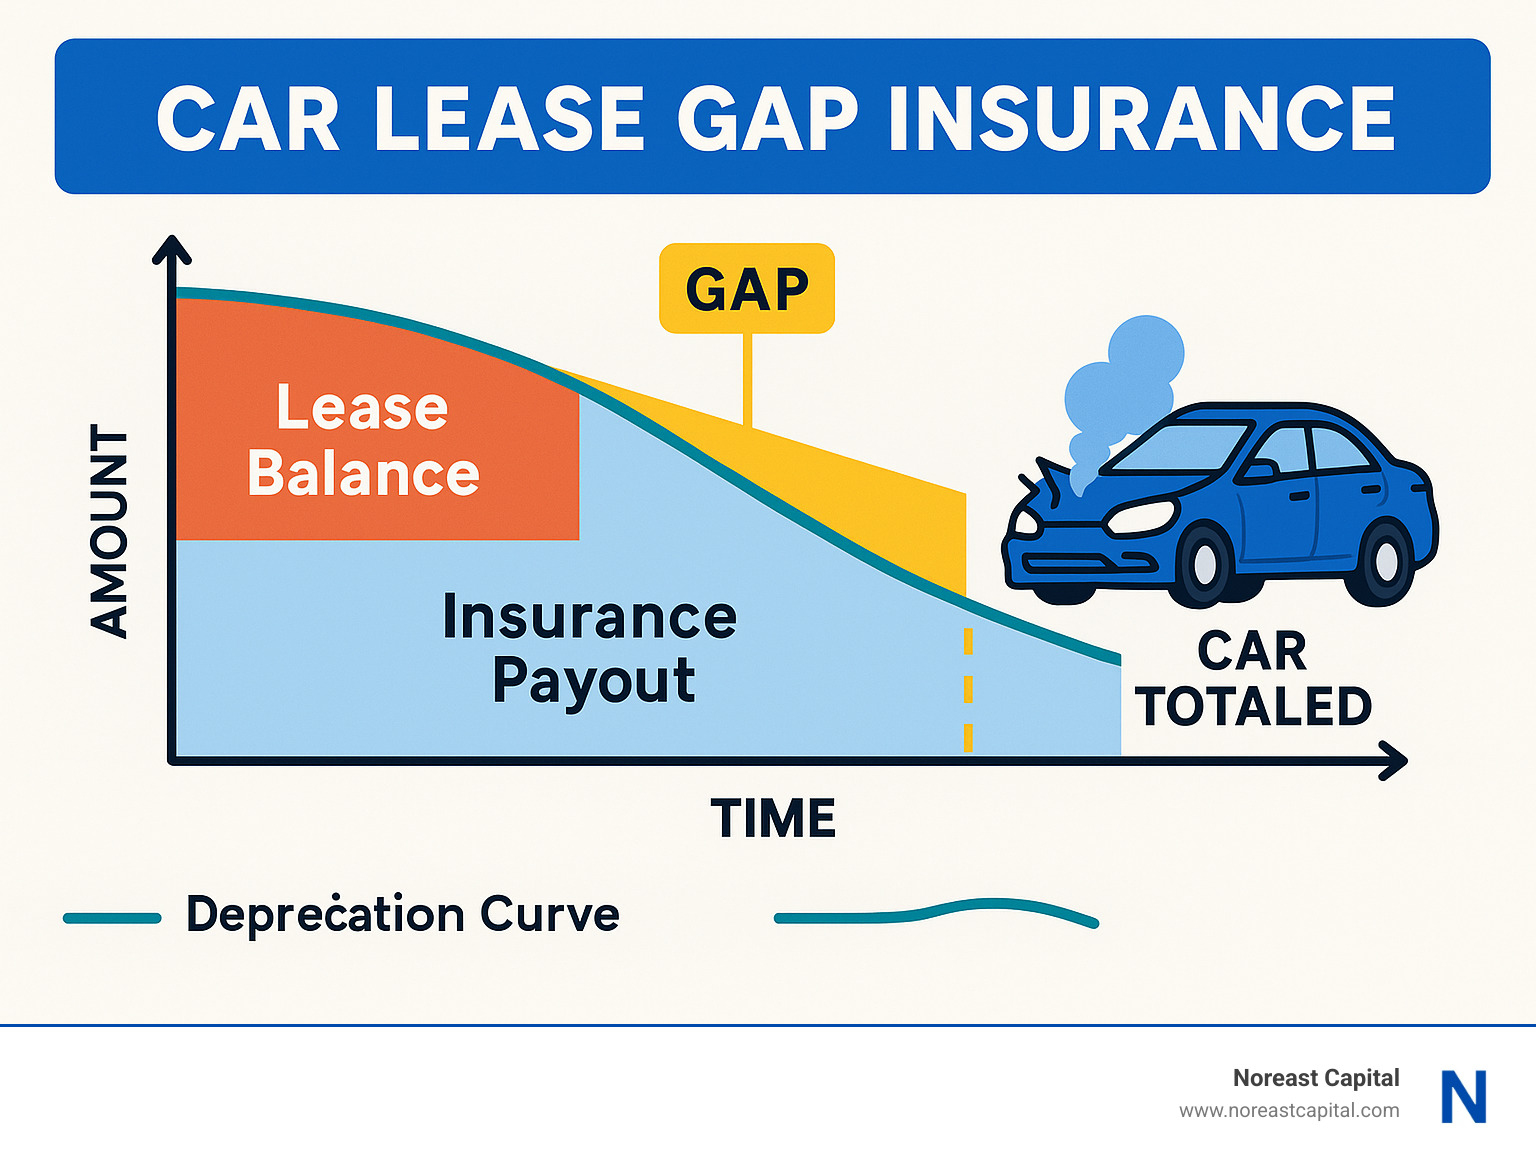
Insuring a leased vehicle typically costs more than insuring a car you own outright because leasing companies require higher liability limits and mandatory "full coverage," including collision and comprehensive protection. Additionally, most lessors mandate Gap insurance to cover the difference between the car’s depreciated value and your remaining lease balance in the event of a total loss.
The Fundamental Shift in Insurance Obligations for Leased Vehicles
When you lease a car, the fundamental relationship between the driver and the vehicle changes compared to traditional ownership. You are effectively renting the vehicle for a set period, typically 24 to 48 months. Because the leasing company (the lessor) remains the legal owner of the asset, they have a vested financial interest in ensuring that the vehicle is fully protected against physical damage and that any legal liabilities arising from its use are well-covered.
In 2026, the automotive market continues to see a high volume of sophisticated electric and hybrid vehicles being leased. These vehicles often carry higher repair costs due to specialized components like battery arrays and advanced driver-assistance systems (ADAS). Consequently, insurance companies and lessors have synchronized their requirements to mitigate the risks associated with these high-value assets. Understanding the cost of leased car insurance requires looking beyond the monthly premium and examining the specific coverage mandates that drive those prices upward.
The primary driver of increased costs is the transition from state-minimum coverage to lessor-mandated coverage. While a state might only require a small amount of bodily injury and property damage liability, a leasing company will almost certainly require significantly higher limits to protect their investment from lawsuits and physical destruction.
Mandatory Coverage Levels and Their Financial Impact
Leasing companies do not allow lessees to carry "liability only" insurance. They require a suite of coverages often referred to as "full coverage," though that term is more of a colloquialism than a technical insurance product. To understand the cost, one must break down the three primary pillars of a lease-compliant policy.
Higher Liability Limits
Most states require minimal liability coverage, often as low as $25,000 per person for bodily injury. However, most leasing contracts in 2026 stipulate limits of at least $100,000 per person and $300,000 per accident for bodily injury, along with $50,000 or $100,000 for property damage. This is often written as 100/300/50.
The reason for this is simple: if you are involved in a catastrophic accident, the leasing company could potentially be named in a lawsuit as the owner of the vehicle. Higher liability limits protect both you and the lessor. Increasing your coverage from state minimums to these higher tiers can increase your premium by 20% to 40%, depending on your driving history and location.
Collision and Comprehensive Coverage
Collision insurance covers damage to your vehicle resulting from an accident with another car or an object. Comprehensive insurance covers non-collision events, such as theft, vandalism, fire, or natural disasters. For a leased car, these are non-negotiable.
The cost of these coverages is directly tied to the "Actual Cash Value" (ACV) of the vehicle. In 2026, as vehicle prices have stabilized but remain high, the cost to repair or replace a car is significant. Furthermore, lessors usually cap the maximum deductible you can choose—typically at $500 or $1,000. While a $2,500 deductible would lower your monthly premium, most leasing companies forbid it because it increases the risk that a lessee won't be able to afford the repairs after an accident, leaving the lessor with a damaged asset.
The Critical Role of Gap Insurance in 2026
One of the most specific components of leased car insurance costs is Guaranteed Asset Protection, commonly known as Gap insurance. Vehicles depreciate the moment they are driven off the lot. In a lease, you are essentially paying for that depreciation over time. However, if the car is stolen or totaled in the first year, the insurance company will only pay the Actual Cash Value. This amount is often significantly less than what you still owe on the lease agreement.
Without Gap insurance, you would be legally responsible for paying the "gap" between the insurance payout and the lease payoff amount out of your own pocket.
| Feature | Standard Full Coverage | Gap Insurance |
|---|---|---|
| Primary Goal | Covers vehicle repair or replacement up to market value. | Covers the difference between market value and lease balance. |
| Required by Lessor? | Always. | Usually (often bundled into the lease). |
| Payout Basis | Actual Cash Value (ACV). | Remaining lease payoff balance. |
| Cost Influence | Based on driver risk and car value. | Usually a flat fee or small percentage of premium. |
Many modern lease agreements in 2026 include Gap coverage automatically within the lease contract. It is vital to verify this before purchasing a separate policy from your insurance provider. If it is not included in the lease, adding it to your personal auto insurance policy typically costs between $20 and $60 per year, which is a marginal but necessary addition to your total insurance expenditure.
Comparing Insurance Costs: Leased vs. Financed vs. Owned
To truly understand the cost of insuring a leased car, it helps to compare it to other forms of vehicle "ownership." While the insurance requirements for a financed car and a leased car are similar, the leased car often ends up being more expensive due to the specific liability mandates and the lack of flexibility in choosing deductibles.
- Owned Outright: You have total flexibility. You can choose high deductibles or drop collision and comprehensive coverage entirely on older vehicles. This is the cheapest way to insure a car but carries the highest personal financial risk.
- Financed (Loan): The lender requires full coverage and usually limits deductibles to $1,000. However, they may not require the 100/300/50 liability limits that lessors demand.
- Leased: This is the most restrictive and generally the most expensive. You must maintain high liability limits, low deductibles, and Gap coverage for the duration of the term.
Factors Influencing Your 2026 Premiums
While the lease status sets the "floor" for your insurance requirements, several other factors will determine the final number on your bill. In 2026, insurance algorithms have become increasingly granular.
Vehicle Type and Technology
The specific model you lease is the largest variable. A luxury SUV with complex sensor arrays in the bumpers will cost significantly more to insure than a standard sedan. In 2026, the cost of parts and the labor required for "calibration" after a minor fender bender can drive up the comprehensive and collision portions of your premium. According to the Insurance Information Institute, the cost of high-tech repairs is a leading factor in rising premiums nationwide.
Geographic Location
Where you garage the car matters. If you live in an area prone to flooding, hail, or high rates of vehicle theft, your comprehensive coverage costs will reflect that risk. Urban areas with high traffic density also see higher liability and collision rates due to the statistical likelihood of an accident.
Personal Risk Profile
Your credit-based insurance score, driving record, and age remain foundational. Even though the lease requires specific coverage, a driver with a history of at-fault accidents will pay a massive premium for those high mandated limits compared to a driver with a clean record.
Strategies for Reducing Leased Car Insurance Costs
Despite the rigid requirements imposed by leasing companies, there are ways to manage and potentially lower your costs.
- Shop Before You Sign: Before finalizing a lease, get an insurance quote for that specific VIN or model. Many consumers are surprised to find that the insurance on a "deal" lease is so high it negates the monthly savings on the car payment.
- Bundle Policies: Combining your auto insurance with a renters or homeowners policy remains one of the most effective ways to secure a multi-policy discount, often ranging from 5% to 15%.
- Inquire About Telematics: In 2026, most major insurers offer "pay-how-you-drive" programs. By allowing the insurer to monitor your driving habits via a smartphone app or vehicle plug-in, you can earn significant discounts for safe driving behavior, which helps offset the cost of higher mandated limits.
- Check for Group Discounts: Many employers, alumni associations, and professional organizations offer group insurance rates that are lower than what you can find on the open market.
- Verify Gap Coverage: Do not pay for Gap insurance twice. Review your lease agreement carefully to see if "Gap Waiver" or "Gap Insurance" is already included in your "Gross Capitalized Cost."
Understanding the "Total Loss" Scenario
The most complex aspect of leased car insurance cost is how it functions during a total loss. If your car is destroyed, your insurance company issues a check for the market value. In a lease, that check goes directly to the lessor (the owner).
If the market value is $30,000 but your lease payoff is $34,000, the Gap insurance covers the $4,000 difference. If you didn't have Gap insurance, you would owe that $4,000 immediately to terminate the lease. This highlights why the "cost" of the insurance is actually a protective measure against a much larger sudden expense.
It is also important to note that any down payment (Capitalized Cost Reduction) you made at the start of the lease is generally lost in a total loss scenario. Insurance pays the value of the car to the owner, not your initial investment to lower the monthly payments. This is why many financial experts recommend putting as little money down as possible on a lease.
Common Pitfalls and Misunderstandings
One frequent mistake lessees make is assuming their insurance from a previous, owned vehicle will suffice for the new lease. If you transfer a policy that only has 25/50/25 liability limits to a leased vehicle, you are likely in violation of your lease contract.
If the leasing company discovers your coverage is insufficient—which they will, as they are listed as the "Additional Insured" and "Loss Payee" on your policy and receive notifications of changes—they may purchase "force-placed insurance." This is a policy the lessor buys to protect their interest, and they will bill you for it. Force-placed insurance is notoriously expensive and provides no liability protection for you, only physical damage protection for the car.
Next Steps for Prospective Lessees
Before you visit the dealership, contact your insurance agent with the make and model of the vehicle you are considering. Ask for a quote that specifically meets the 100/300/50 liability requirement and includes a $500 deductible for collision and comprehensive. This will give you the most accurate picture of your total monthly cost of operation.
Frequently Asked Questions
Does leased car insurance cost more than financed car insurance? Generally, yes. While both require collision and comprehensive coverage, leasing companies often mandate higher liability limits (such as 100/300/50) than what a bank might require for a standard auto loan. Additionally, Gap insurance is a more common requirement for leases.
Can I choose my own insurance company for a leased car? Yes, you have the freedom to choose any insurance provider that is licensed in your state, provided the policy meets the minimum coverage requirements outlined in your lease agreement. Shopping around is encouraged to find the most competitive rate for the mandated coverage levels.
What happens if I don't maintain the required insurance on a lease? If you let your insurance lapse or lower your coverage below the lessor's requirements, you are in default of your lease contract. The leasing company can repossess the vehicle or purchase force-placed insurance at your expense, which is much costlier than standard insurance.
Is Gap insurance always required for a lease in 2026? While not legally required by the state, almost all leasing companies require Gap insurance or include a Gap waiver in the contract. This protects the lessor from a financial loss if the car is totaled and the insurance payout doesn't cover the remaining lease balance.
Can I have a $1,000 deductible on a leased car? Most leasing companies allow a deductible of up to $1,000, but some may strictly require a $500 limit. You must check the specific language of your lease agreement. Choosing a higher deductible usually lowers your premium but increases your out-of-pocket cost if you have an accident.
Image Gallery
Select an image to open it in a new tab.
Zara El-Hashem
Sociocultural Dynamics and Academics Writer
